 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
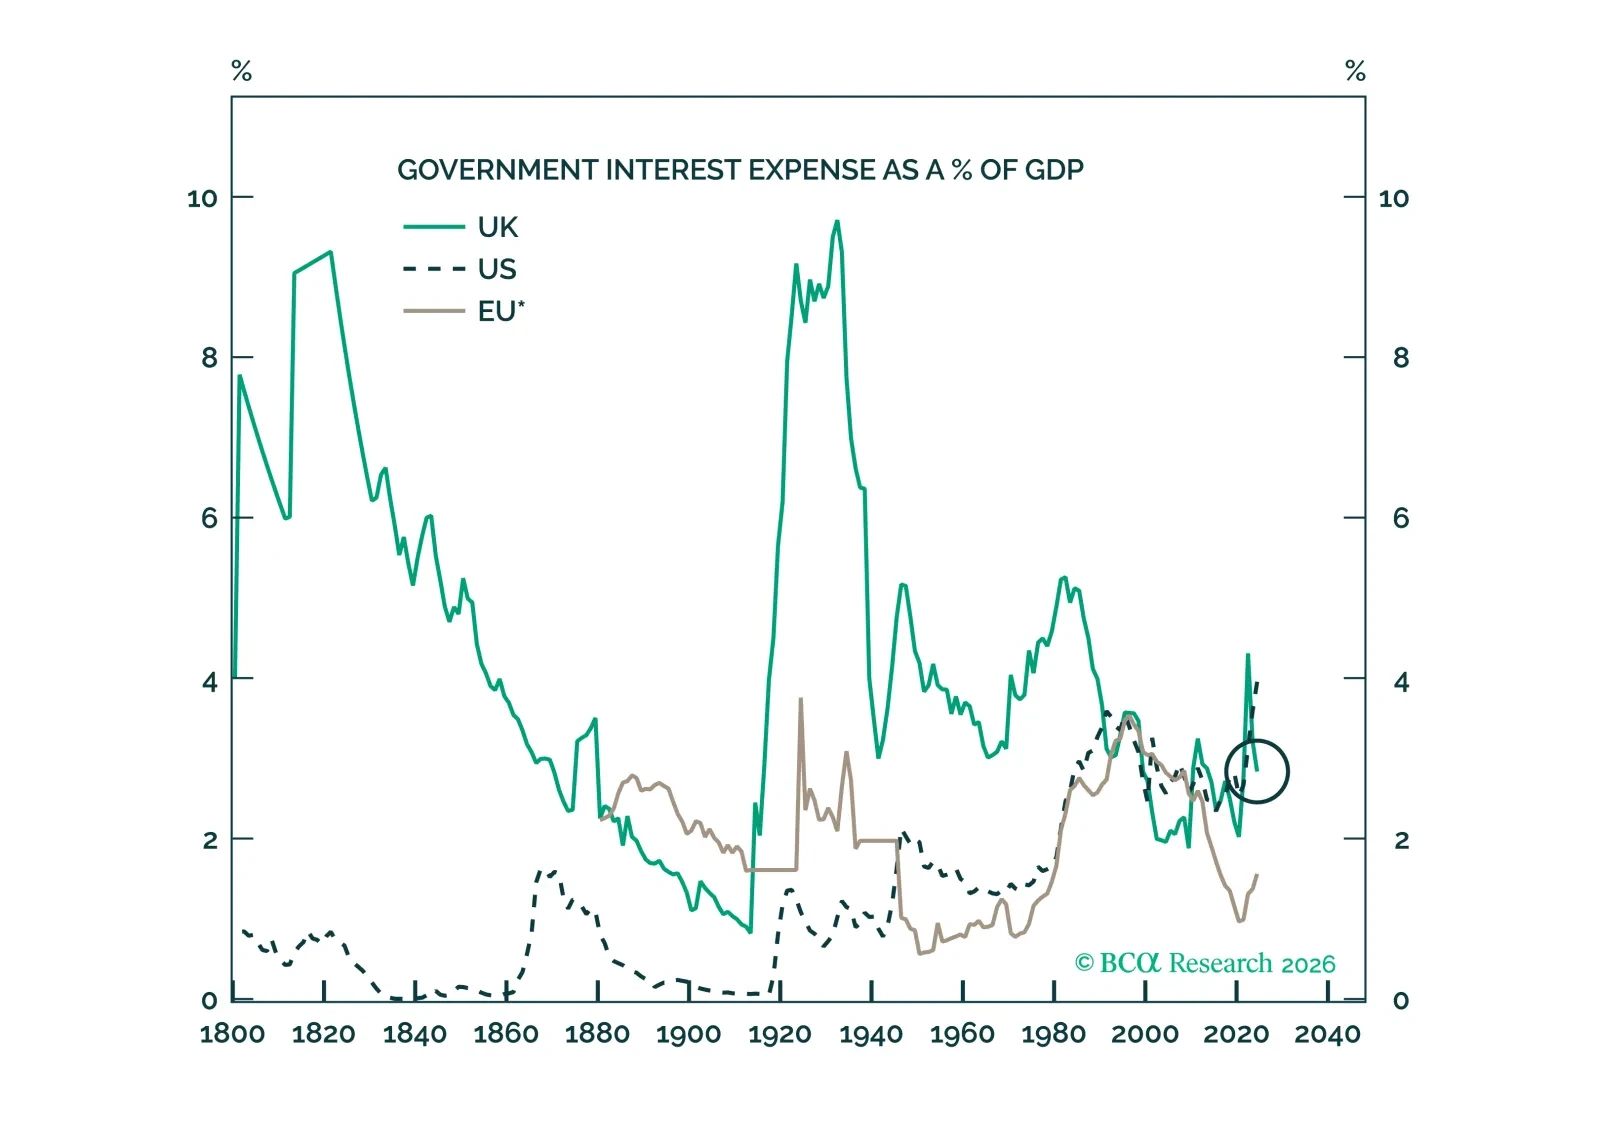
Stay overweight gilts despite renewed political turmoil in the UK.
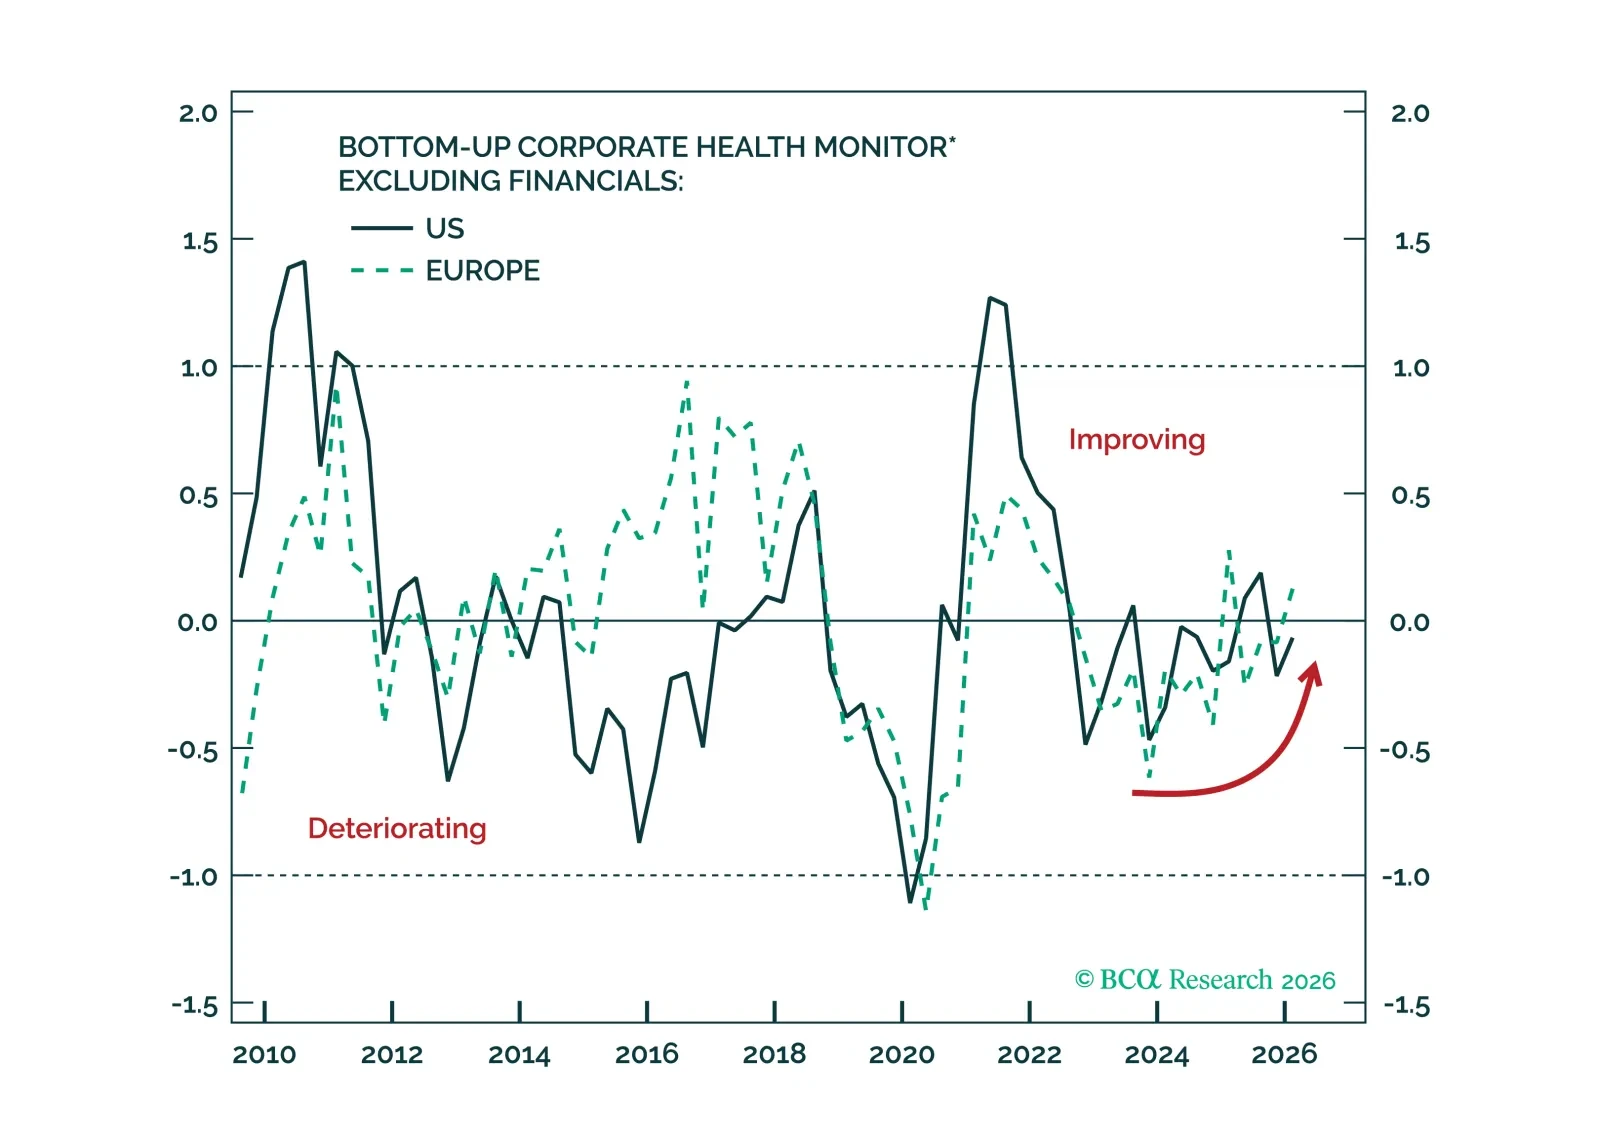
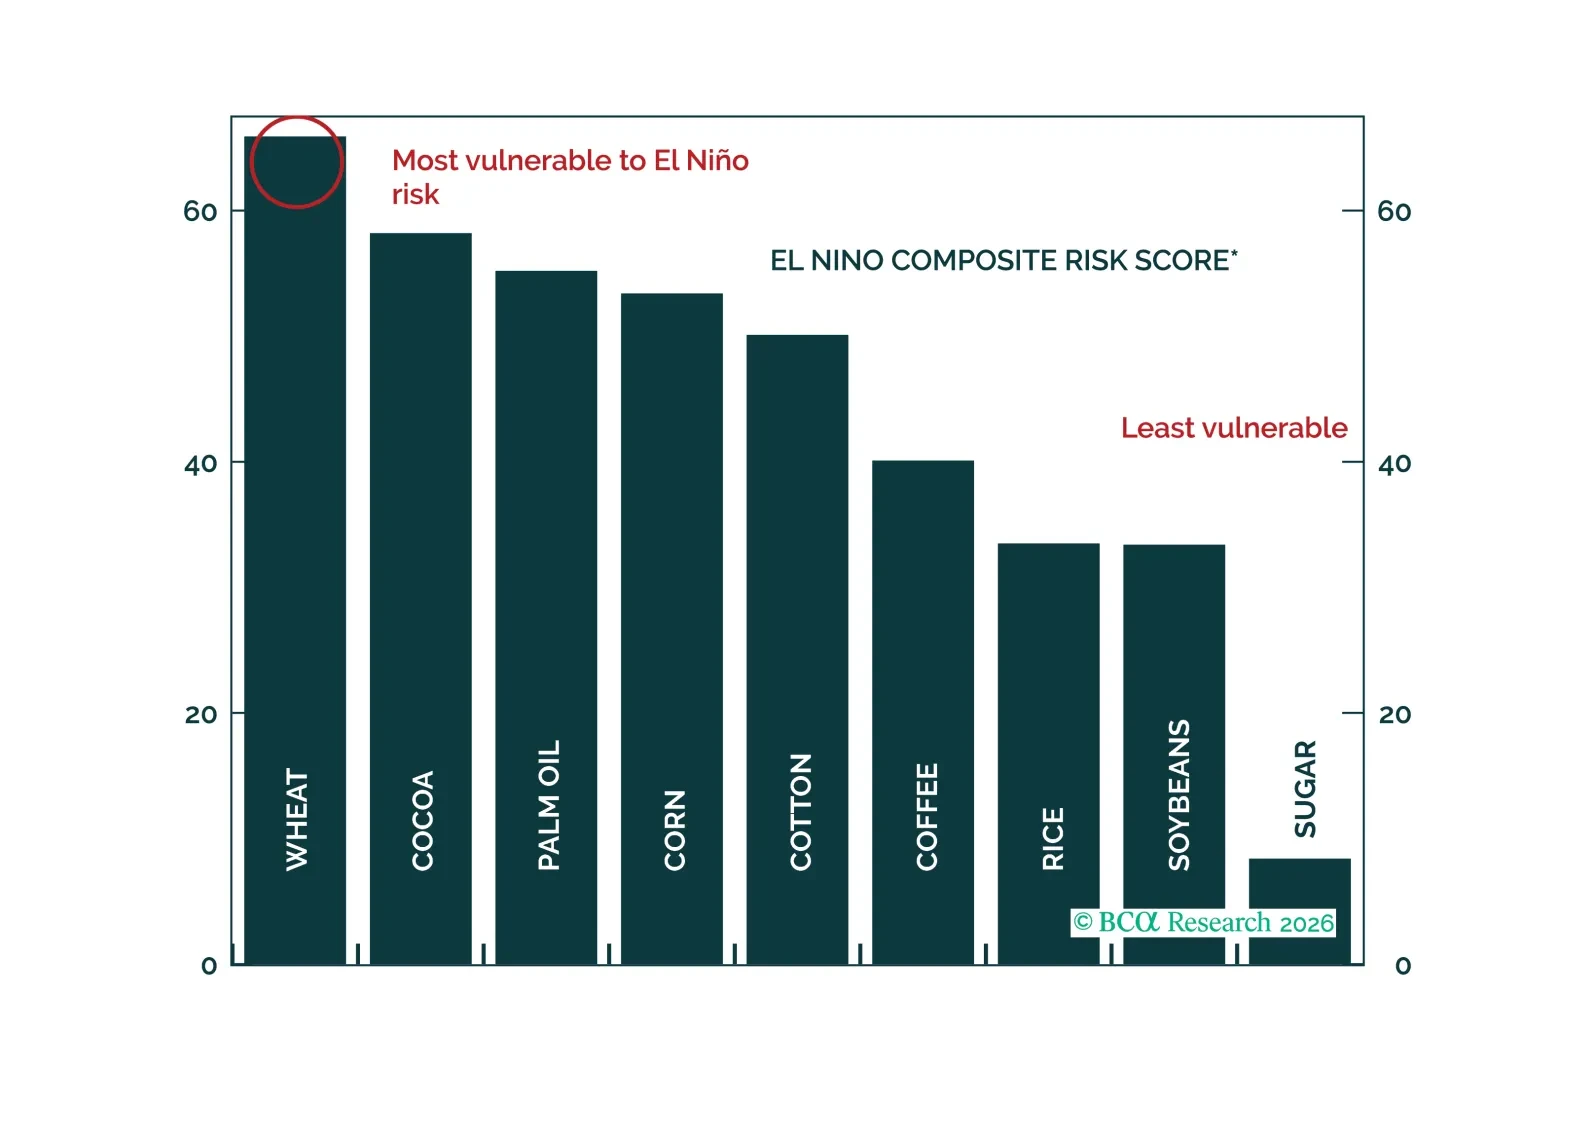
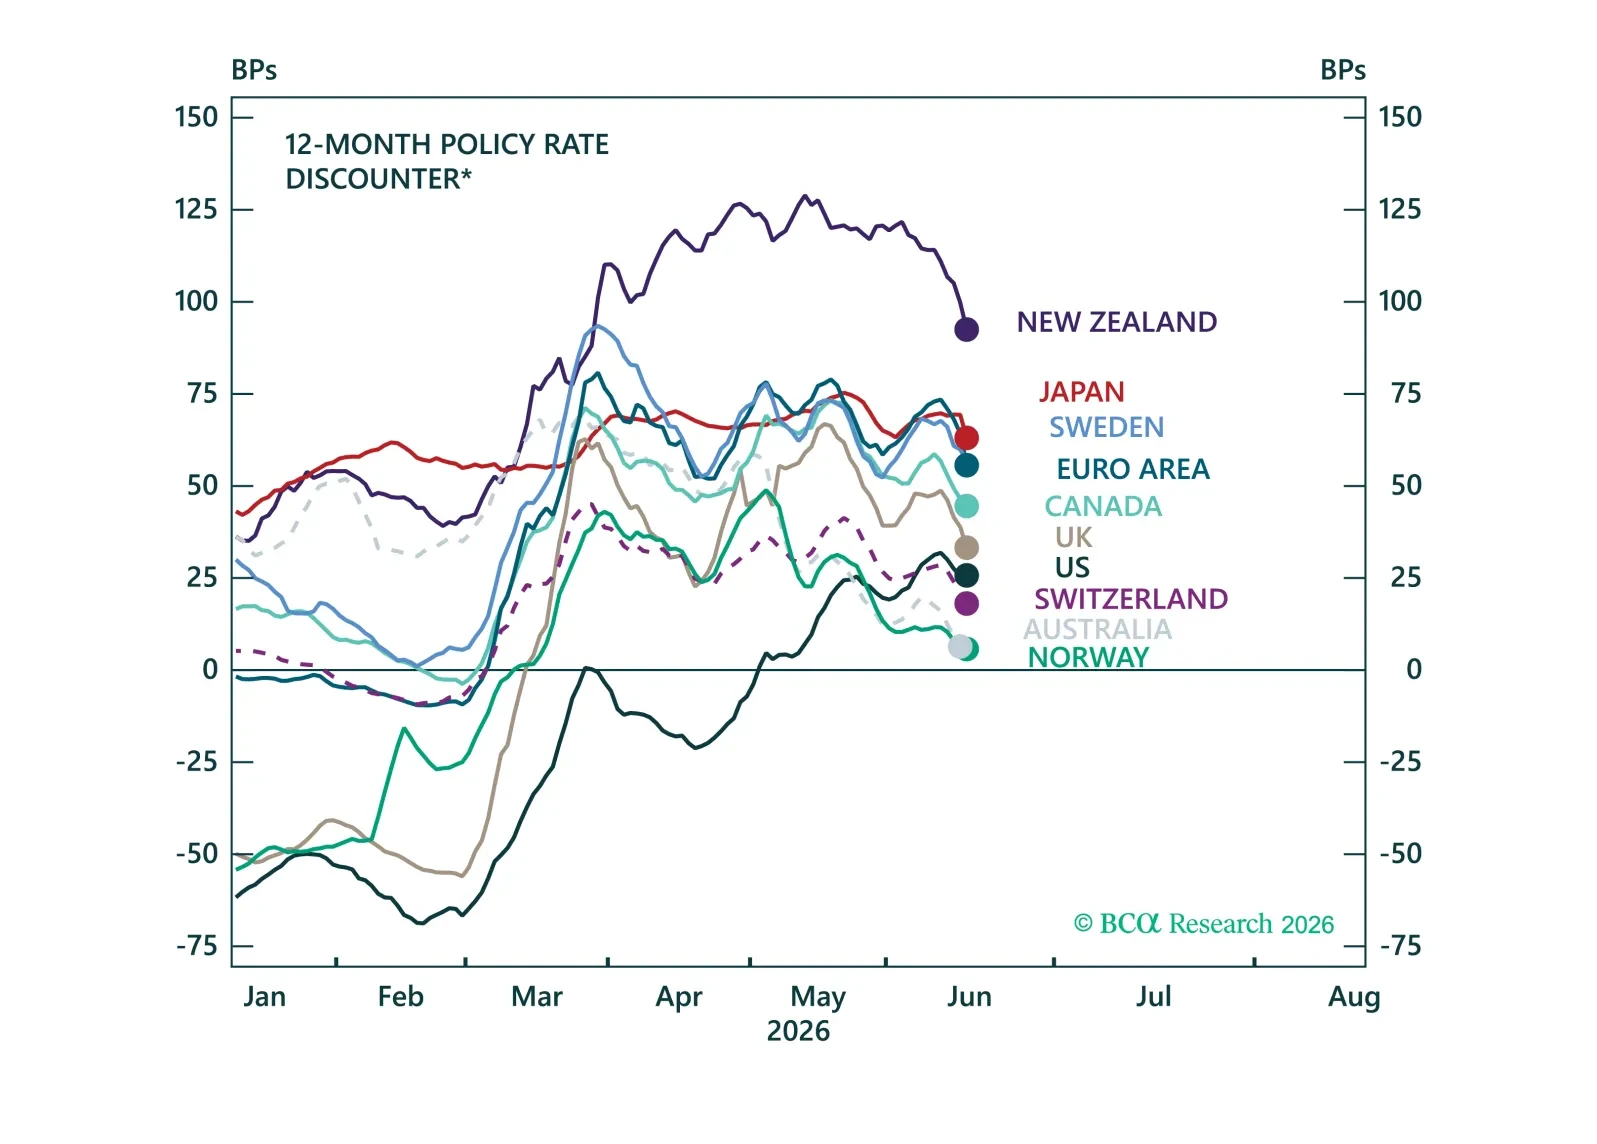
We react to DM central bank meetings this week and highlight the opportunities emerging across global fixed income and currency markets.
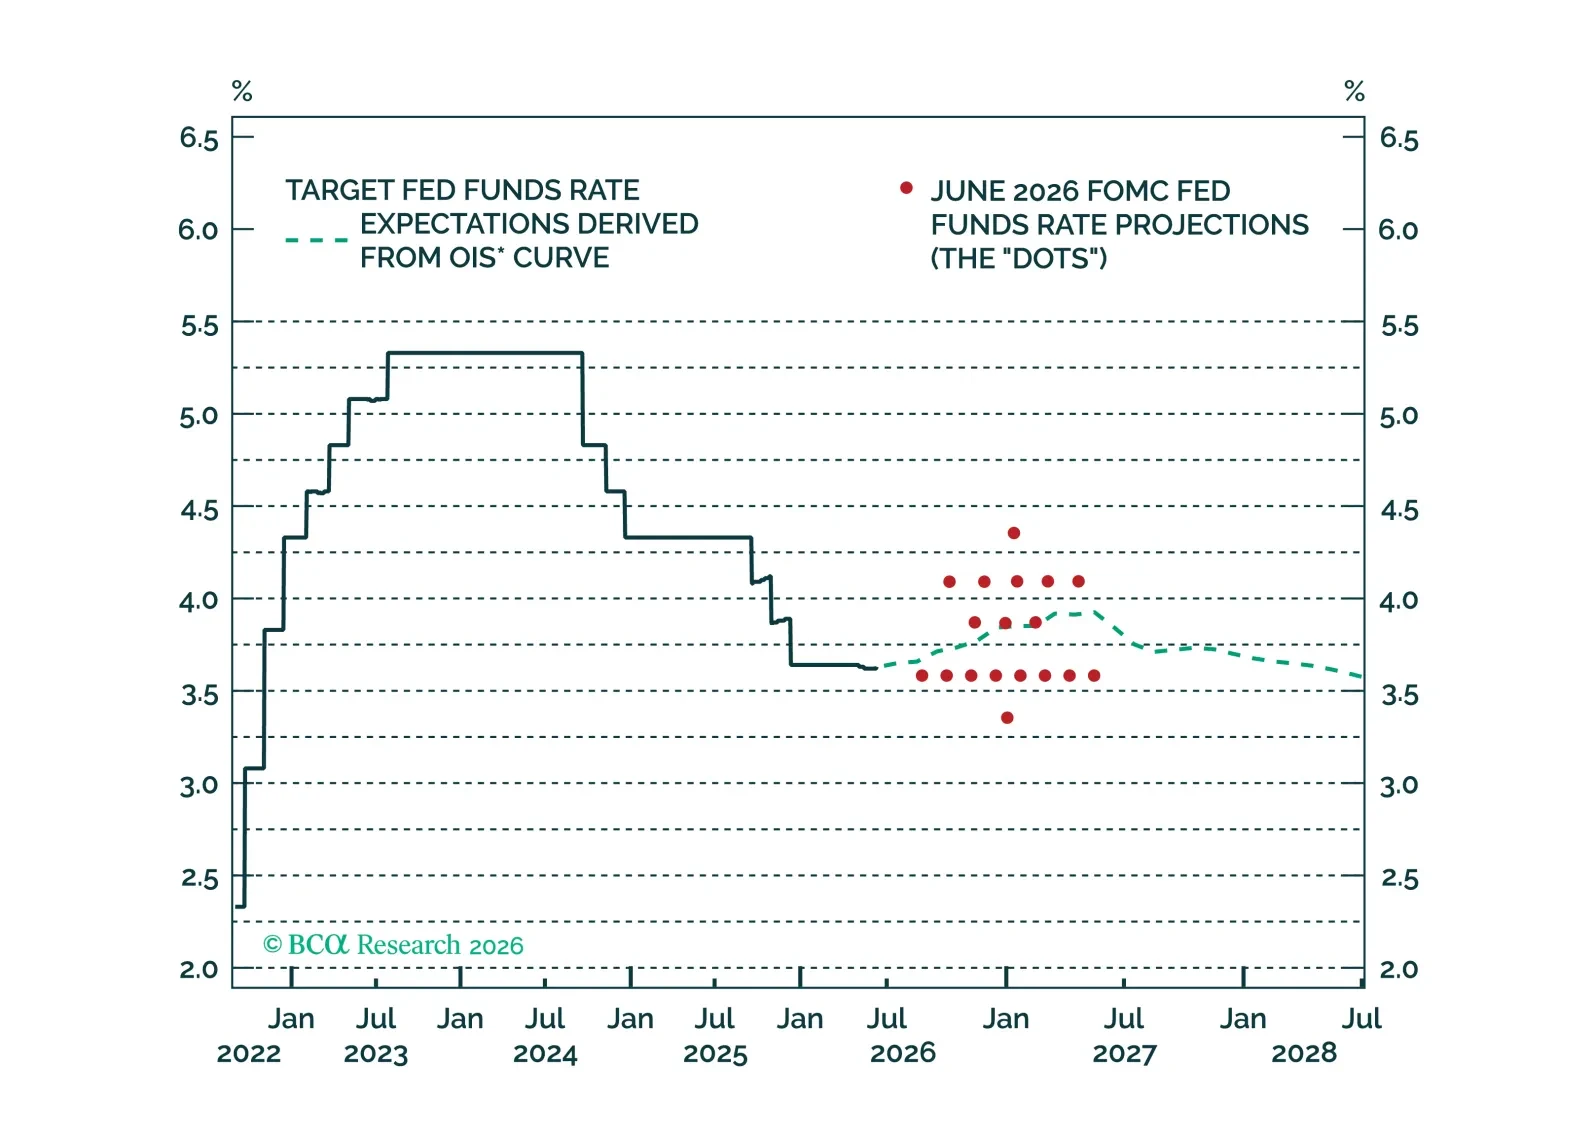
Kevin Warsh announced an ambitious reform agenda for the Federal Reserve. We discuss the potential impact and the current outlook for interest rates.
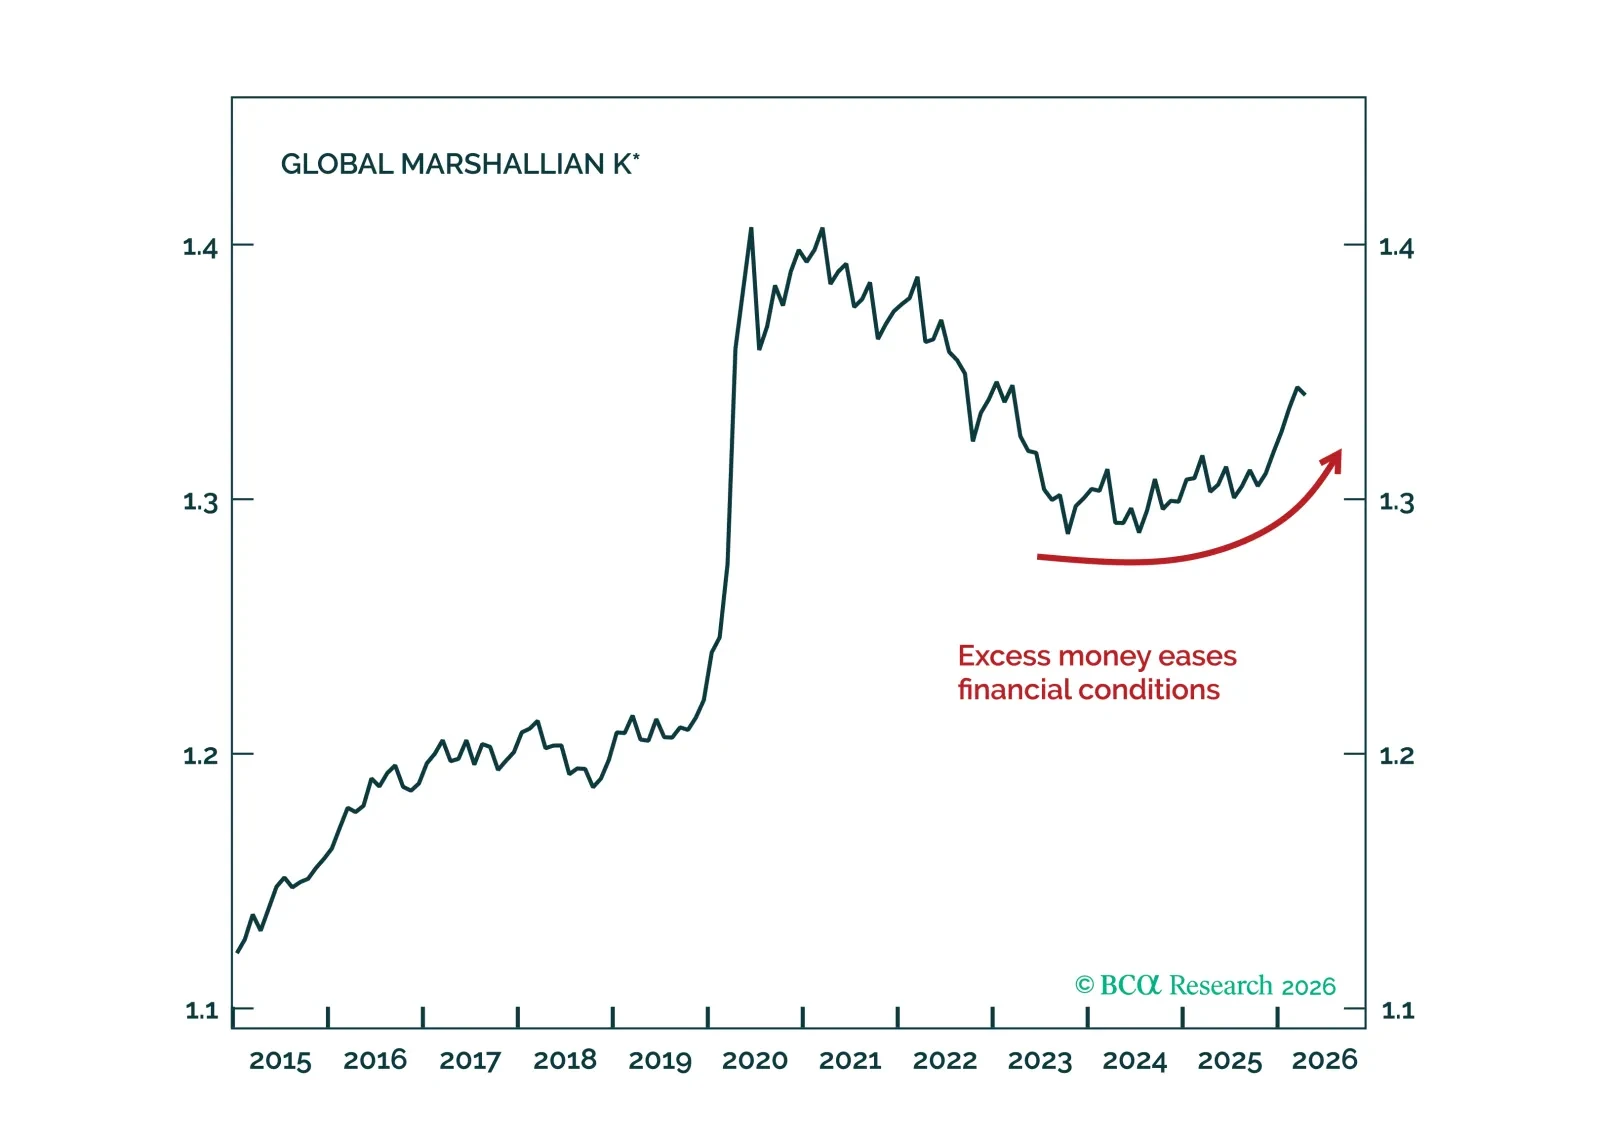
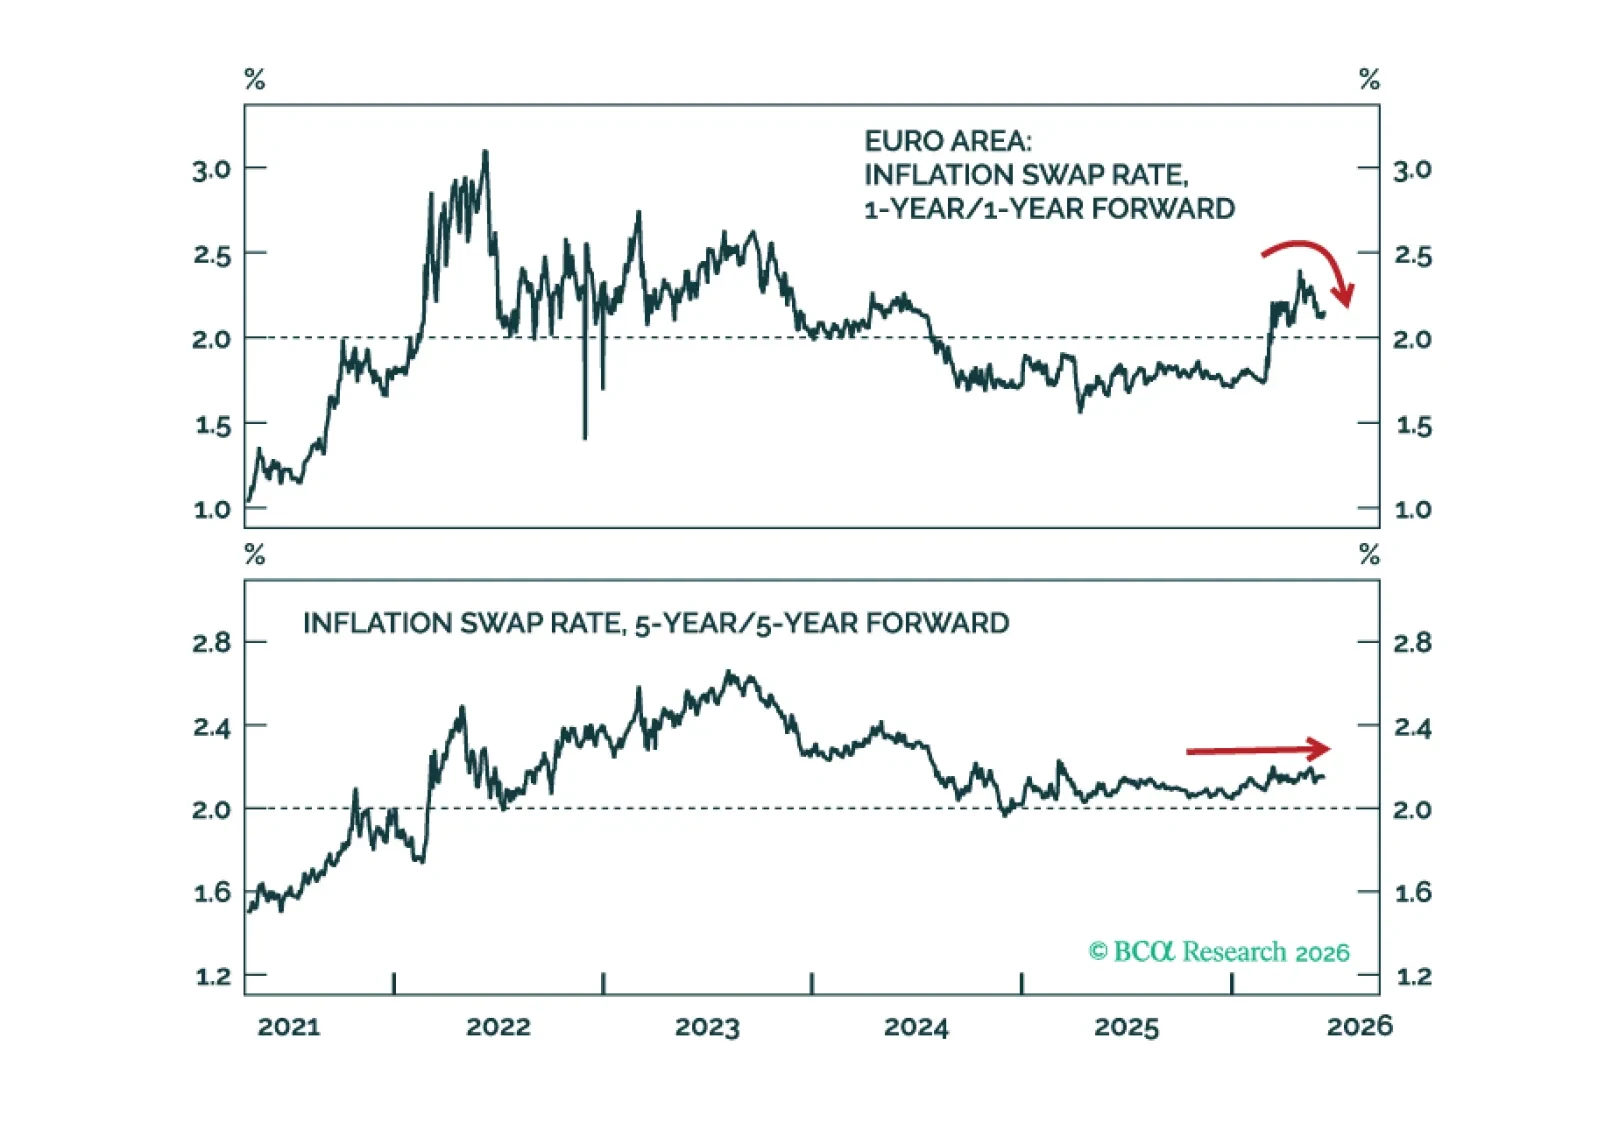
Today’s ECB rate hike is not the beginning of a hiking cycle. Growth concerns will soon move to the forefront of ECB policy decisions, preventing further tightening.
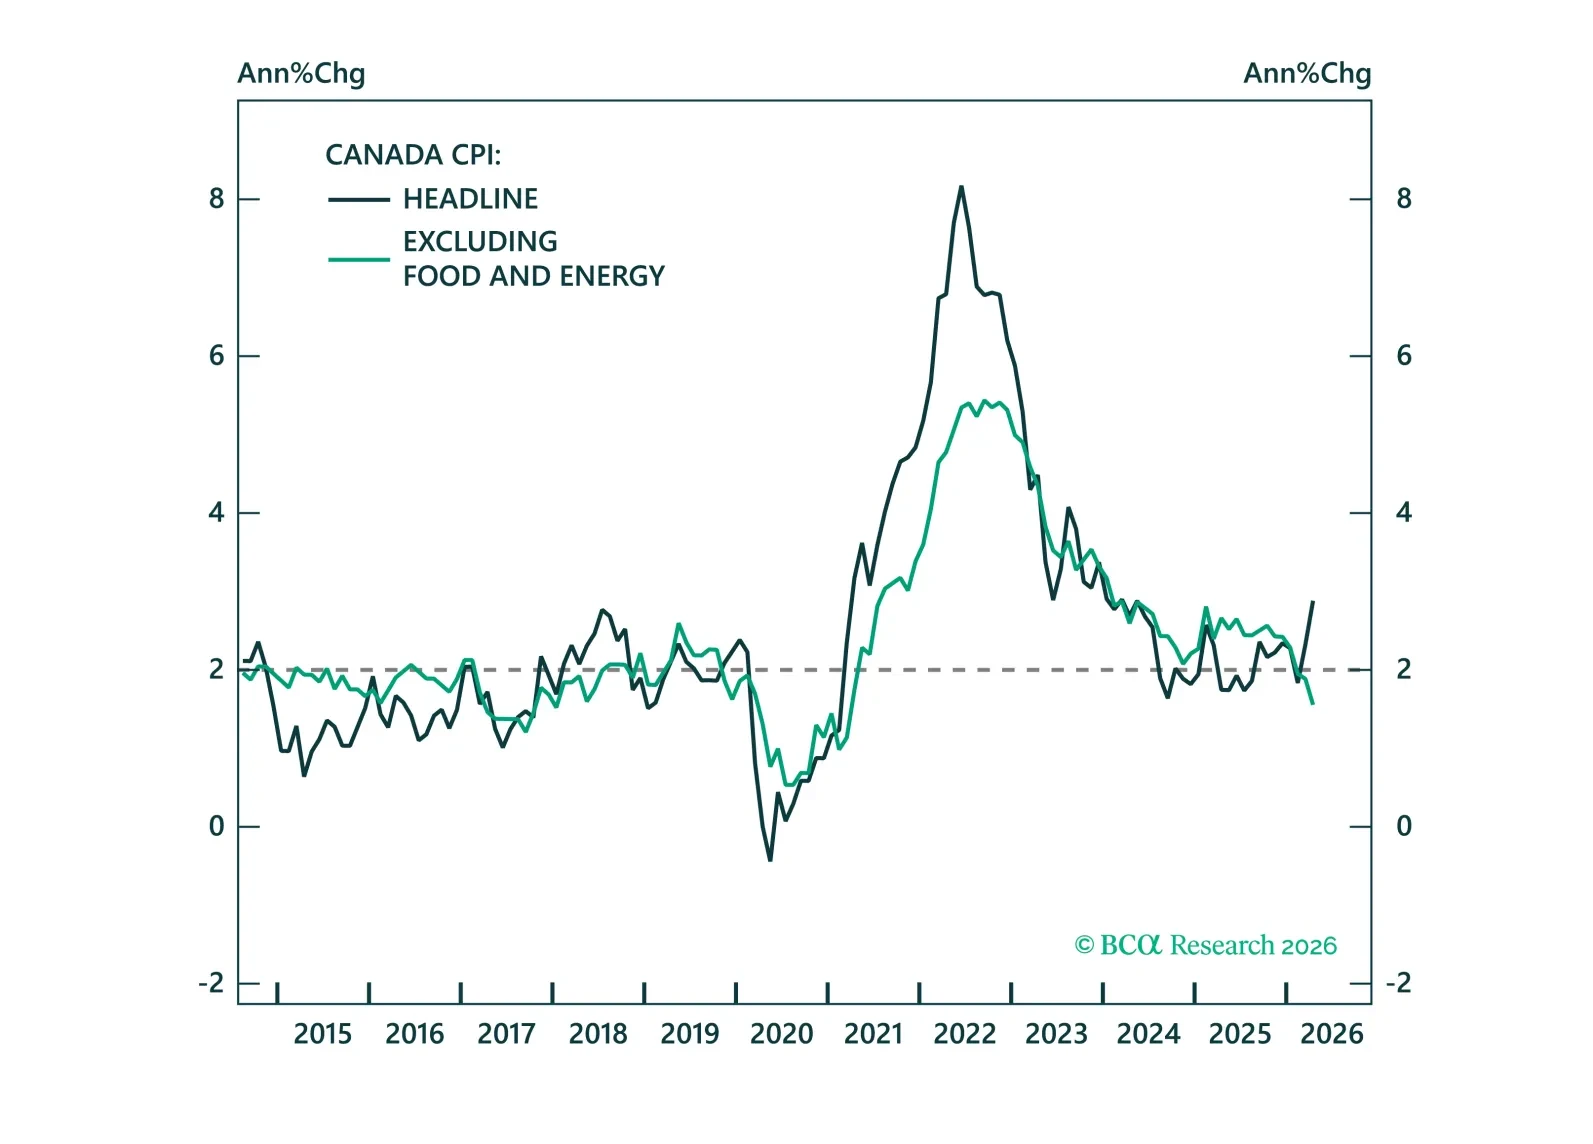
The Bank of Canada left rates unchanged and emphasized inflation risks from higher oil prices. We discuss why inflation and labor market data argue against the tightening currently priced.
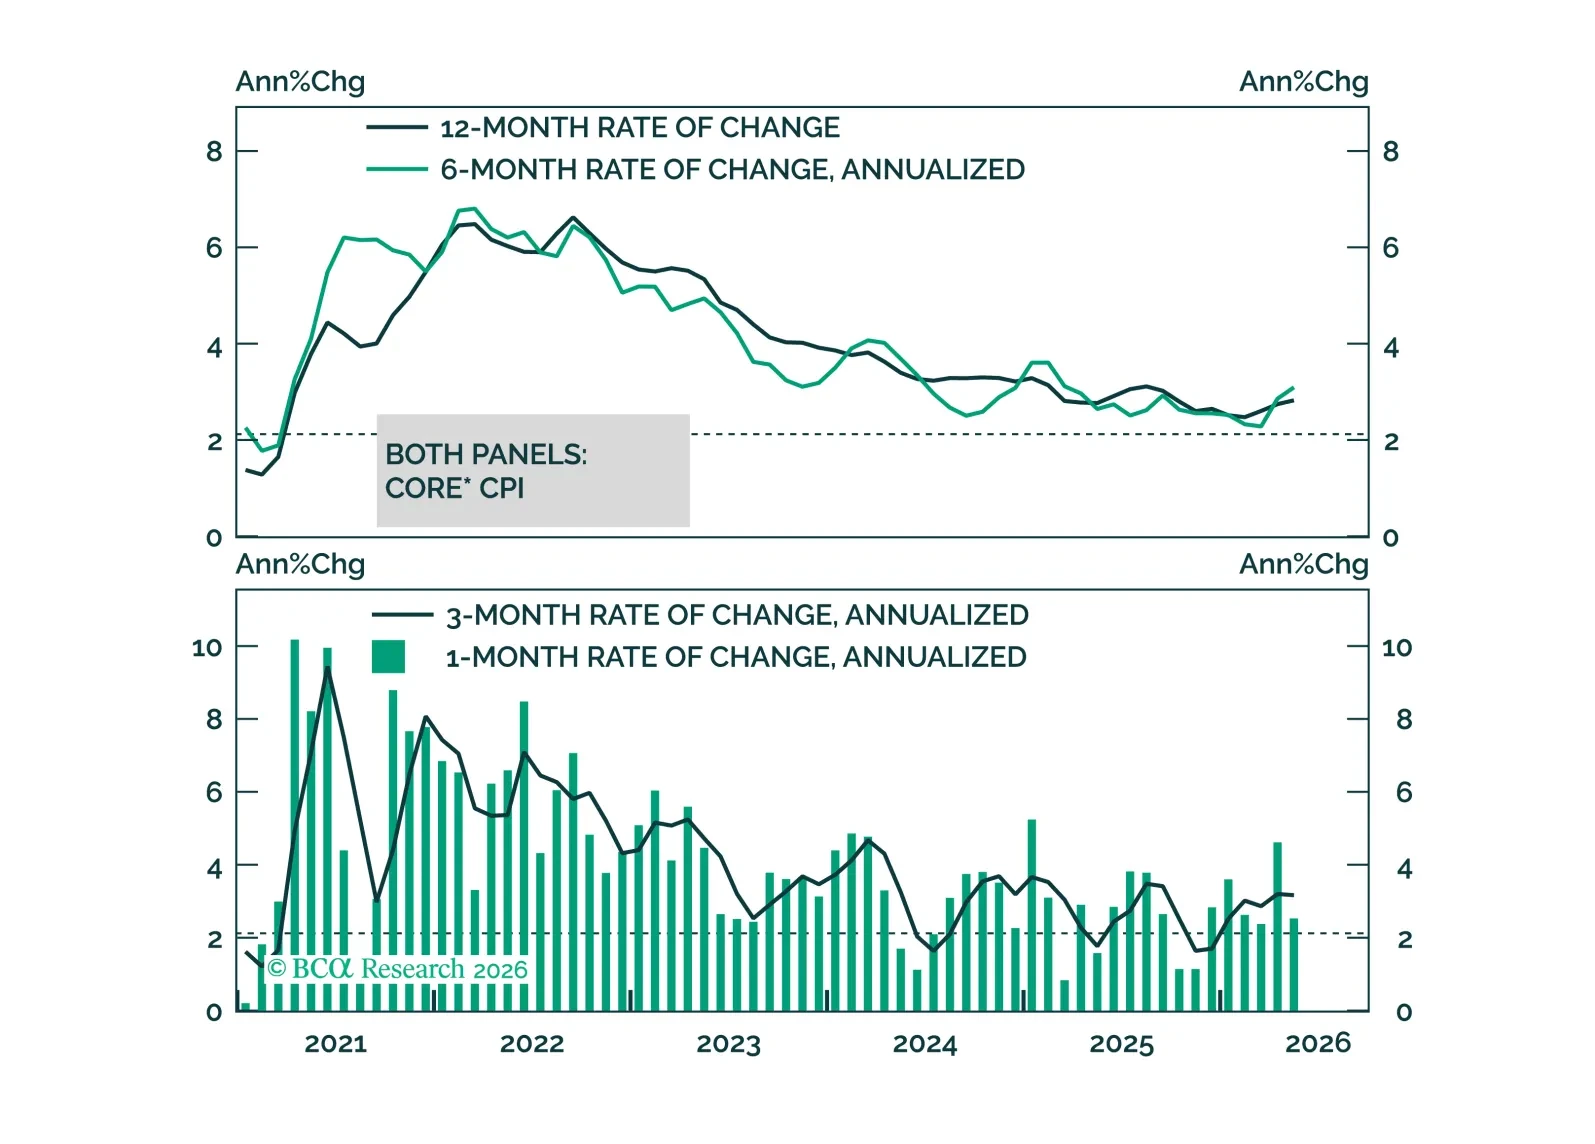
May CPI data show no evidence of passthrough from energy prices to core inflation. This will keep the Fed on hold for the time being.
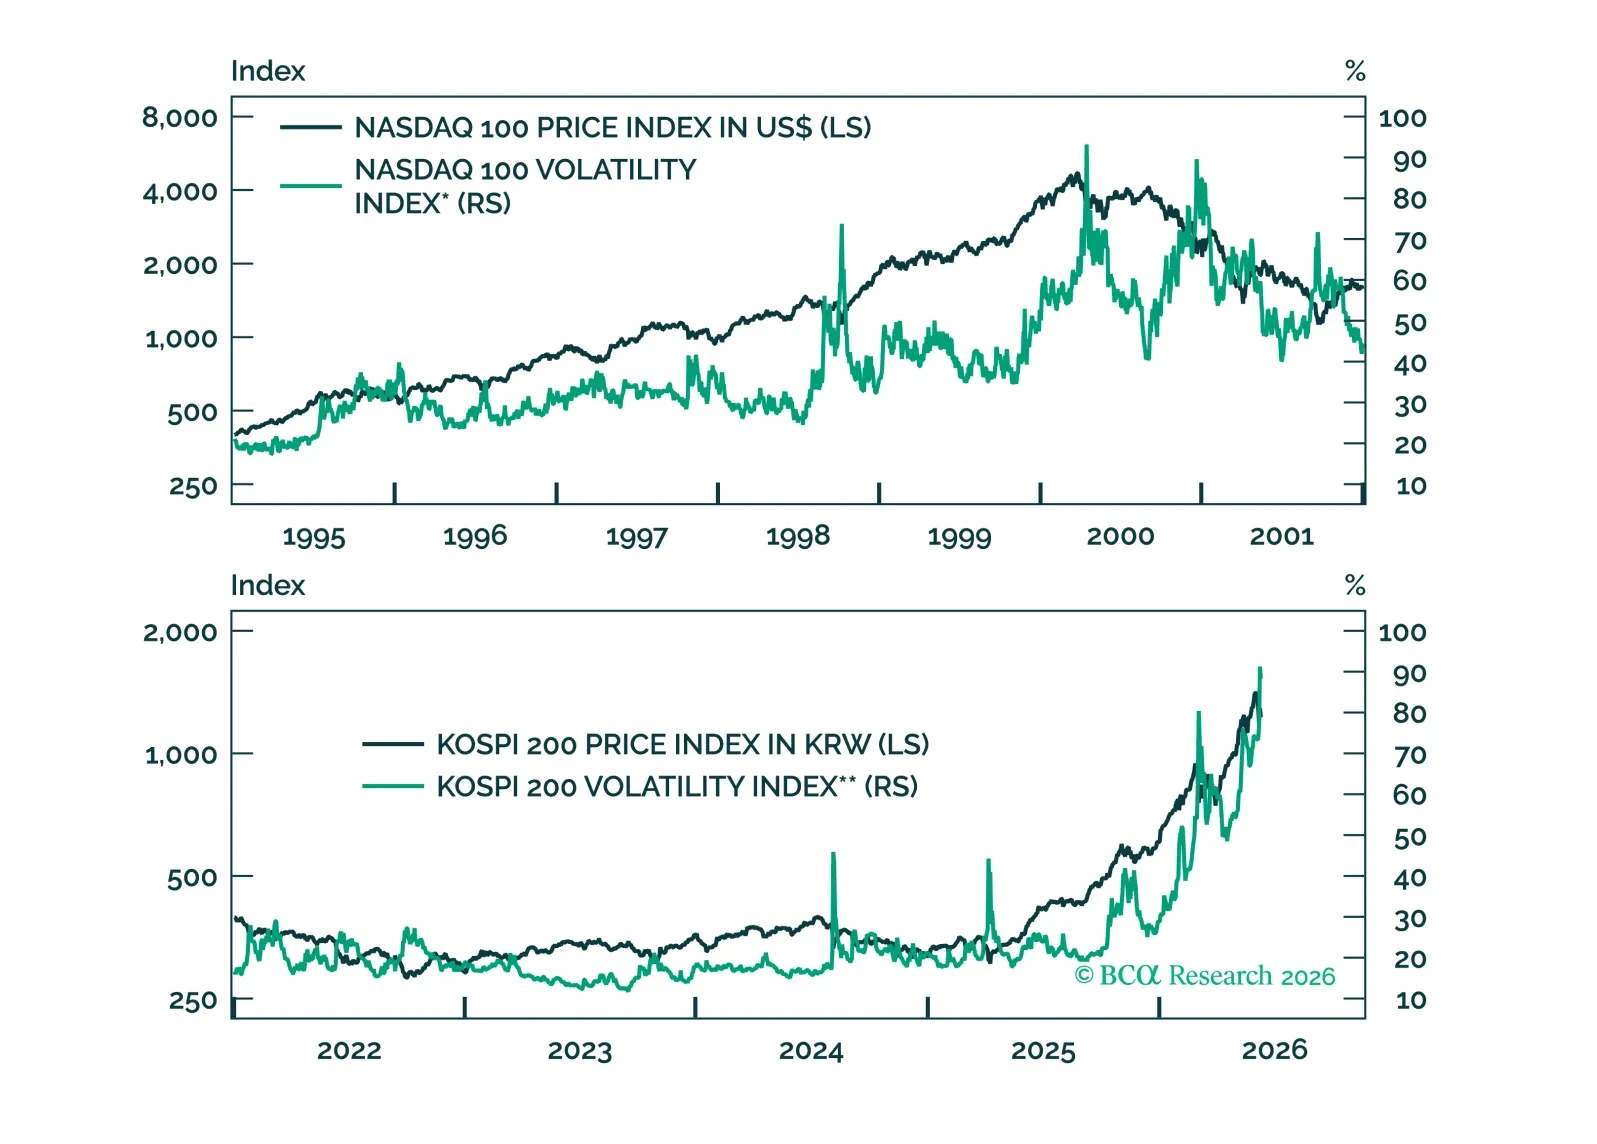
Rising volatility in Korean markets captures a late-cycle surge in which euphoria and drawdown risk are rising together. While KOSPI momentum remains intact, the bigger opportunity may be emerging in the increasingly mispriced KRW, which could rally meaningfully as portfolio flow headwinds fade.