 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
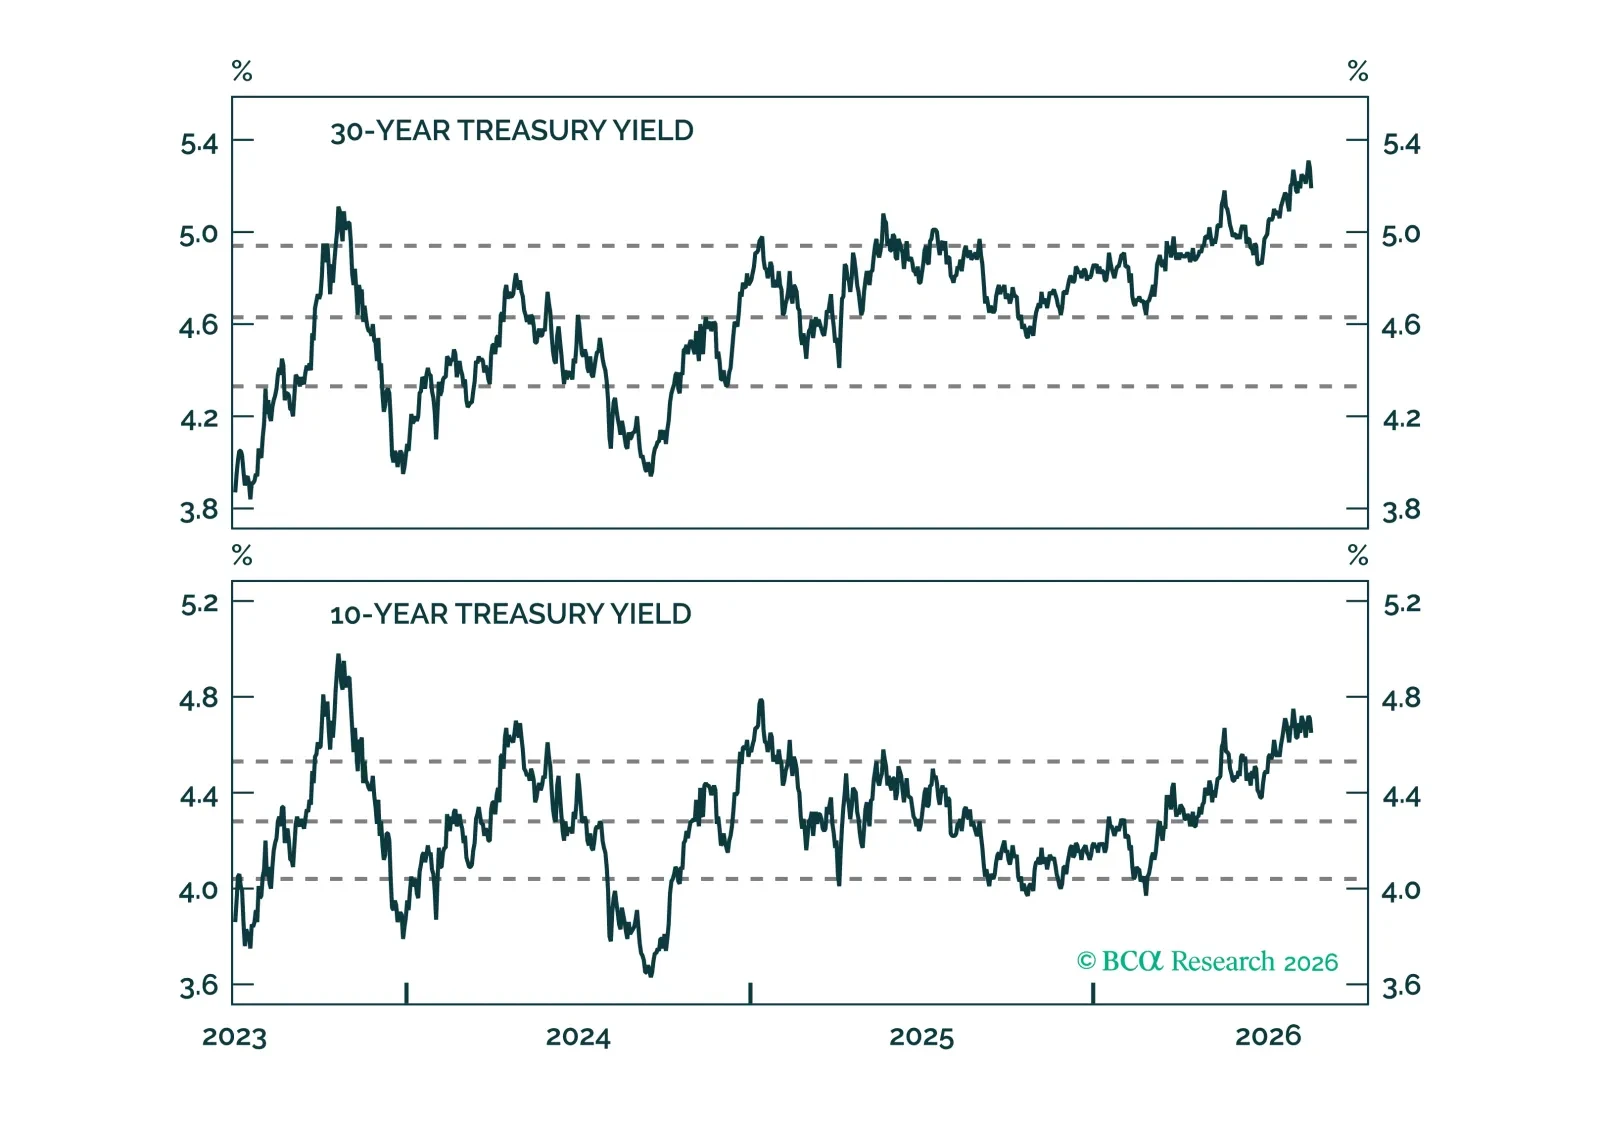
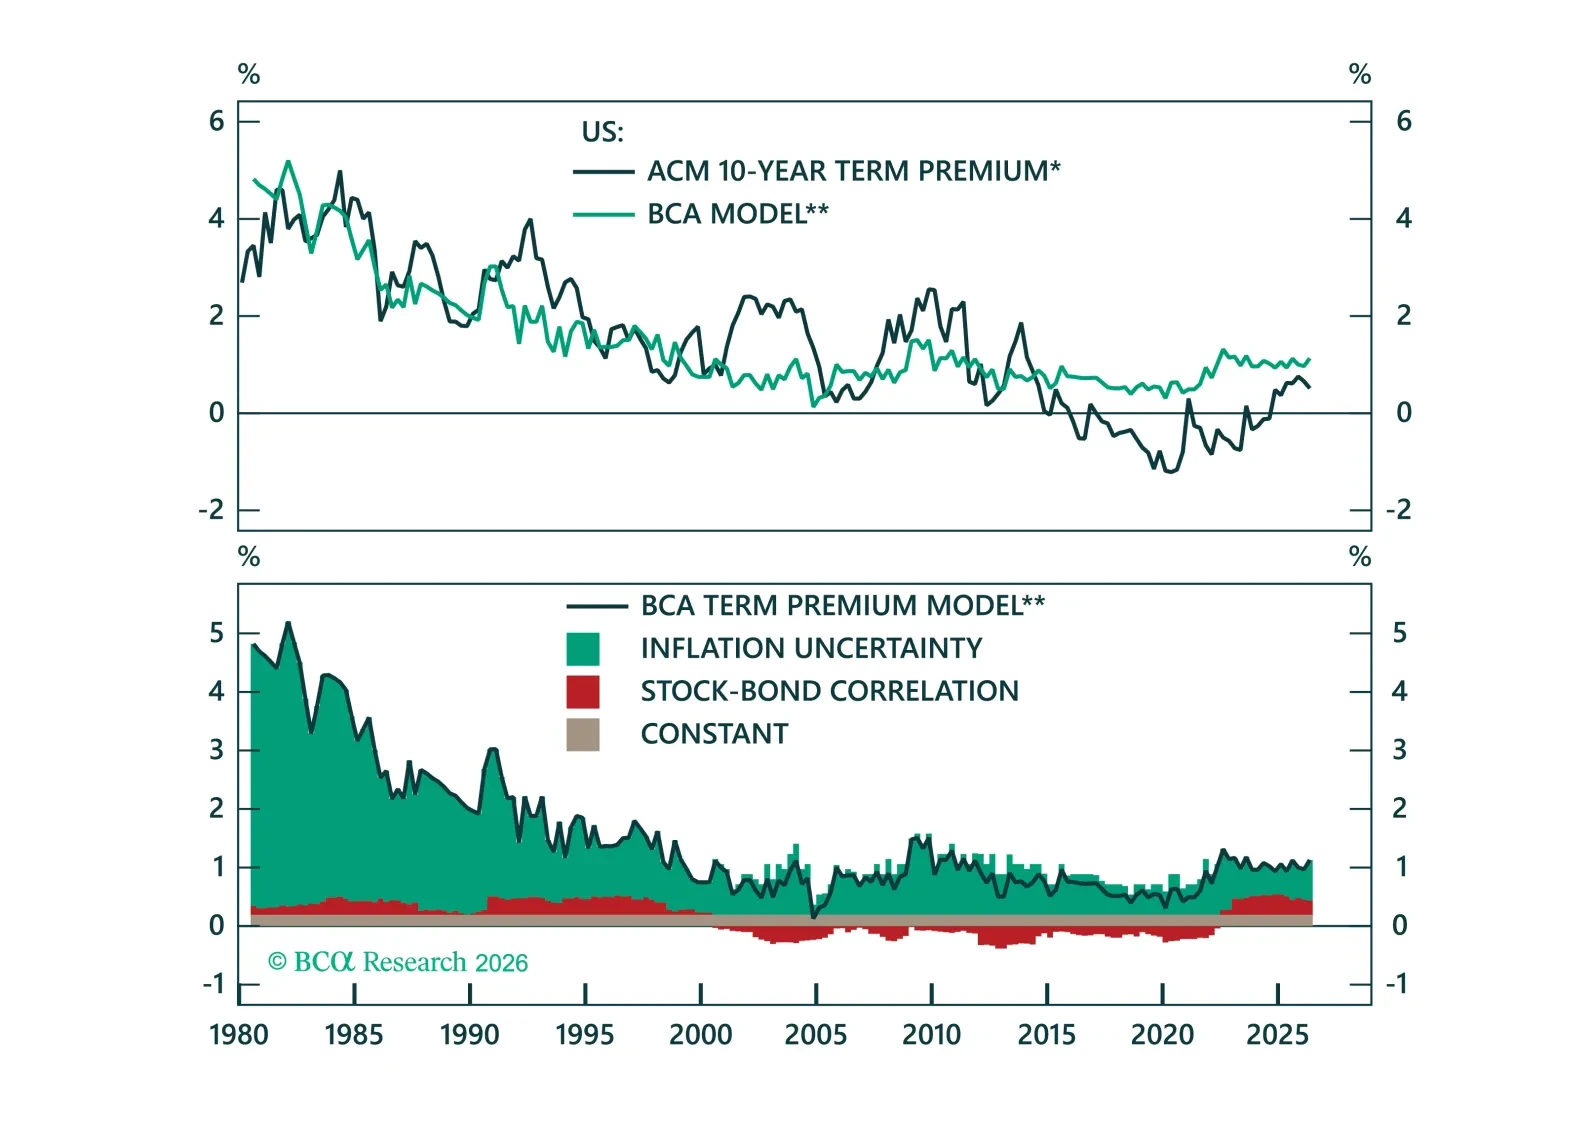
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.
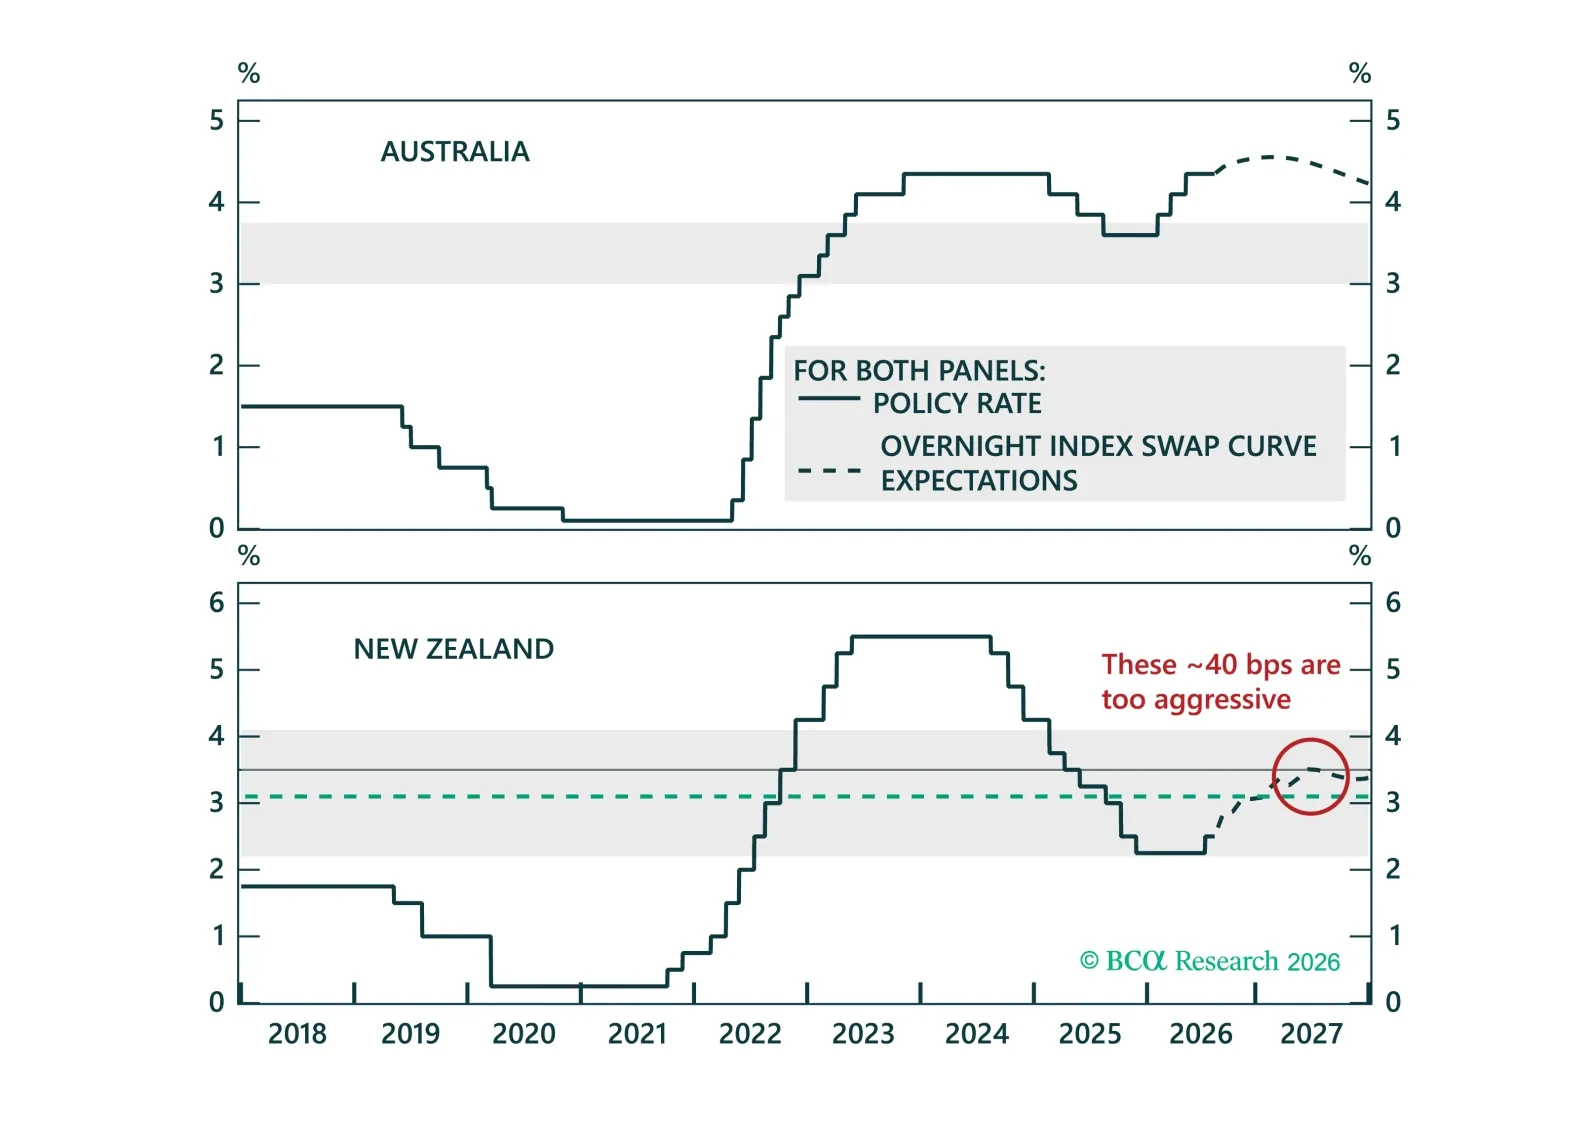
The RBA is likely done hiking, and the RBNZ overpriced for more hikes. We trace both conclusions back to housing, credit, and external dynamics, with implications for our country allocation in ANZ bonds and our long AUD/NZD view.
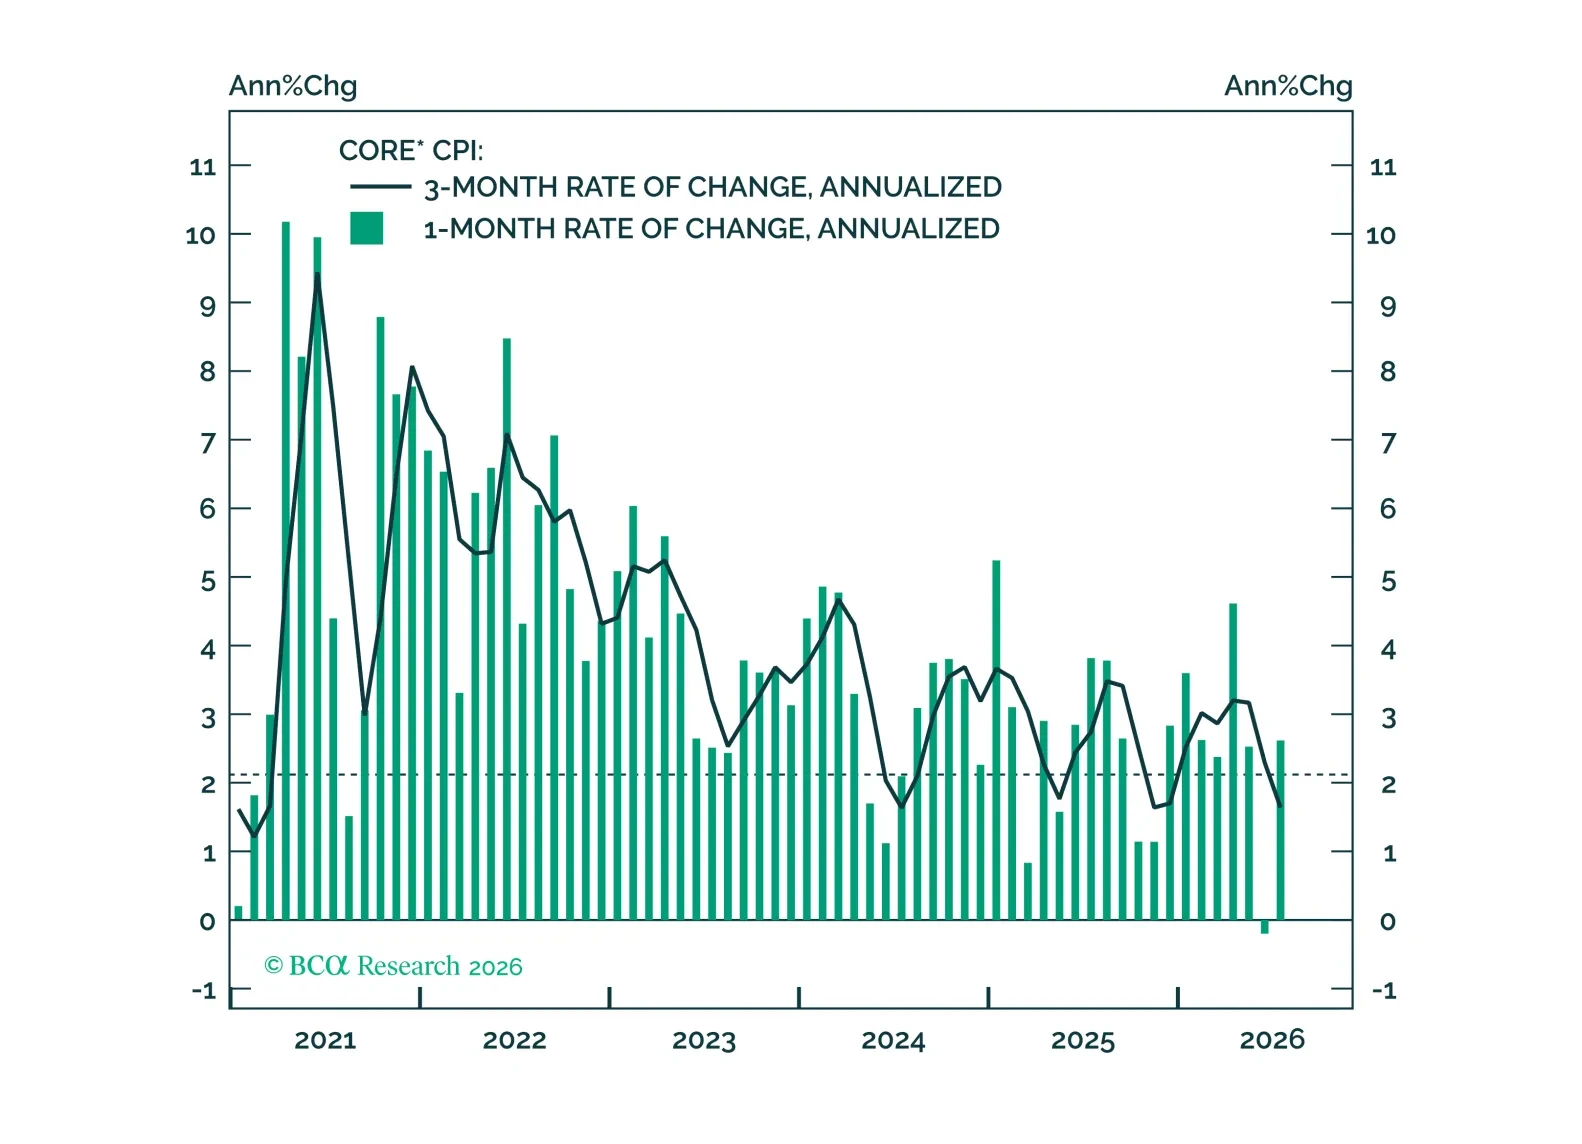
July’s CPI reading was low enough to keep the Fed on hold for now, but near-term upside inflation risks remain.
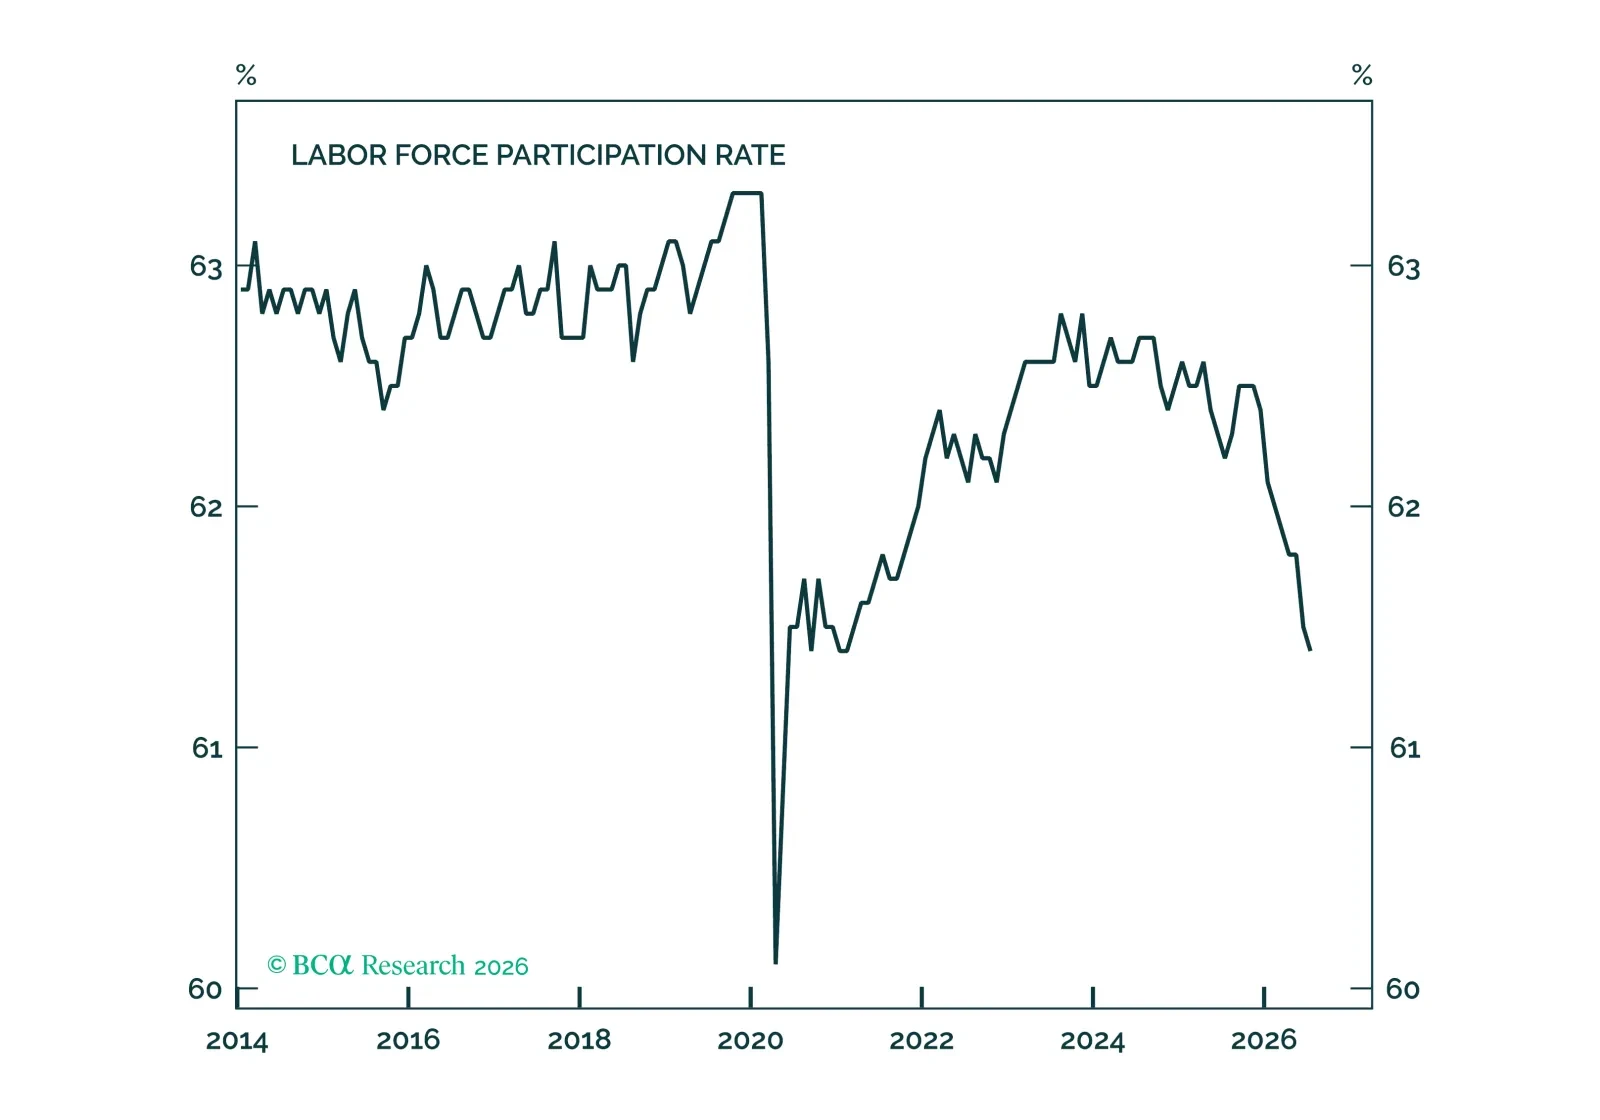
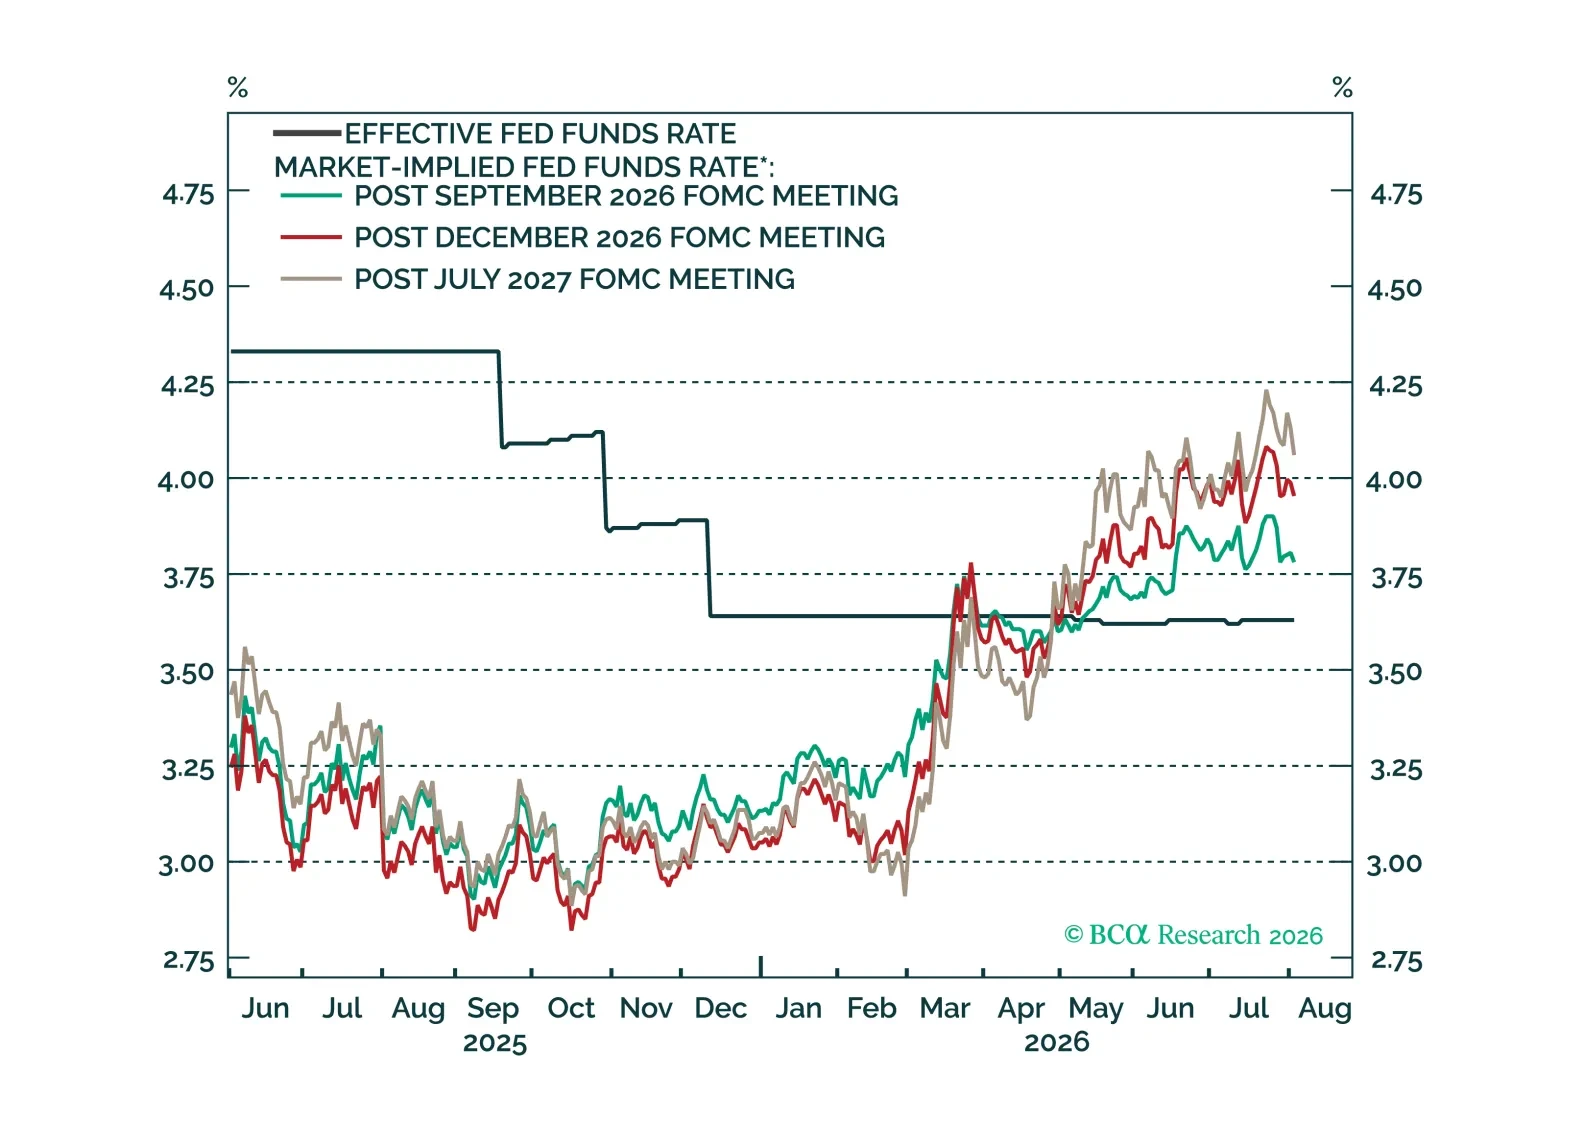
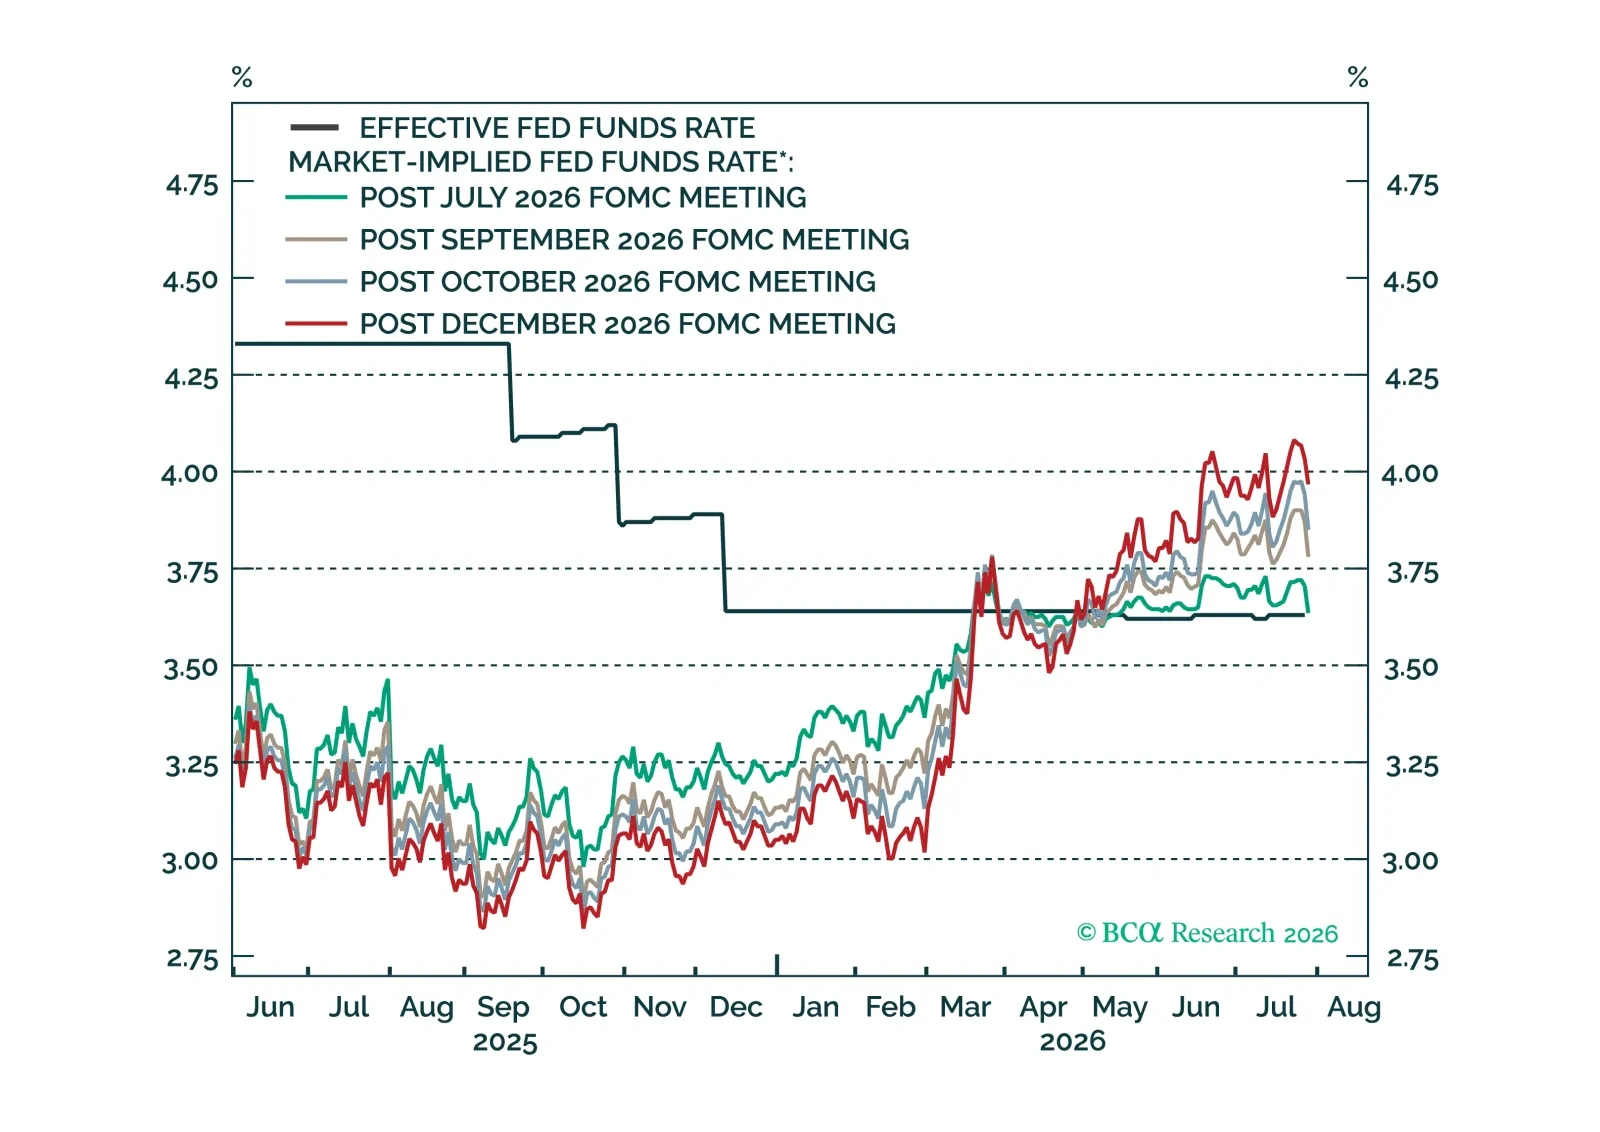
Despite today’s hold, the bar for a rate hike in September remains low and contingent on the next two core CPI reports.
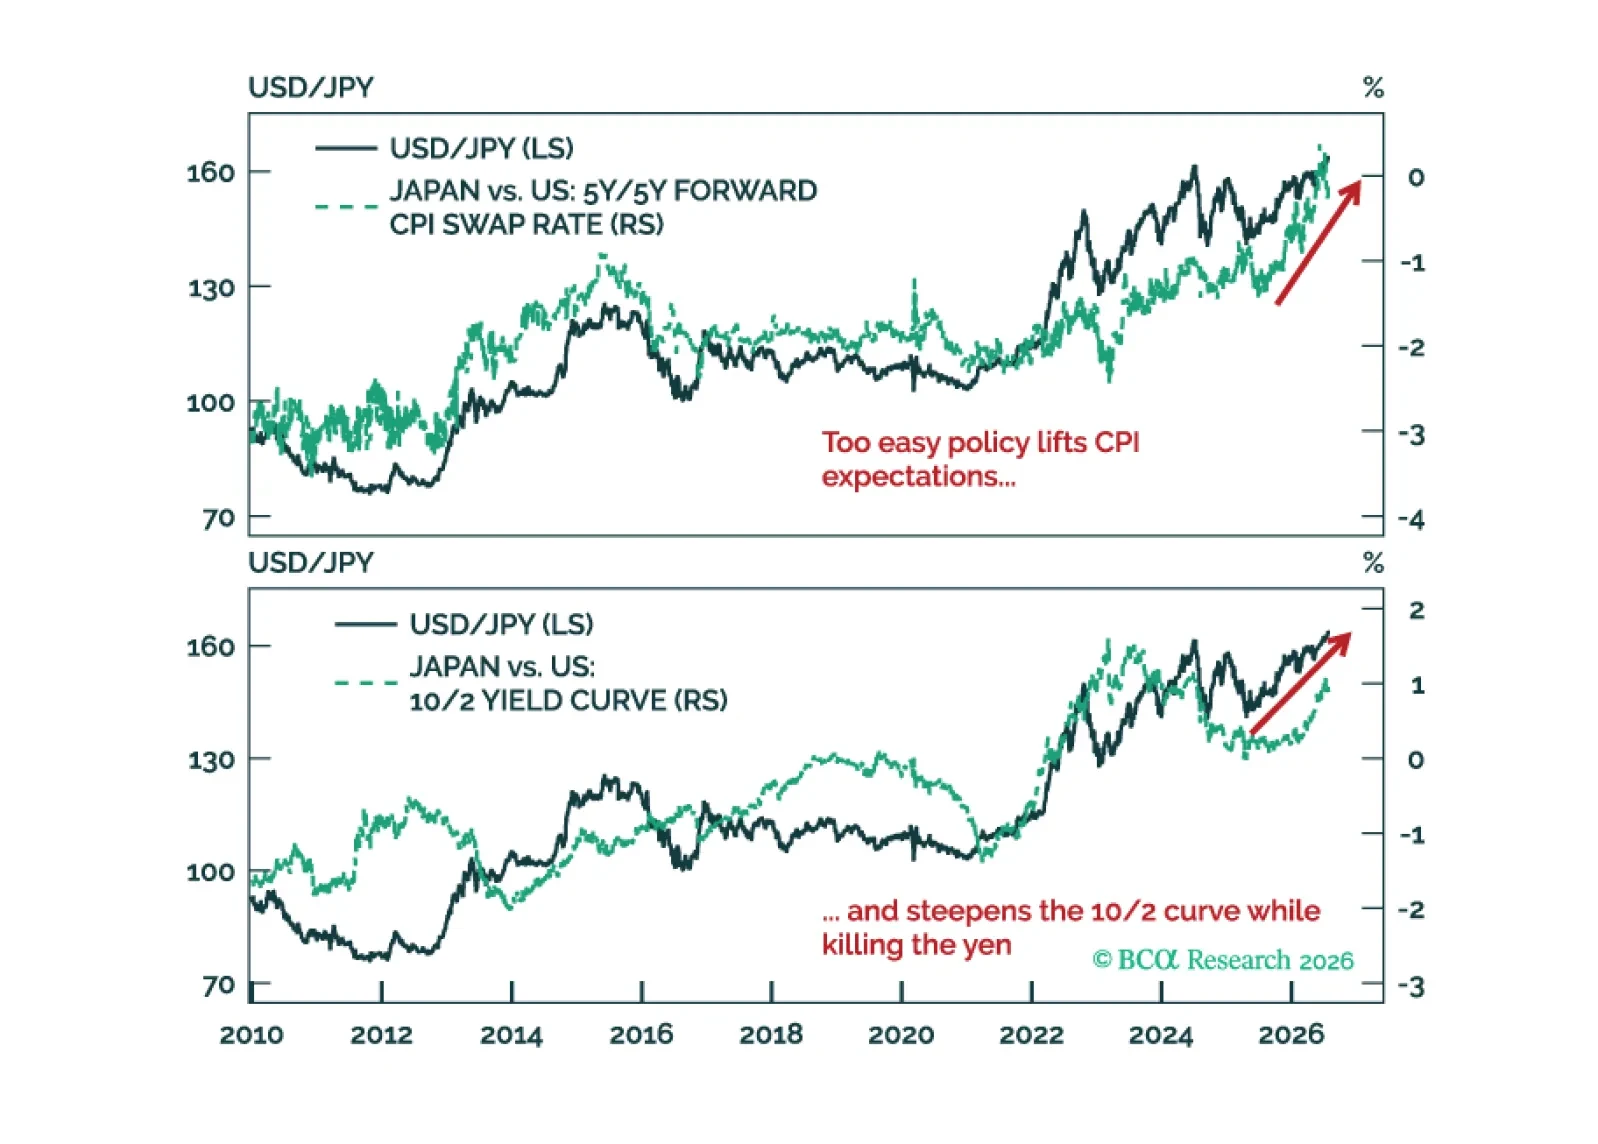
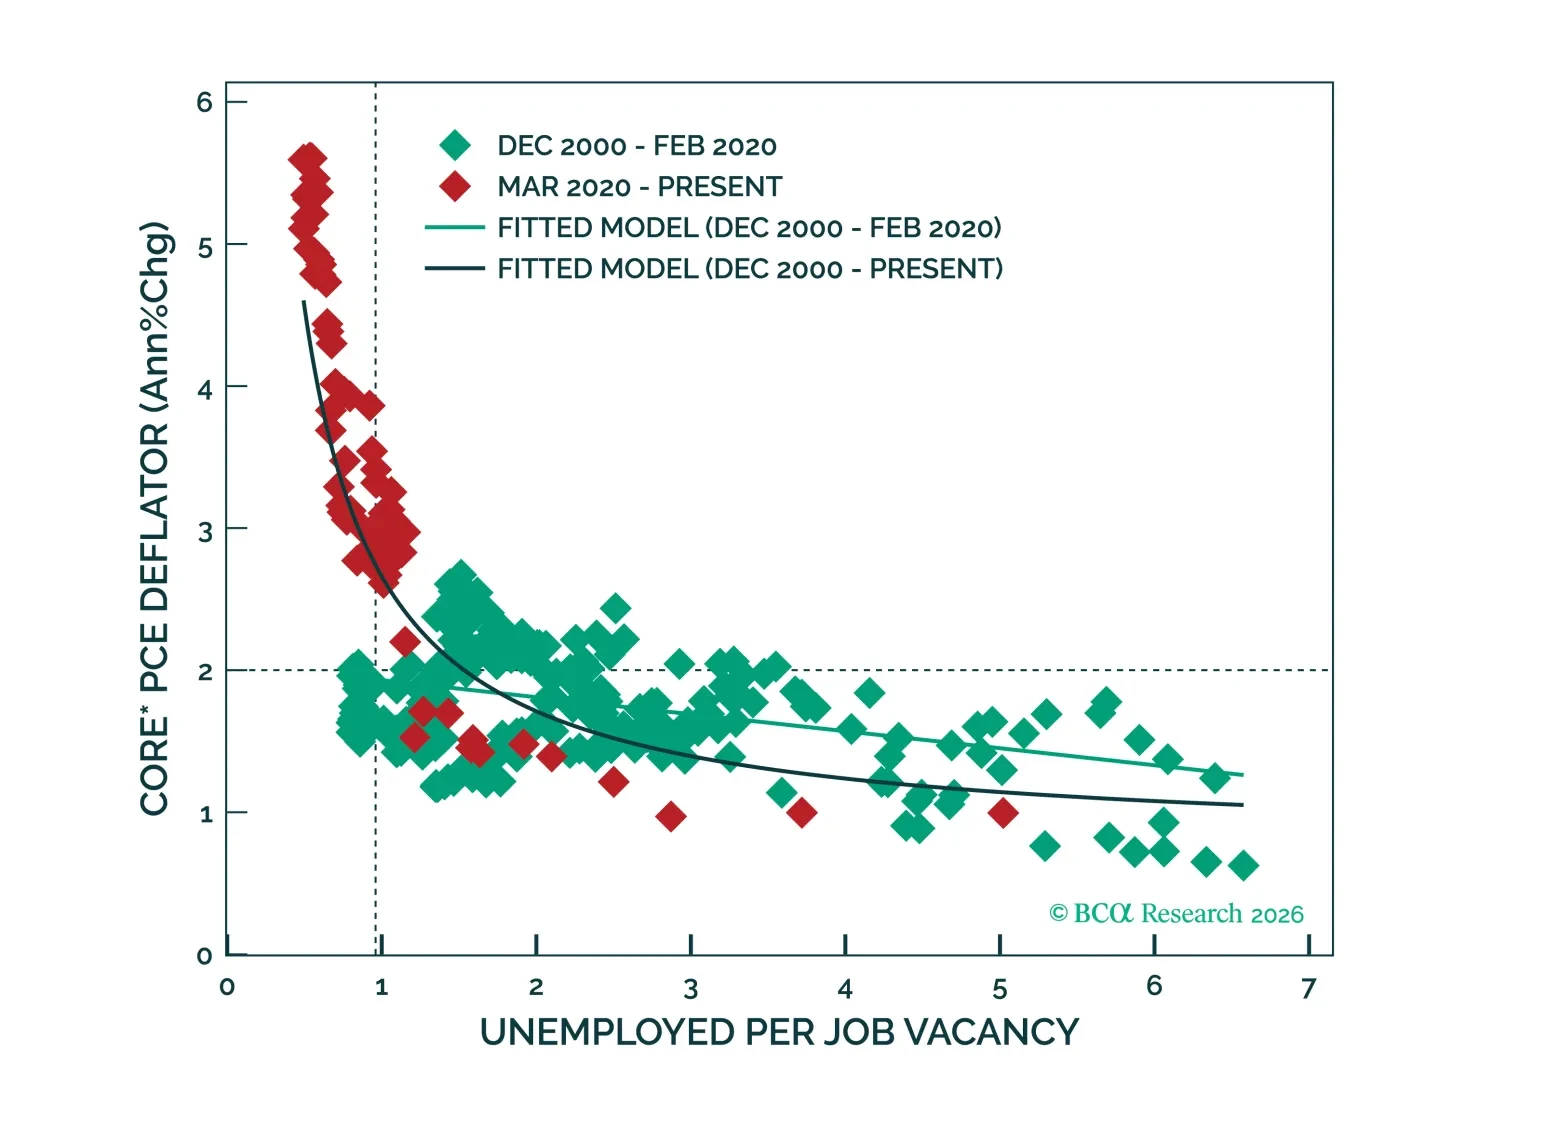
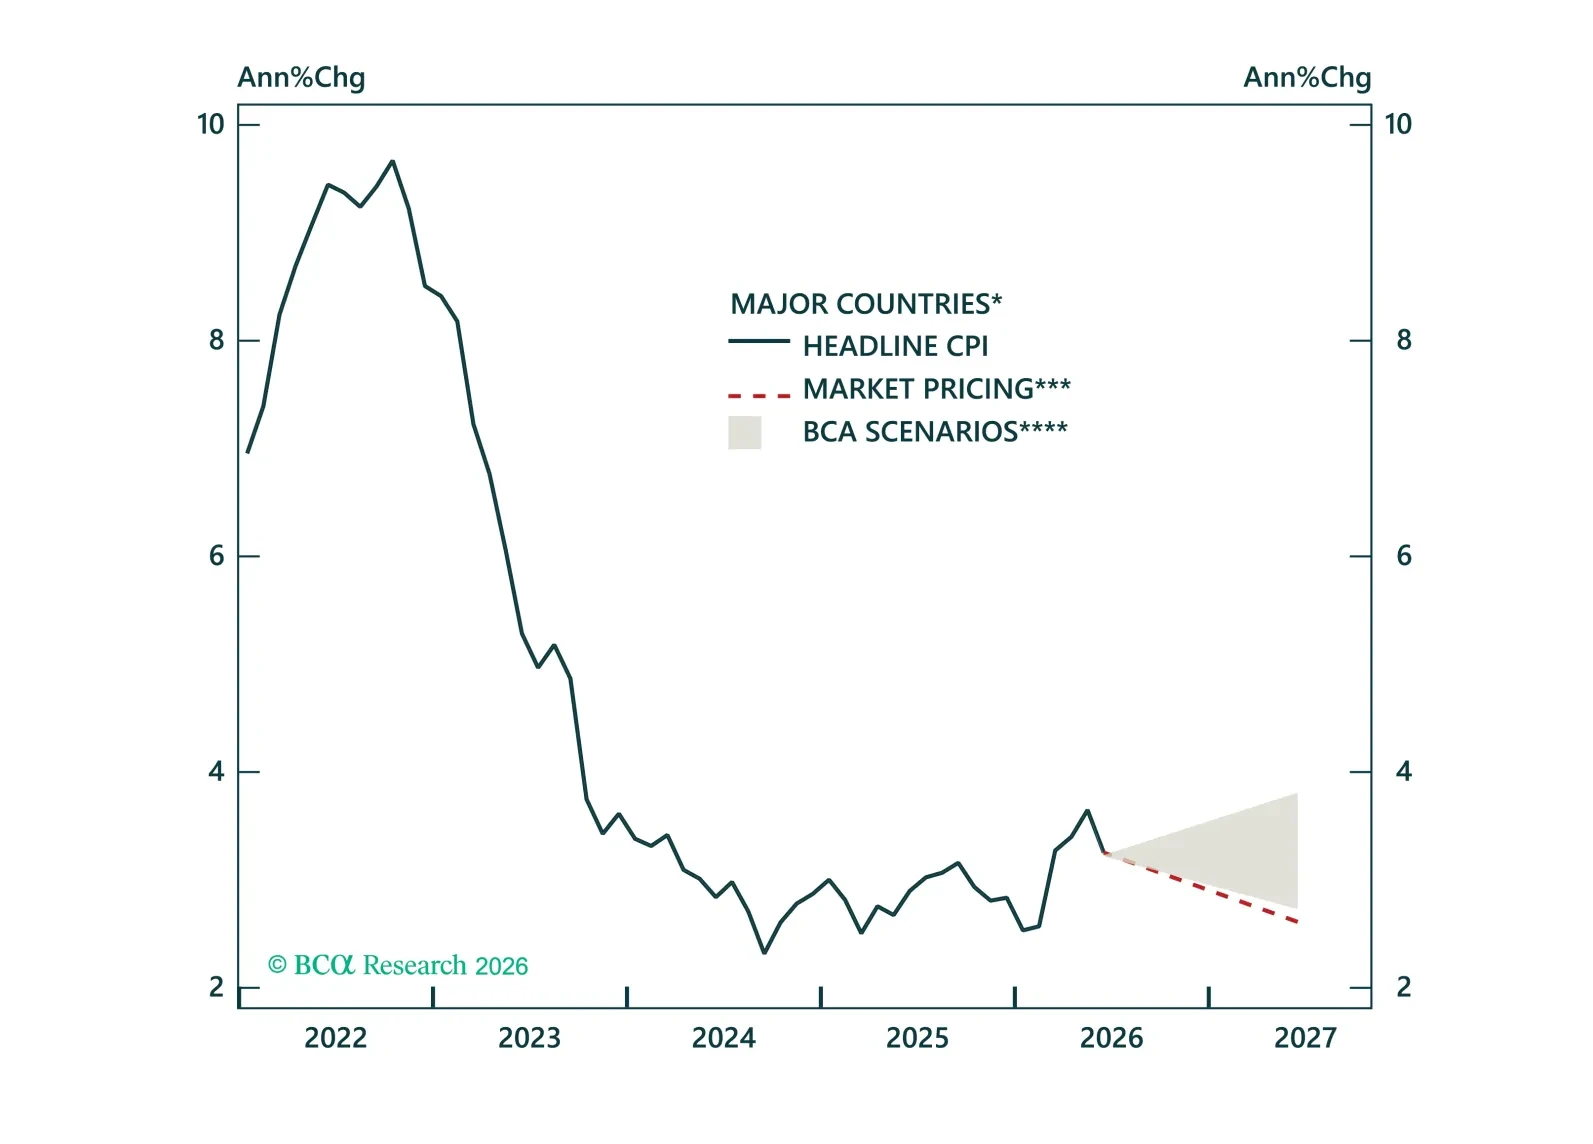
In this Strategy Insight, we assess how Middle East-related energy and shipping disruptions are shaping the global inflation outlook and review the implications for inflation-linked bond markets. We also examine the outlook for core inflation and the resulting implications for central bank policy and duration positioning.