 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
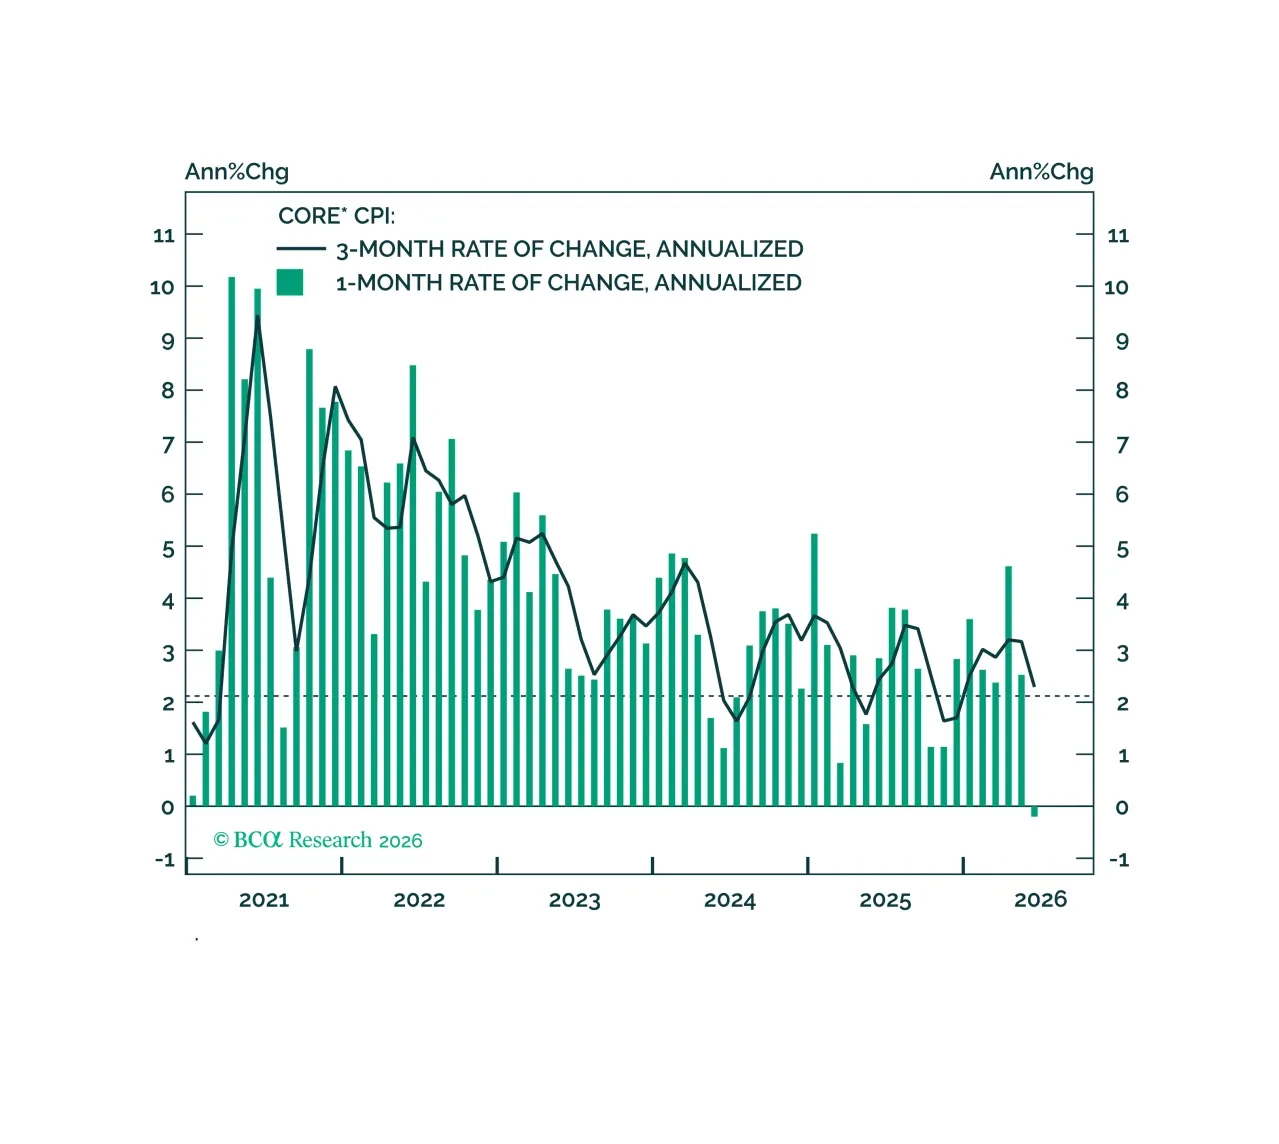
June’s low CPI reading rules out a July rate hike, but September is still on the table.
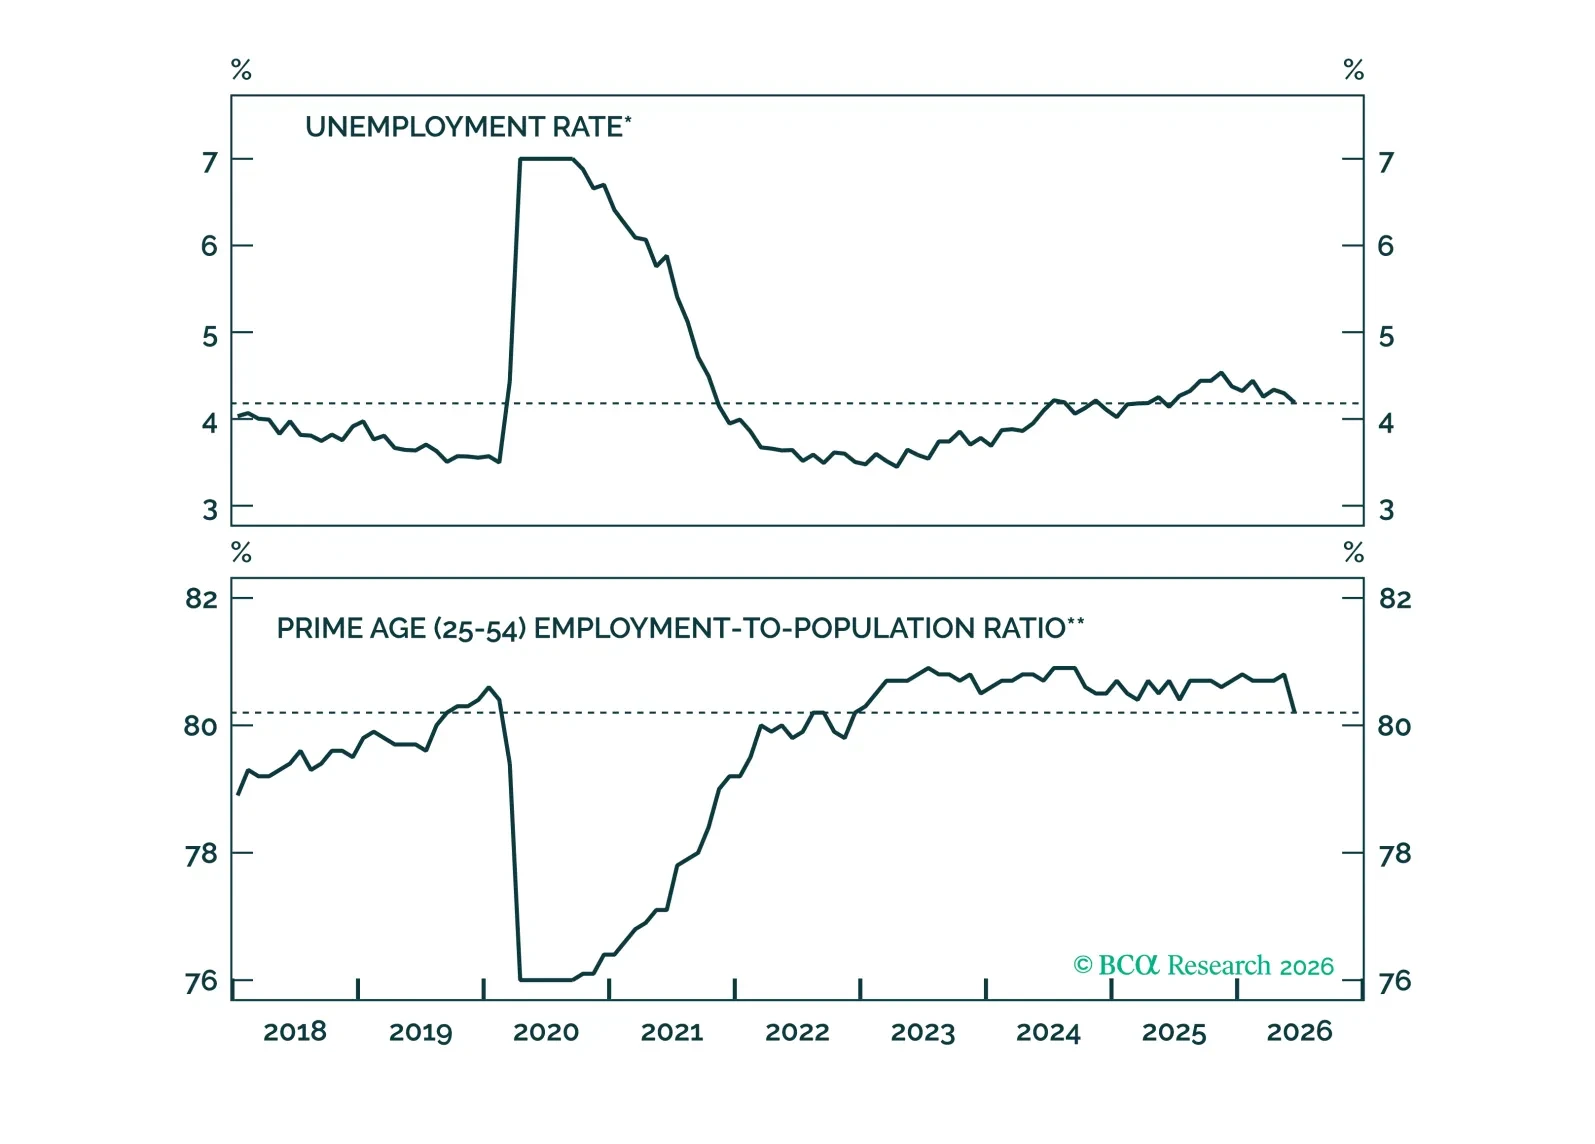
Goldilocks, with fault lines underneath. Our first joint FICC outlook lays out where growth, inflation, and policy are headed this quarter and where the calm could crack.
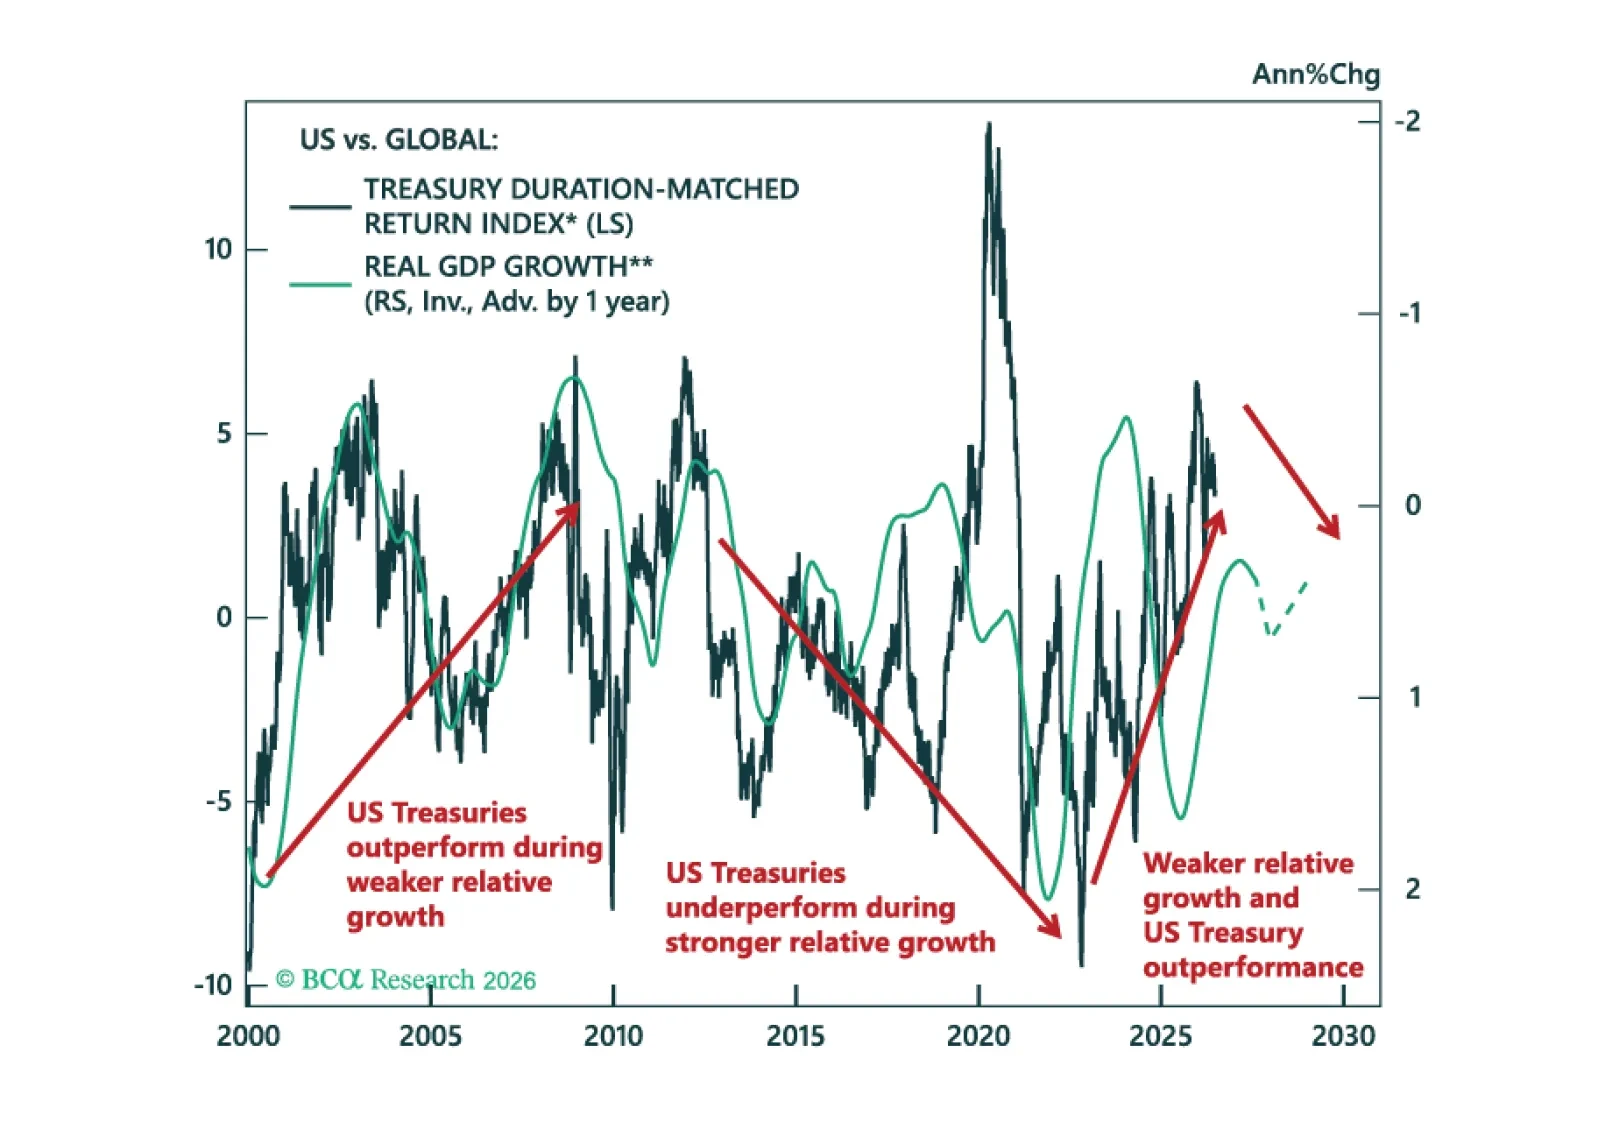
We review our Model Bond Portfolio performance for Q2 and look ahead as fixed income markets move beyond the US-Iran conflict, which is finding its kinetic equilibrium. Valuations and growth differentials are moving against continued US Treasury outperformance.
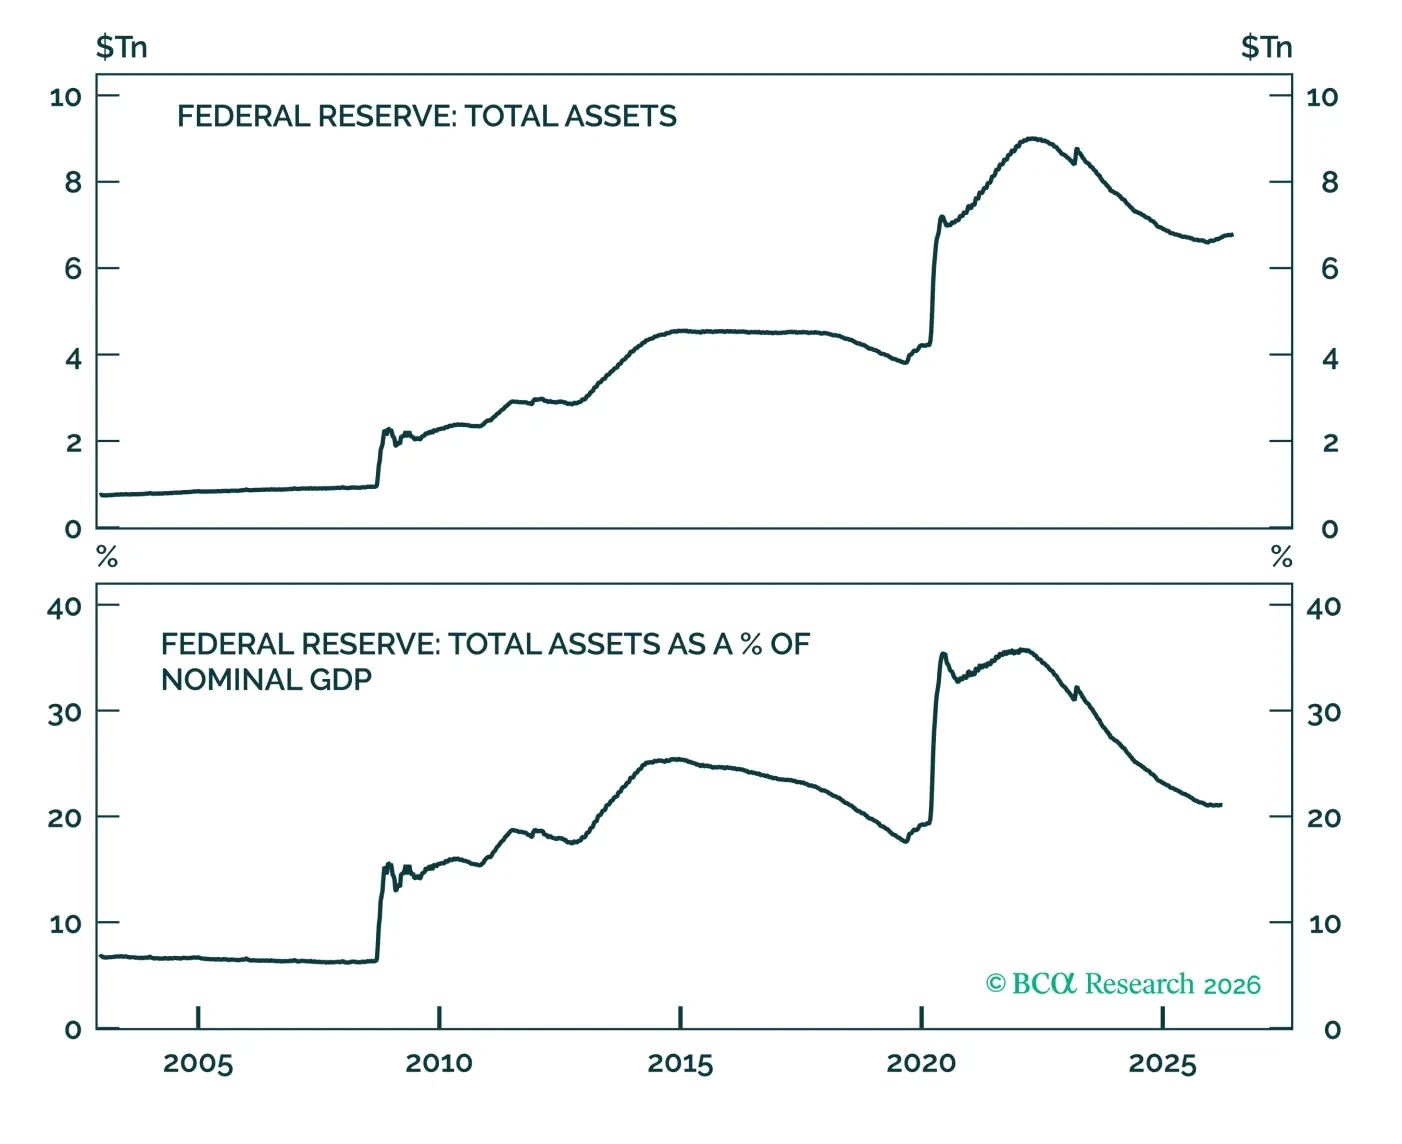
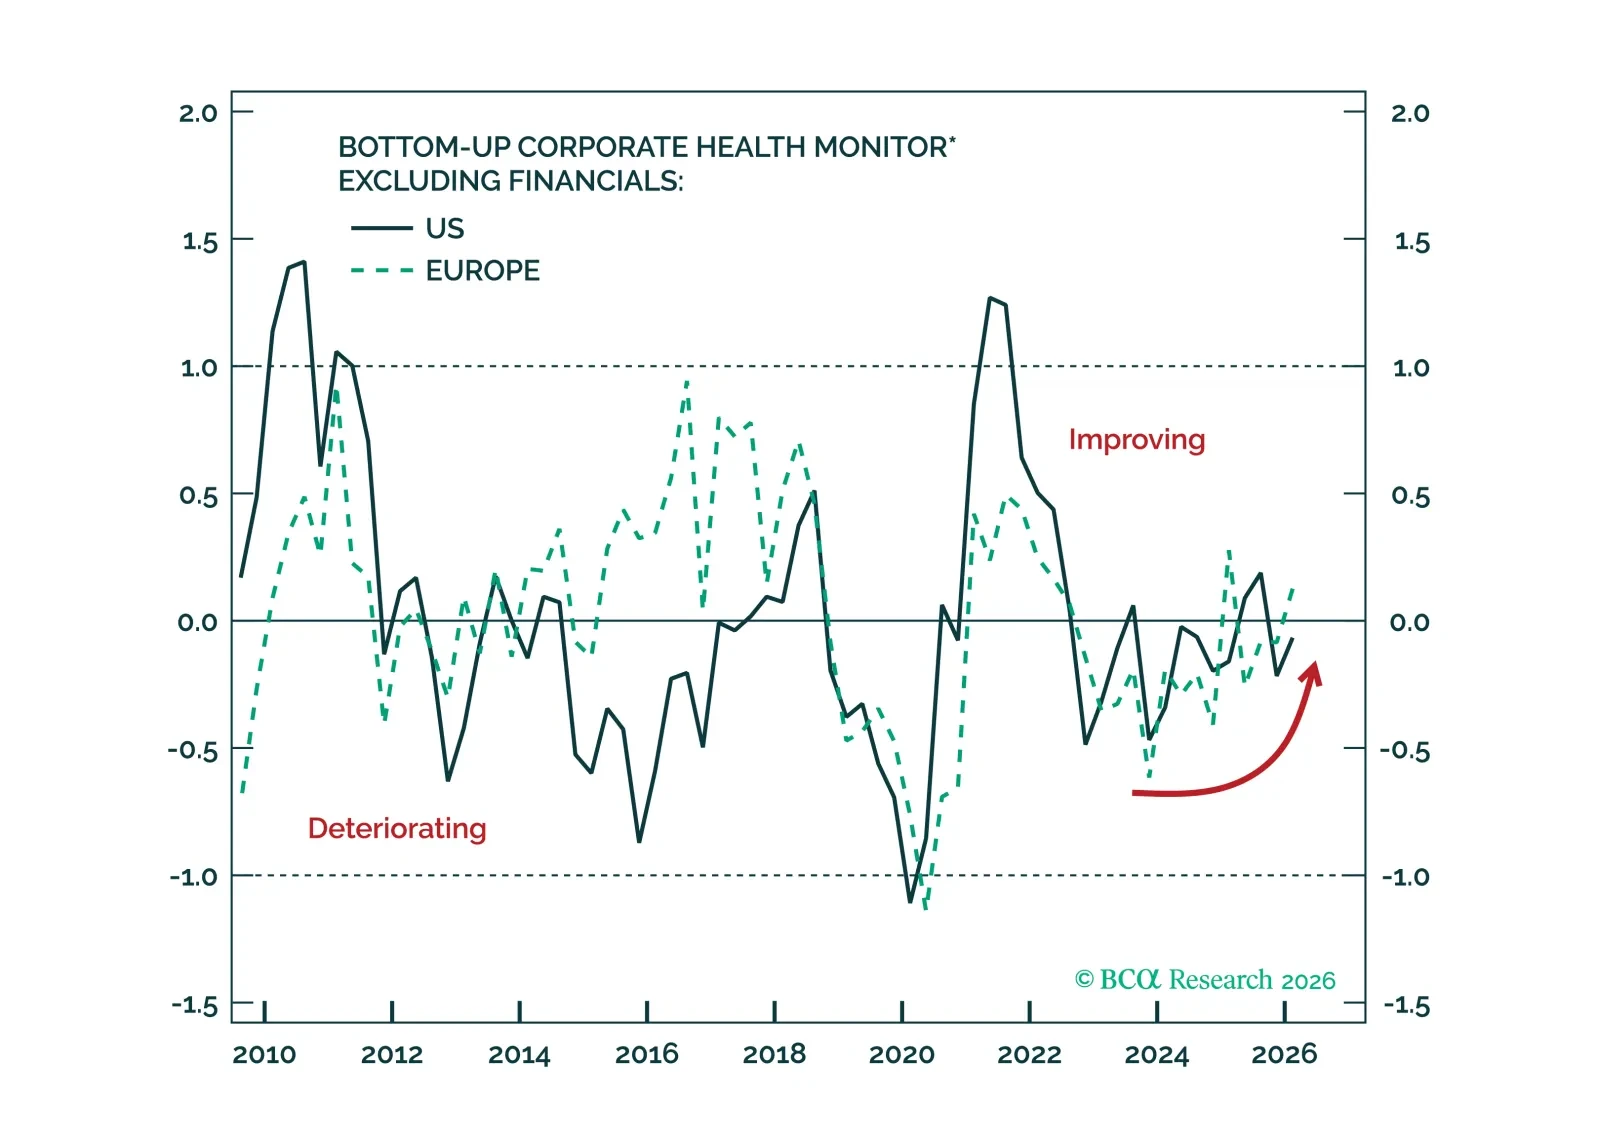
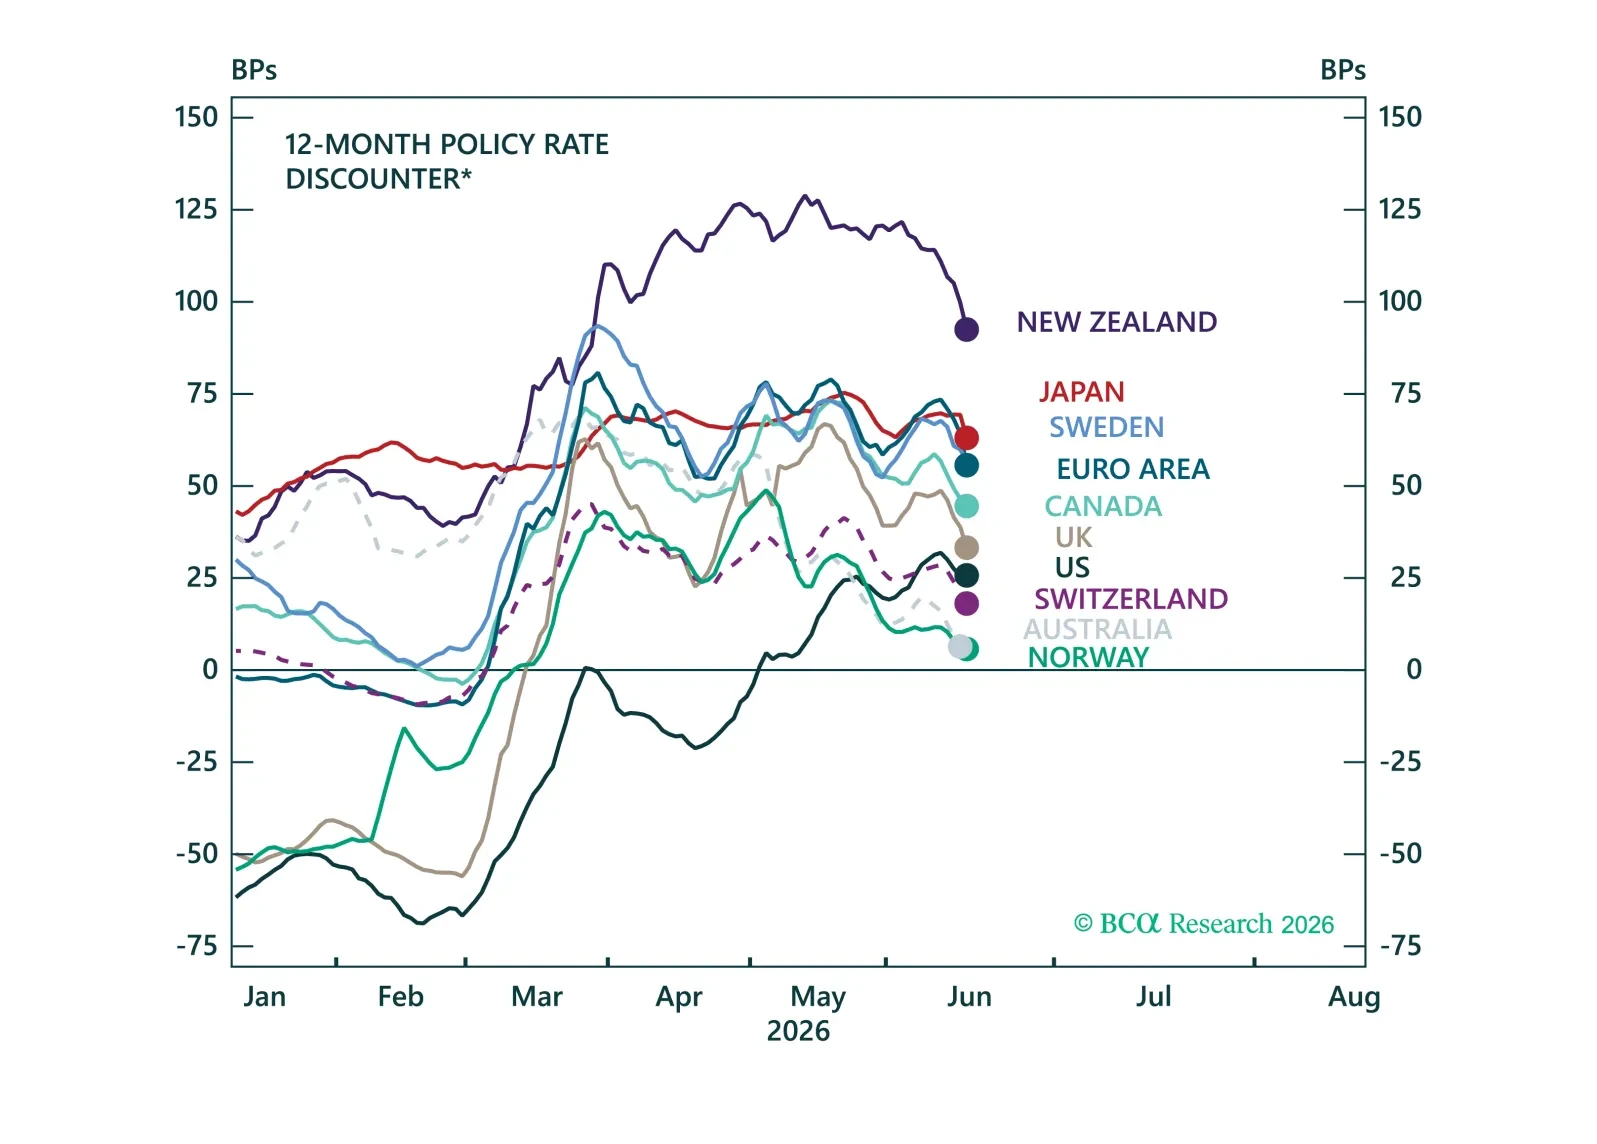
We react to DM central bank meetings this week and highlight the opportunities emerging across global fixed income and currency markets.
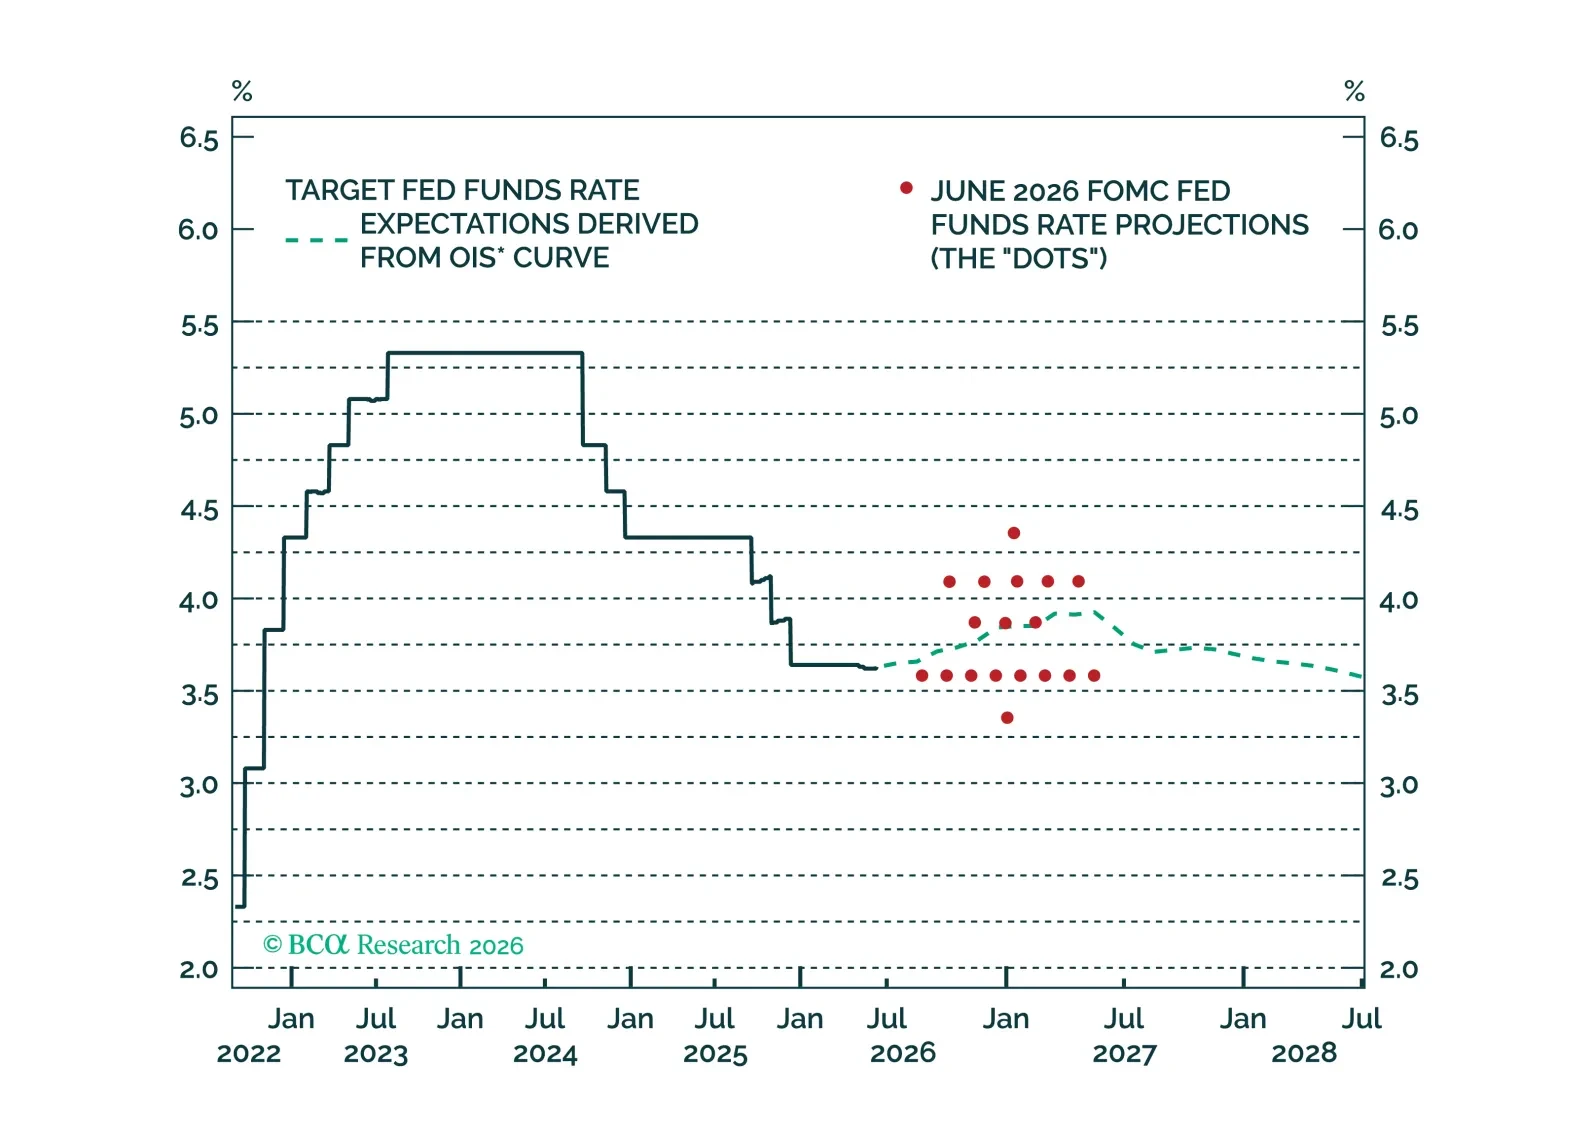
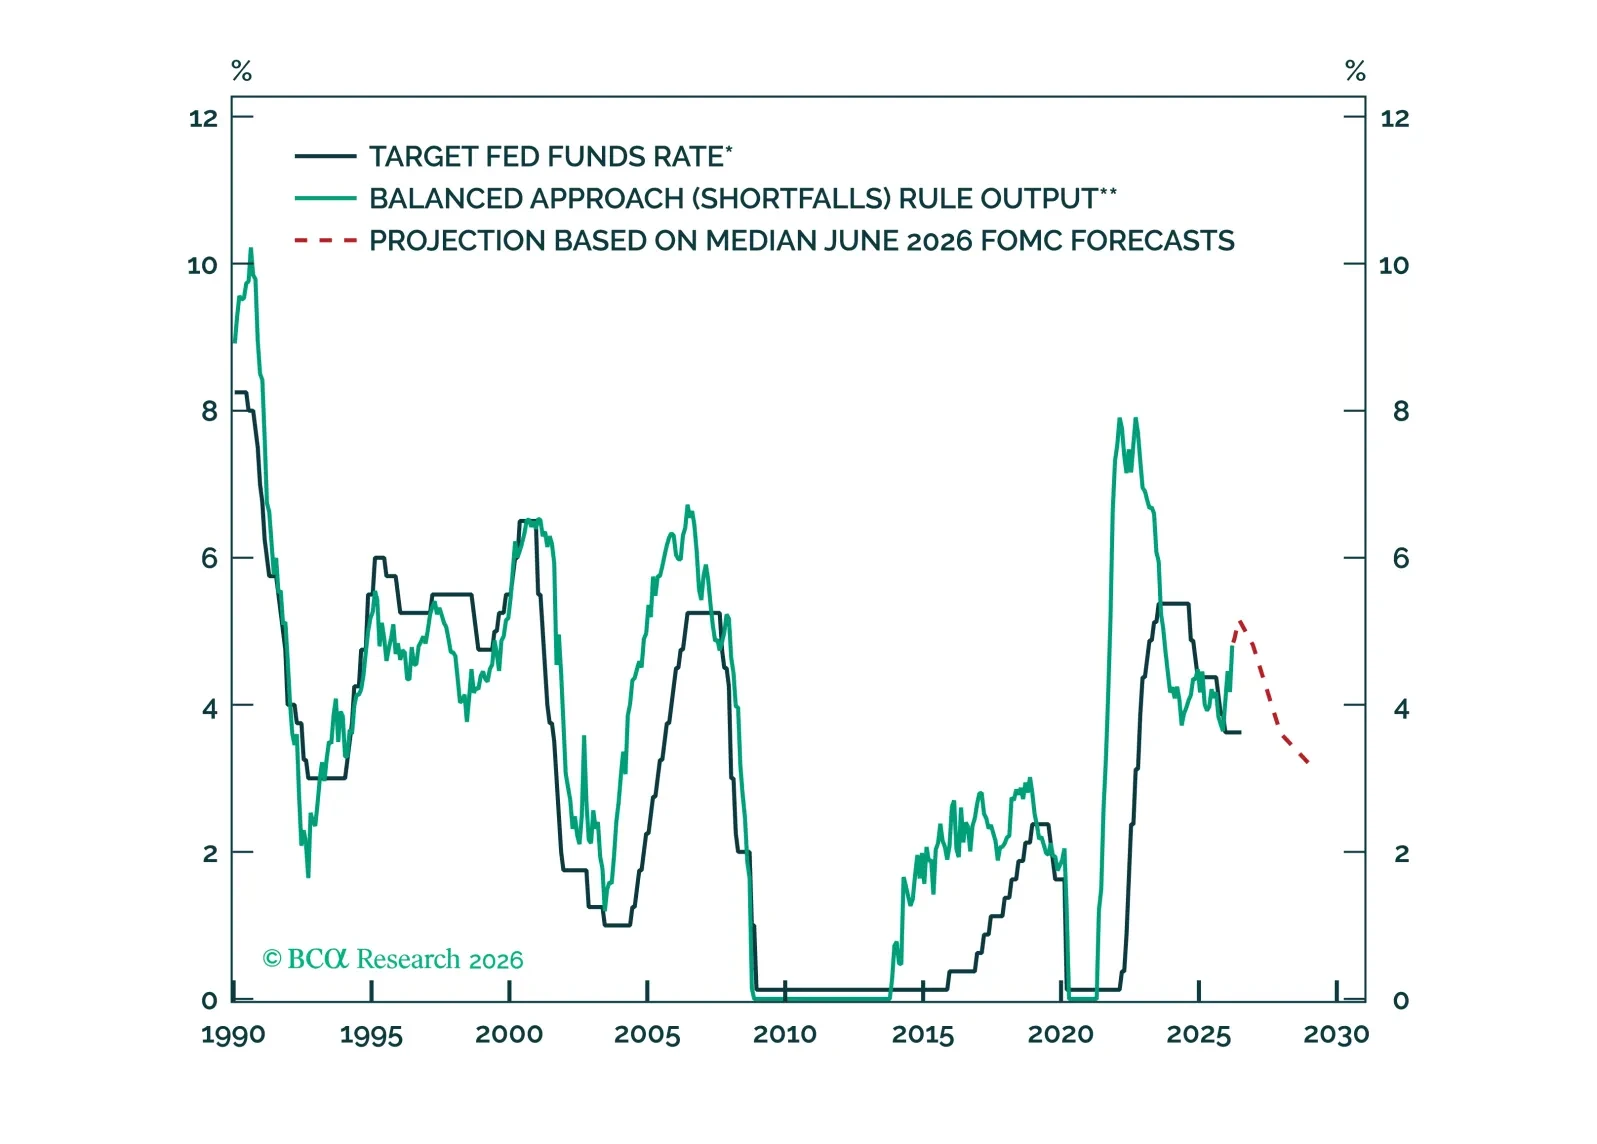
Kevin Warsh announced an ambitious reform agenda for the Federal Reserve. We discuss the potential impact and the current outlook for interest rates.
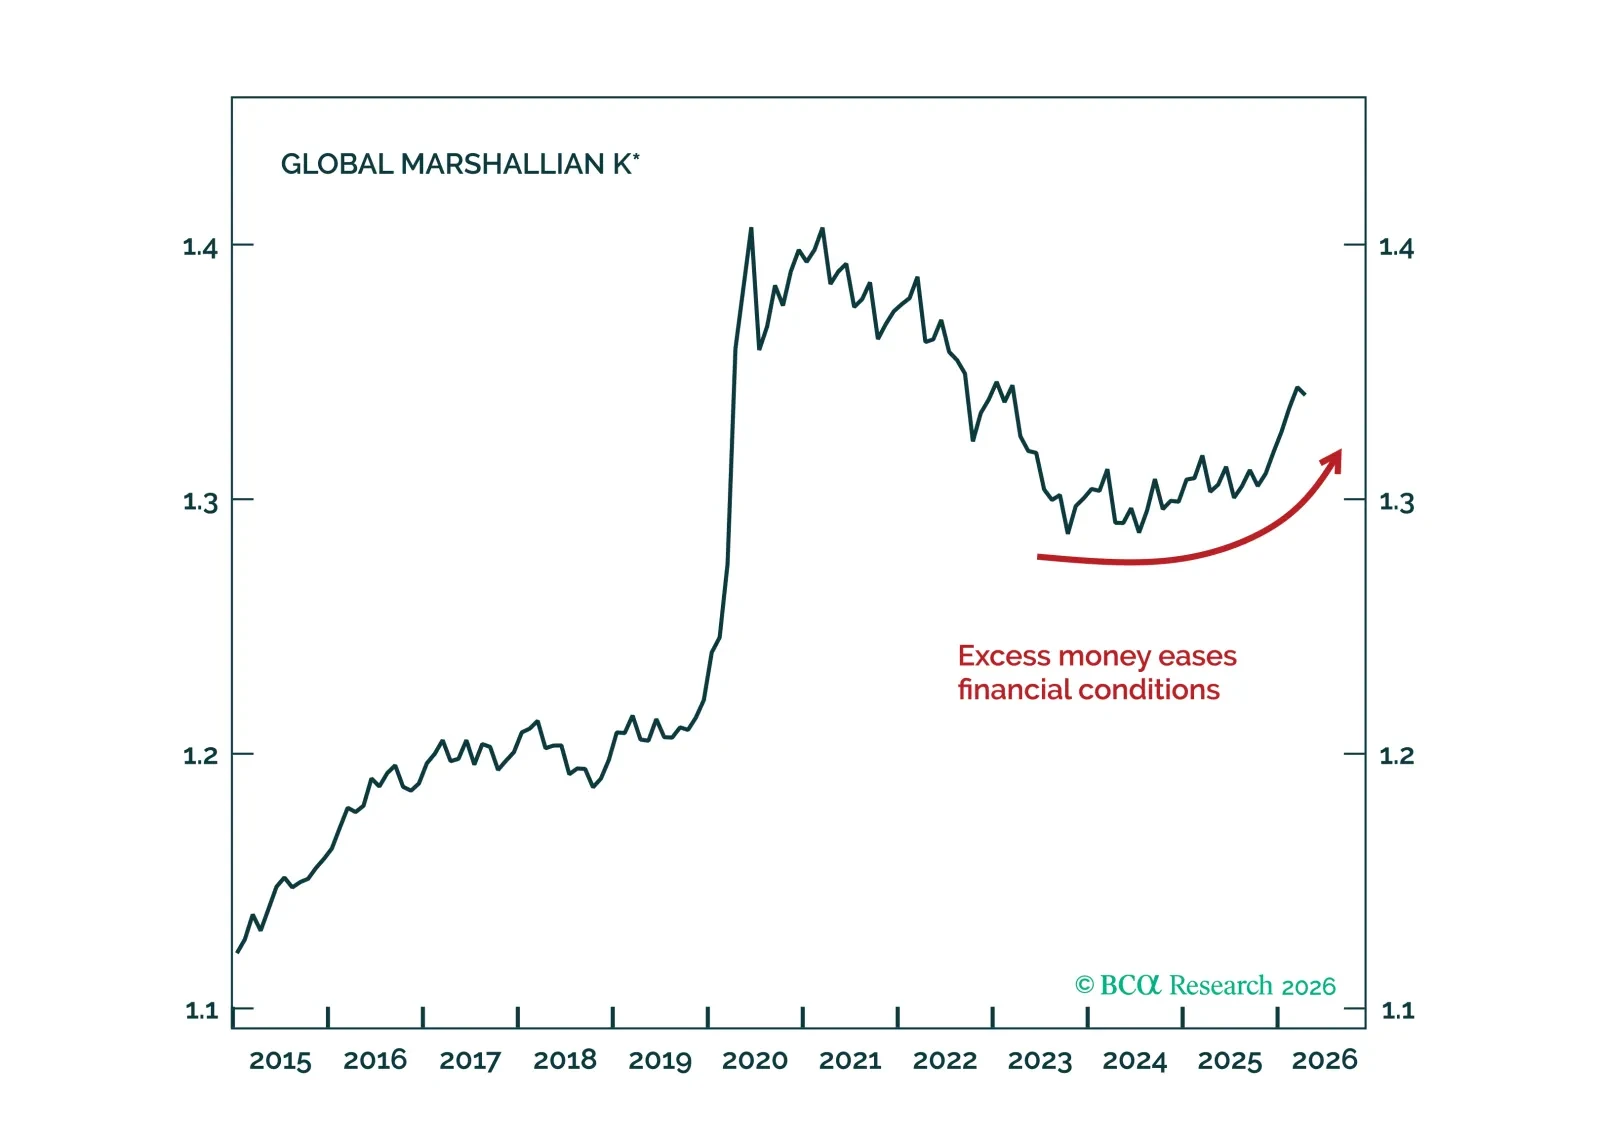
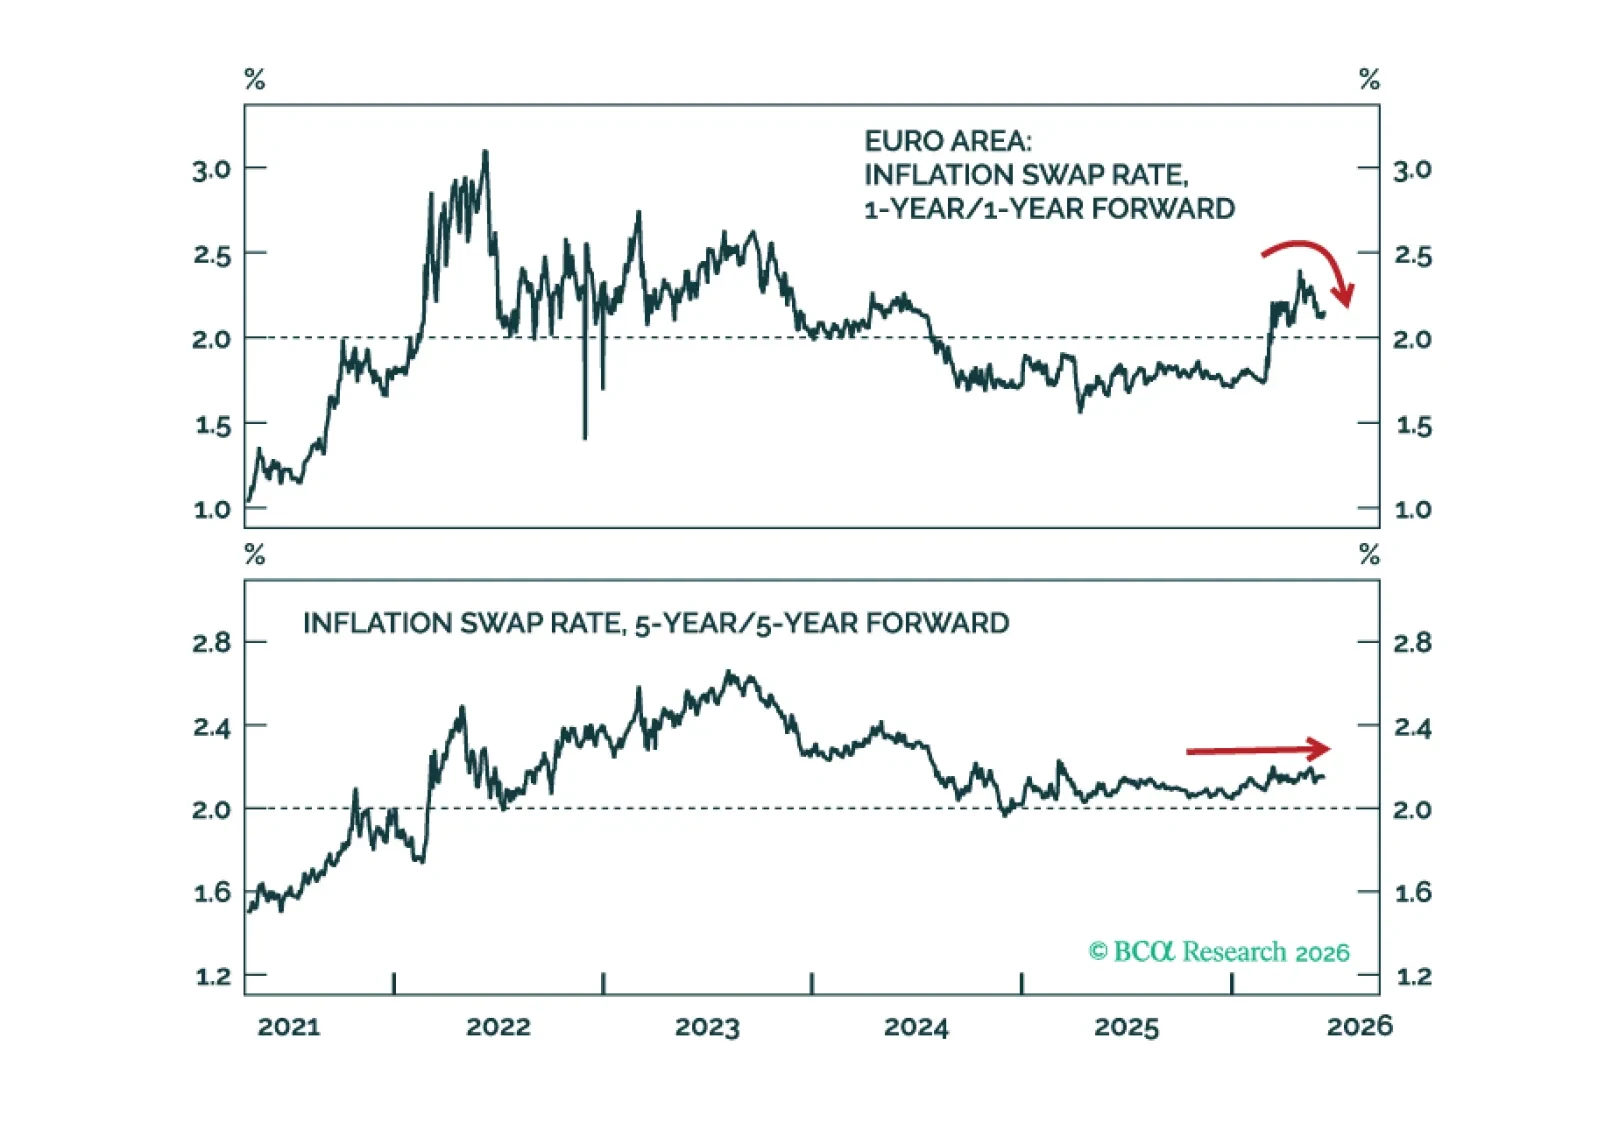
Today’s ECB rate hike is not the beginning of a hiking cycle. Growth concerns will soon move to the forefront of ECB policy decisions, preventing further tightening.