 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
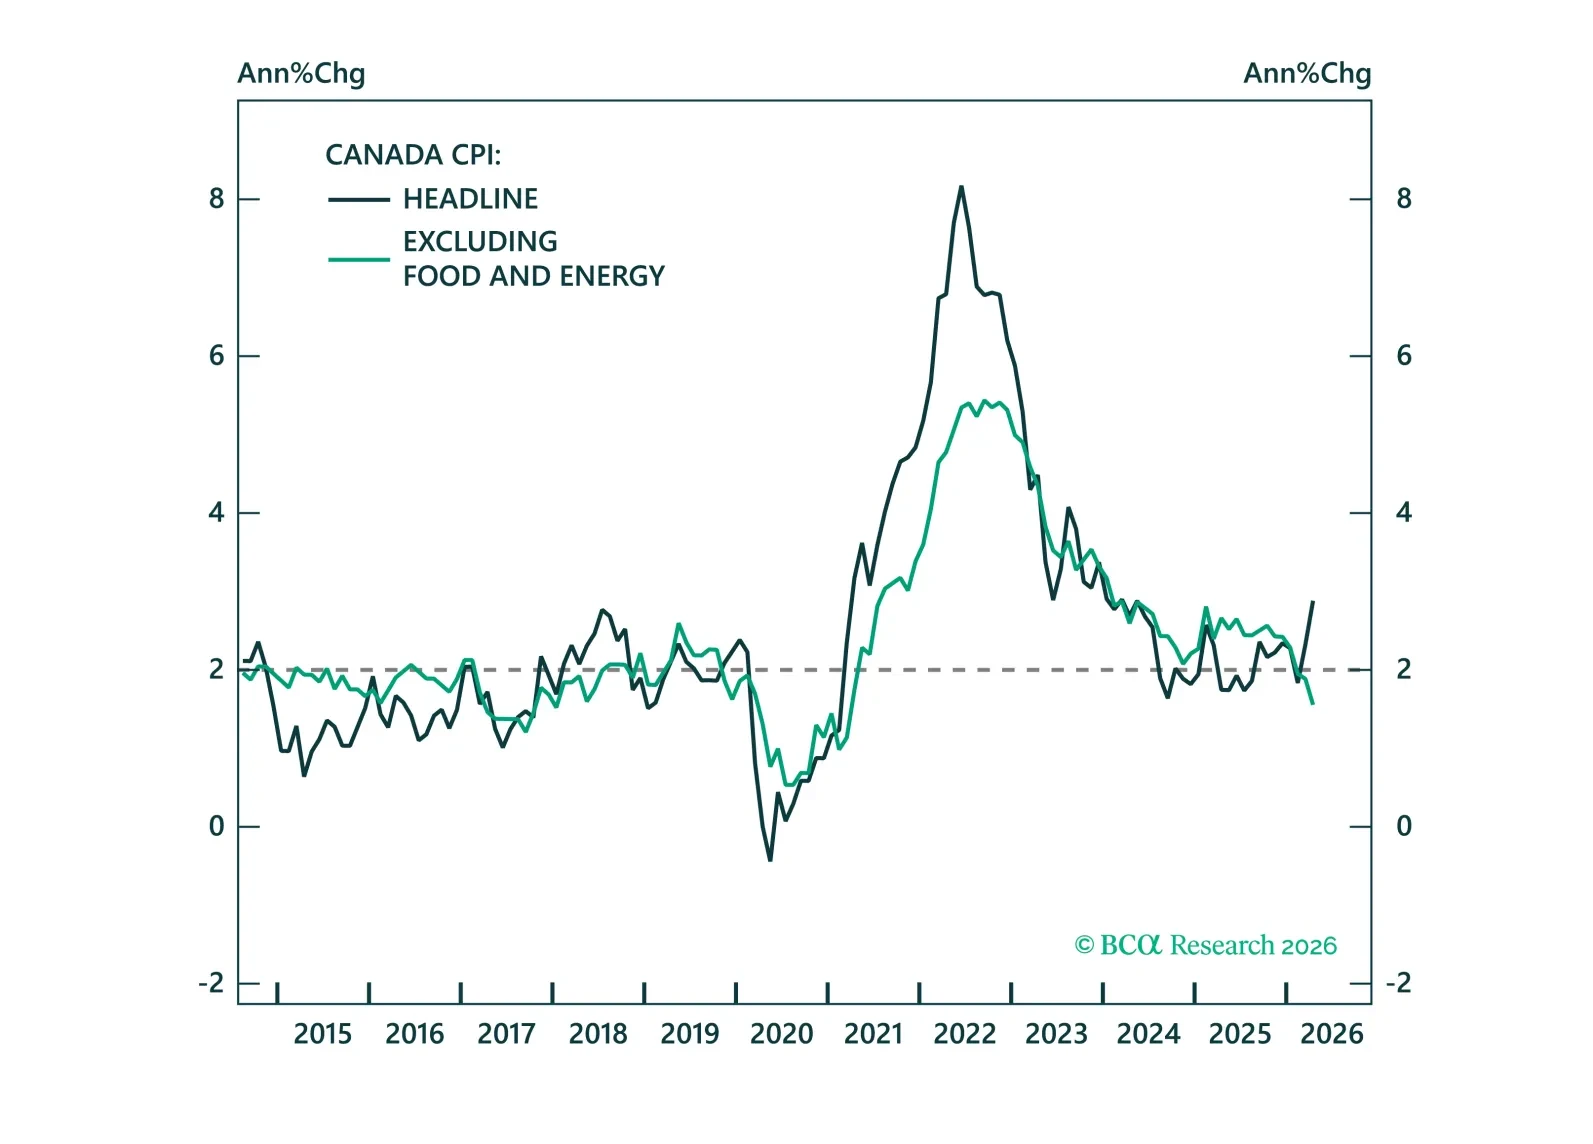
The Bank of Canada left rates unchanged and emphasized inflation risks from higher oil prices. We discuss why inflation and labor market data argue against the tightening currently priced.
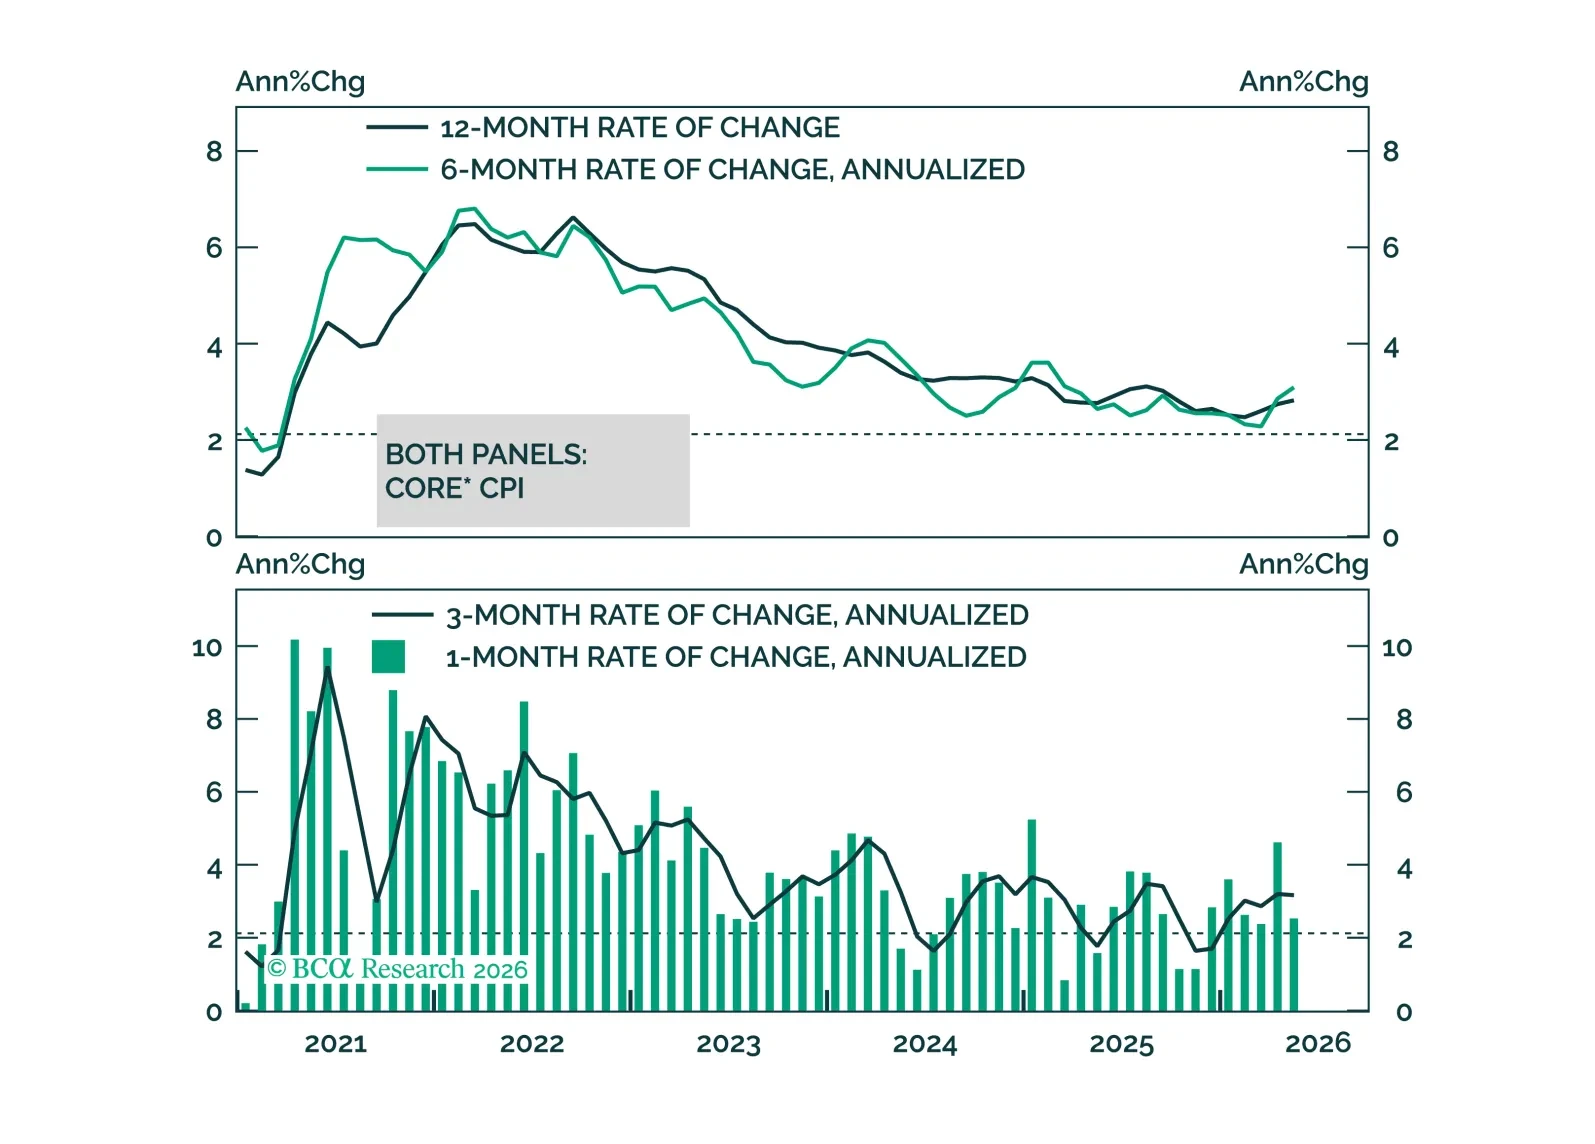
May CPI data show no evidence of passthrough from energy prices to core inflation. This will keep the Fed on hold for the time being.
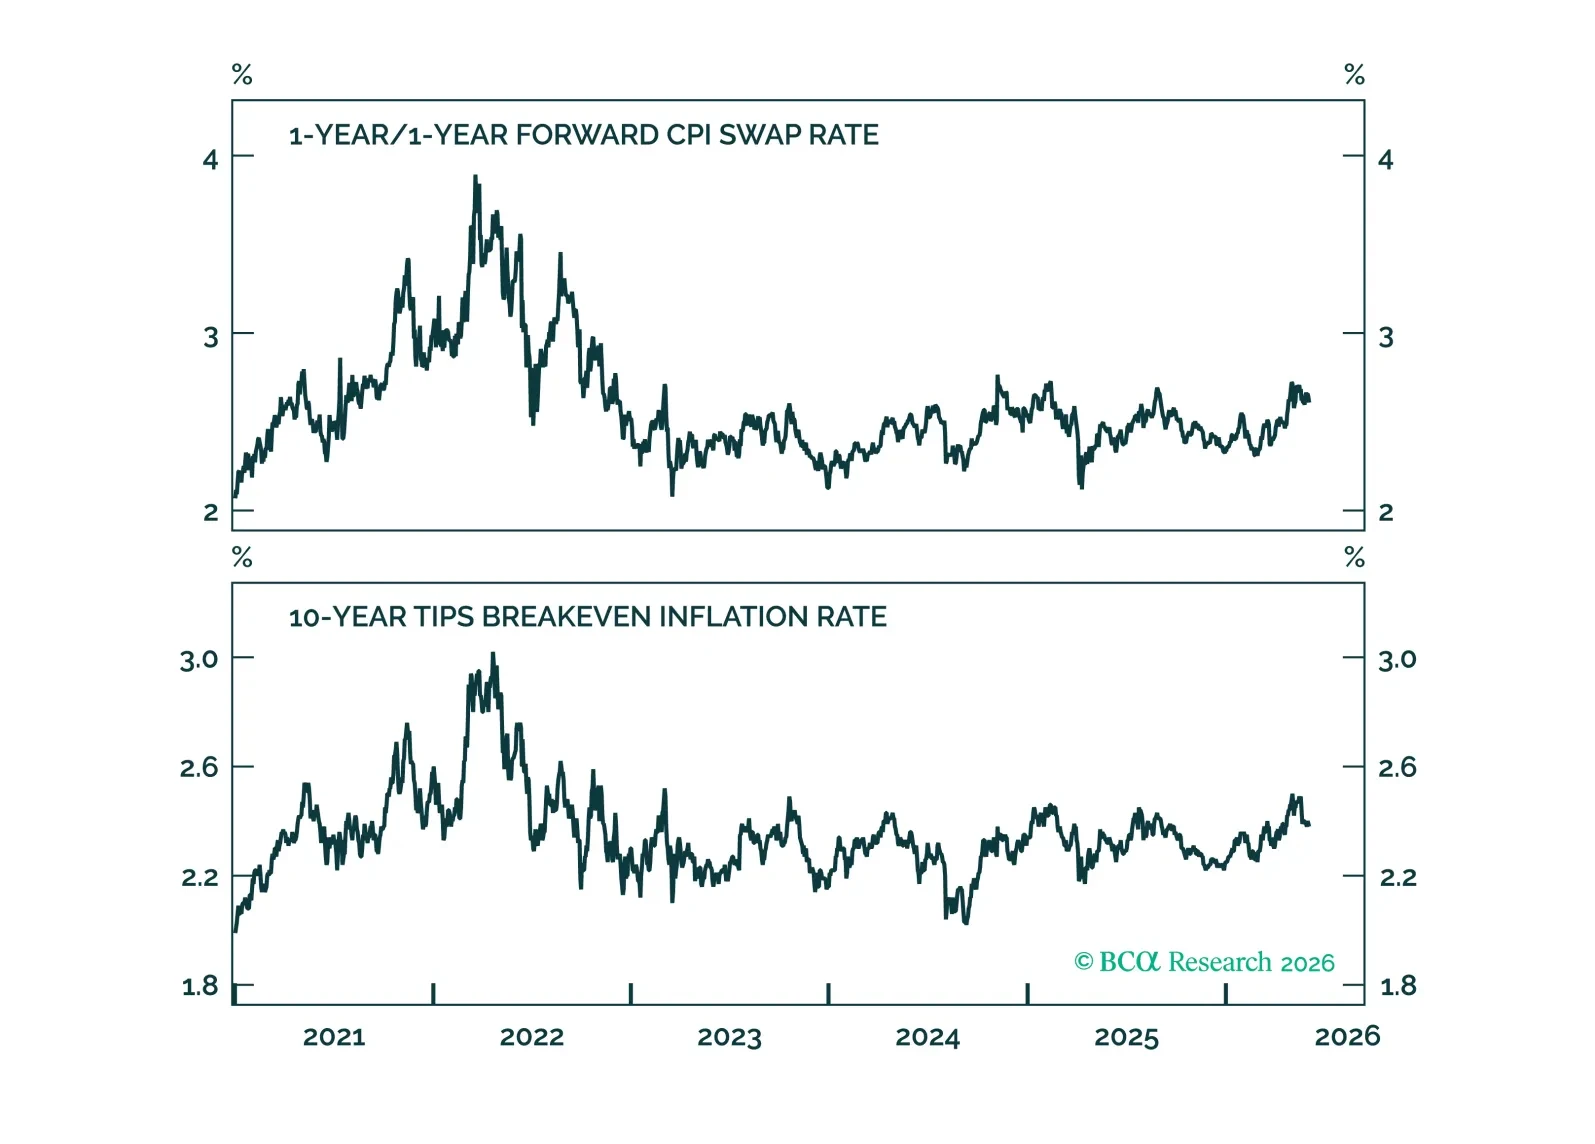
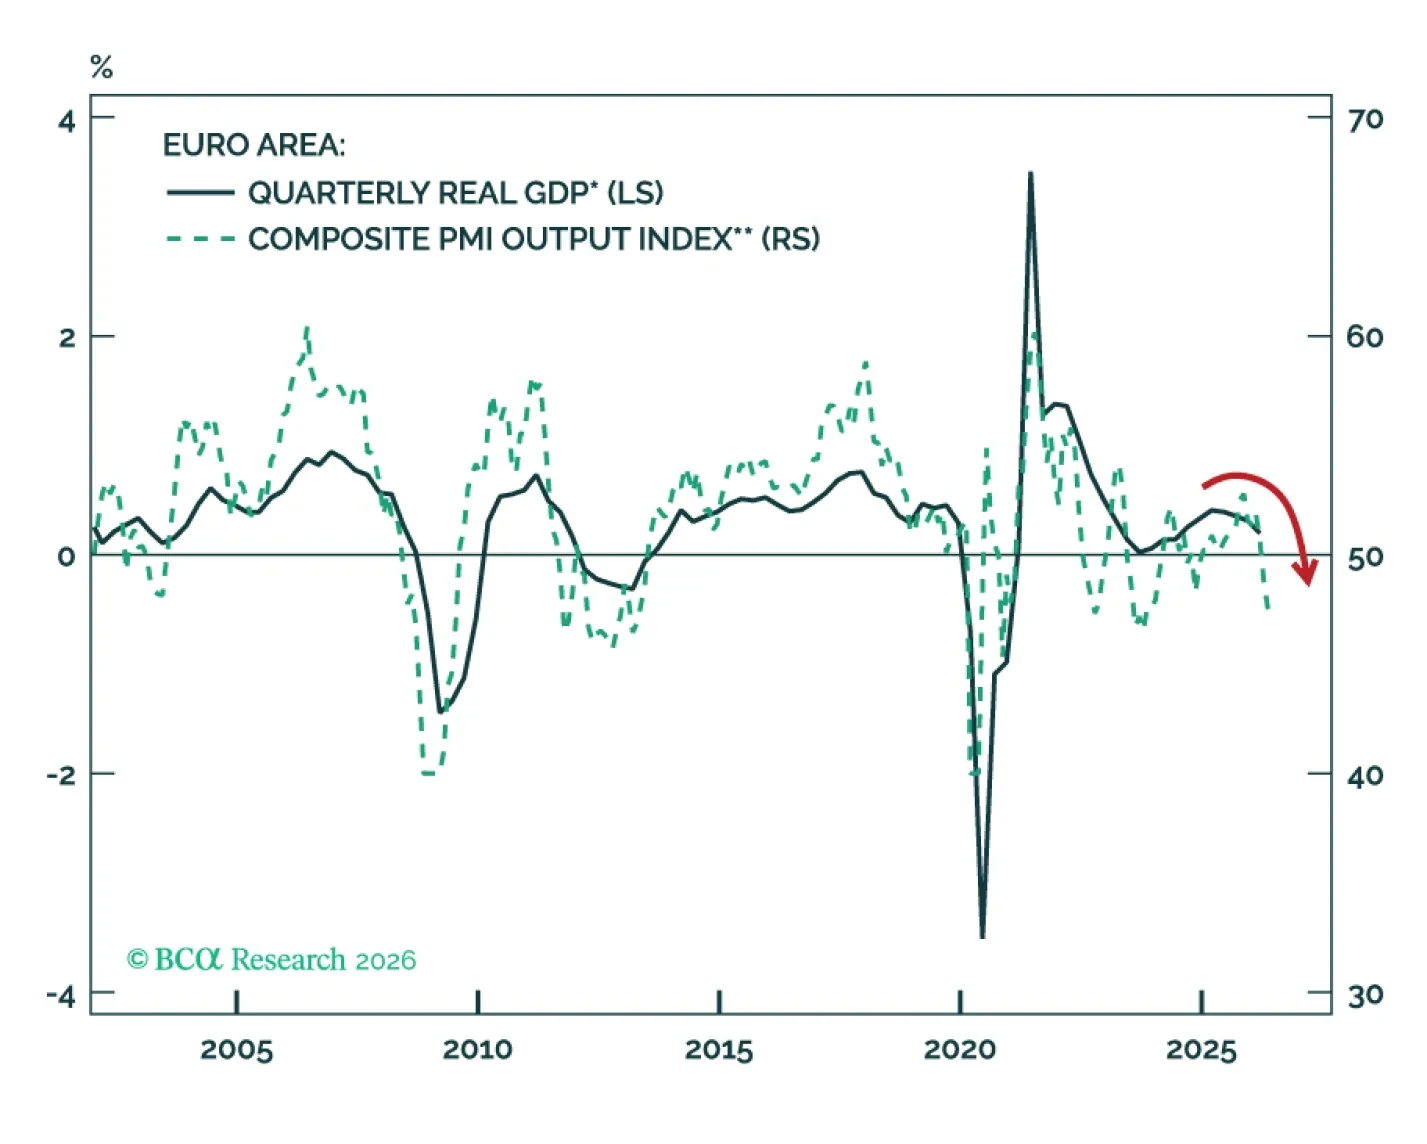
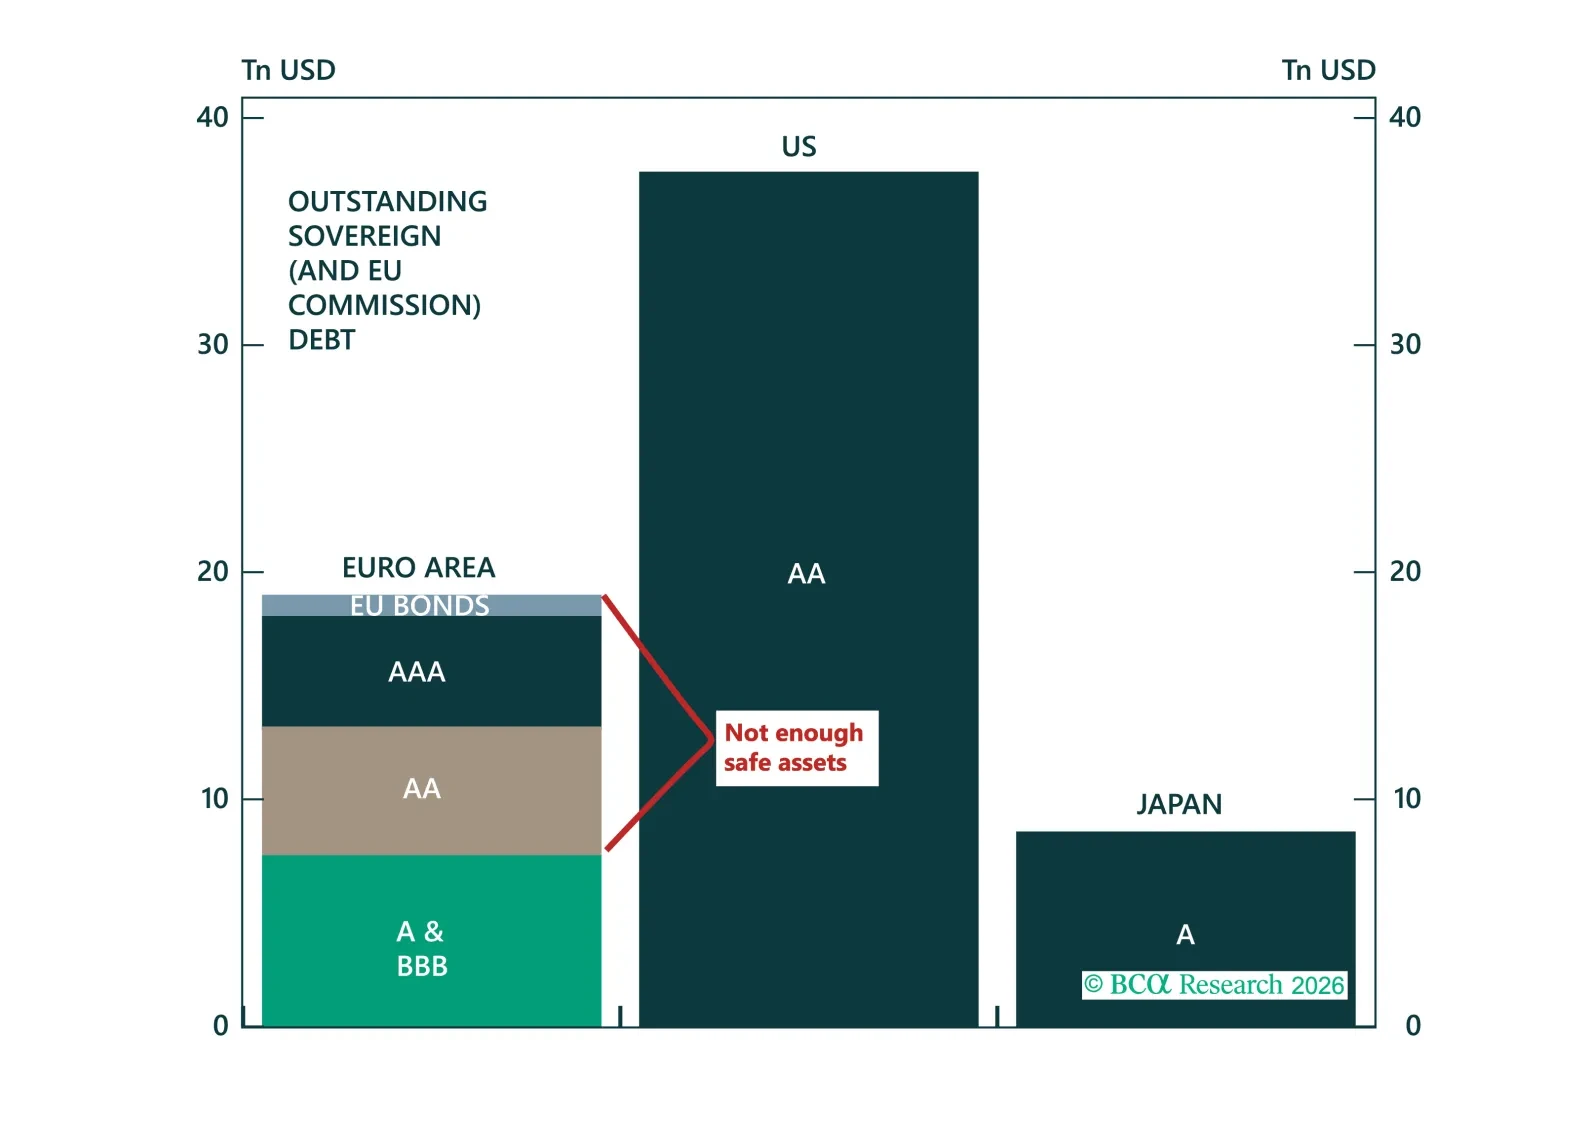
Europe is sliding from stagflation toward recession as prolonged disruptions in the Strait of Hormuz weaken growth, labor markets, and supply chains while keeping inflation elevated. Even if a US-Iran deal is reached, limited fiscal support and rising food inflation leave the Euro Area increasingly vulnerable to a deeper economic downturn.
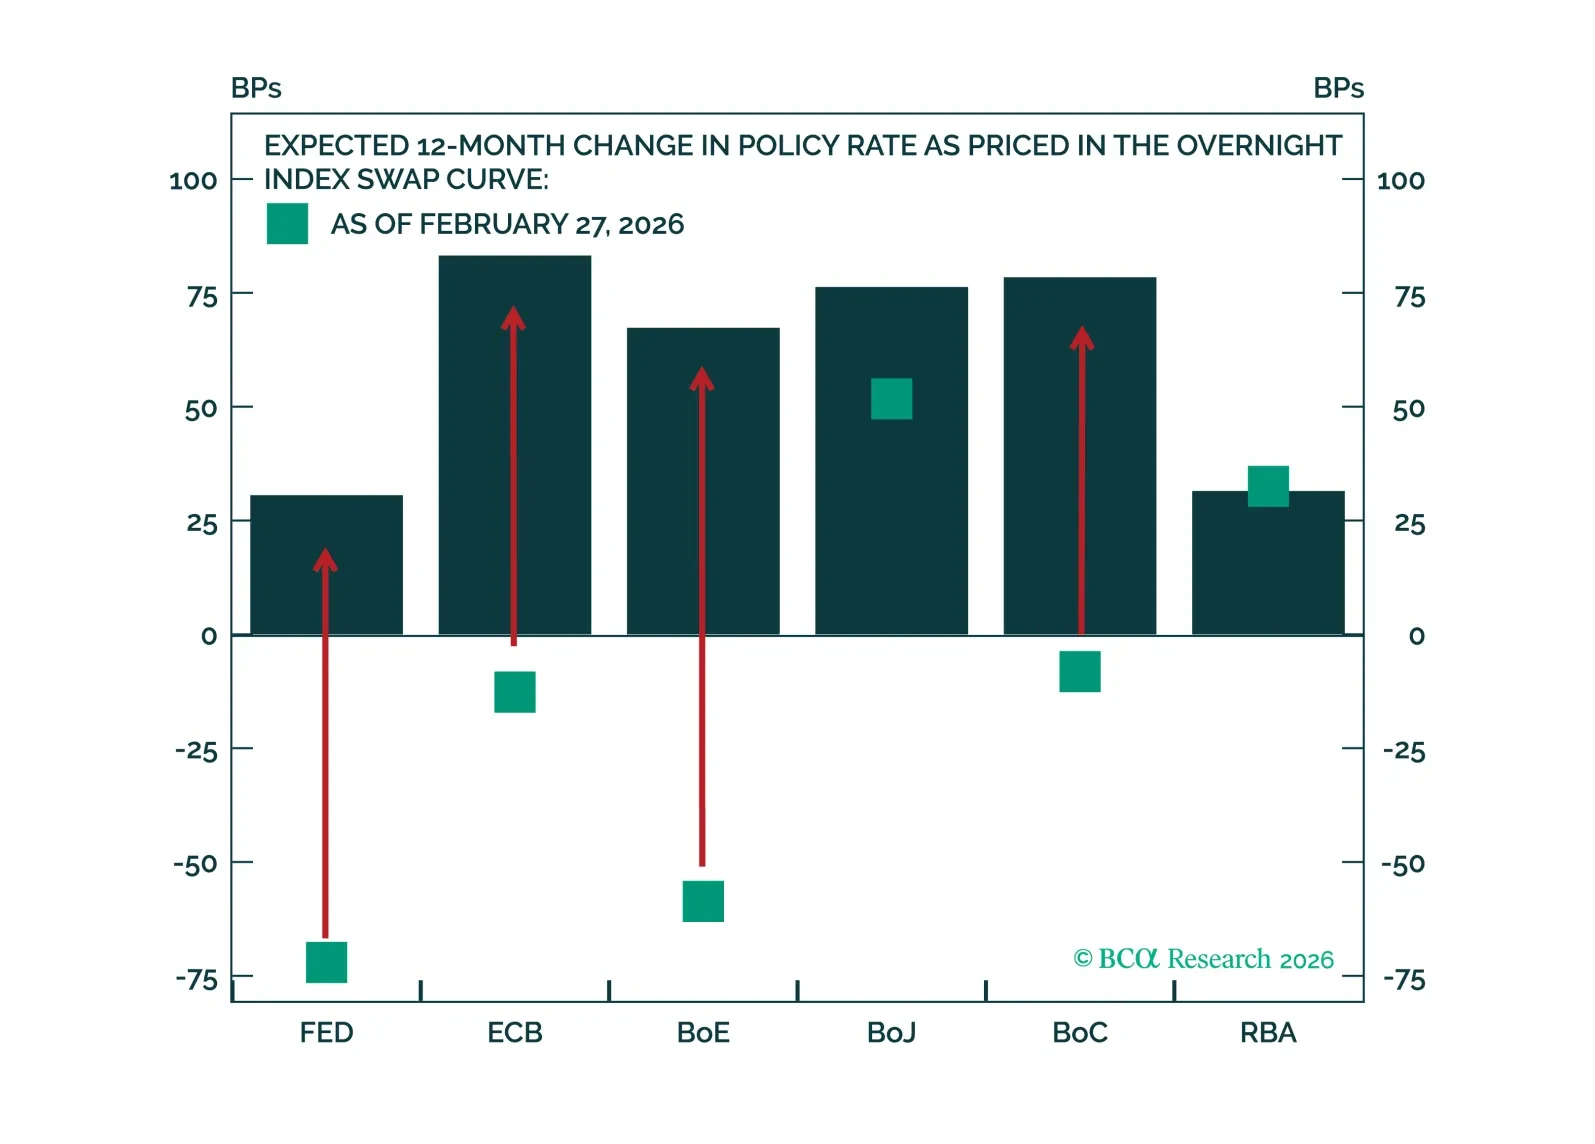
Downgrade global and US portfolio duration from “above benchmark” to “at benchmark” as the risk of hawkish monetary policy surprises is rising.
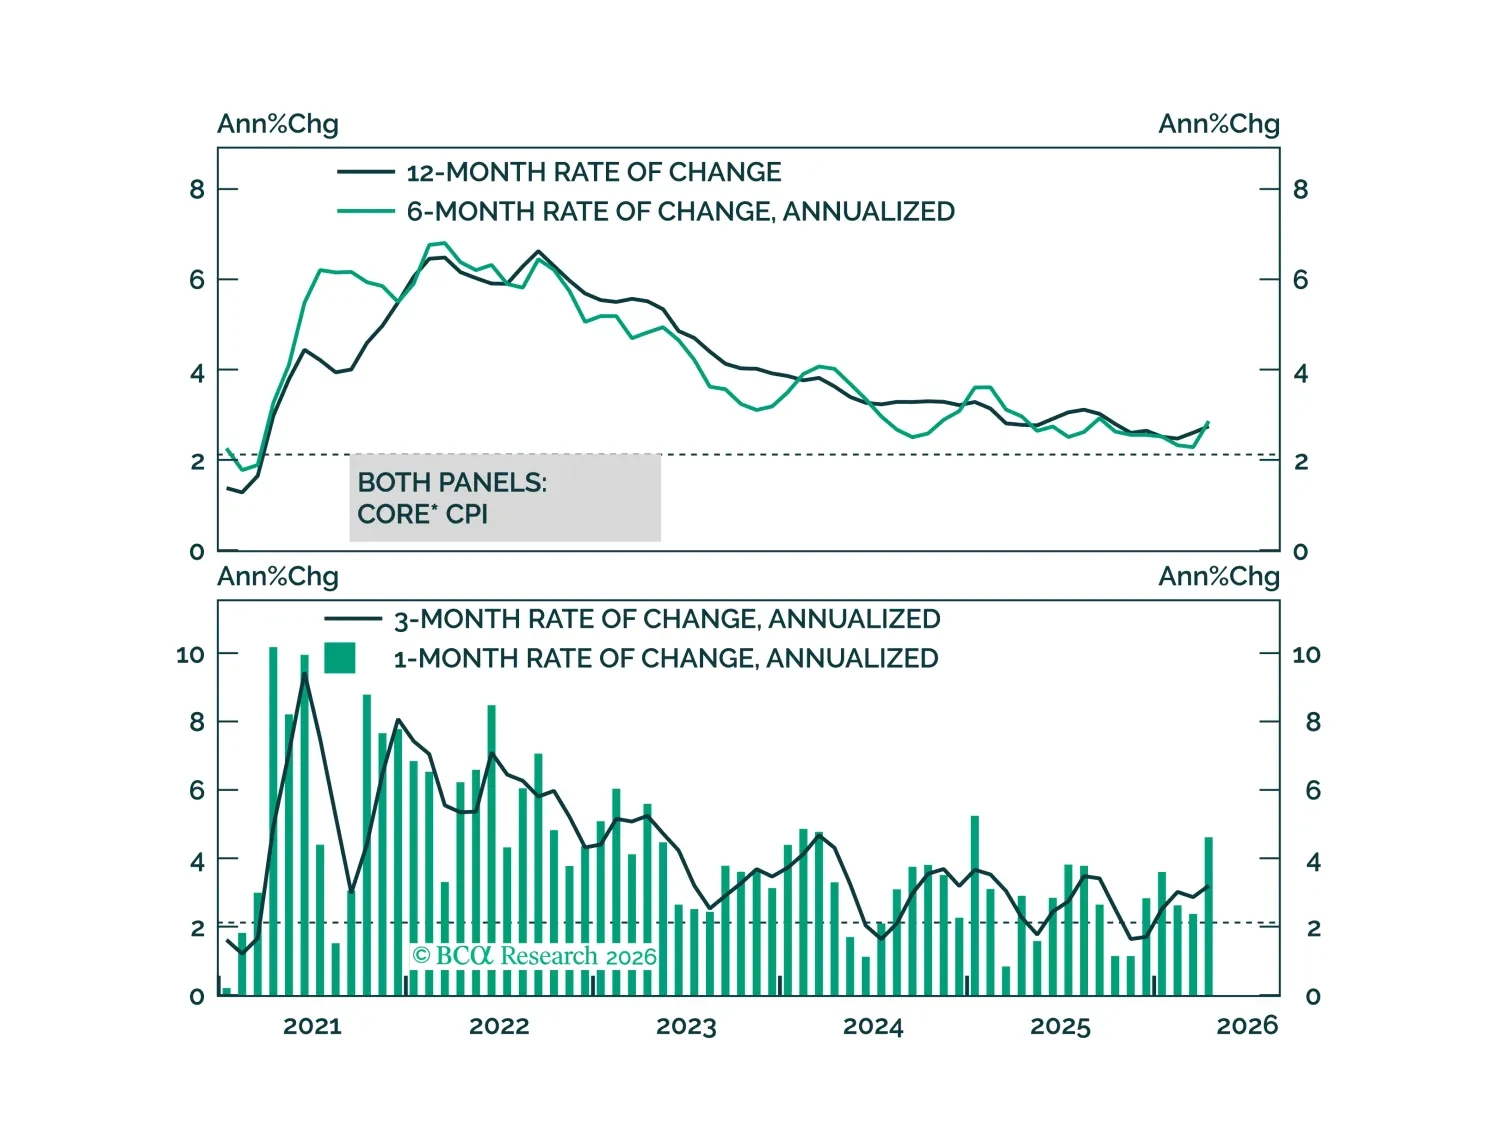
The April CPI report showed clear evidence of the direct effect of higher oil prices on inflation but, so far, limited evidence of passthrough to core.
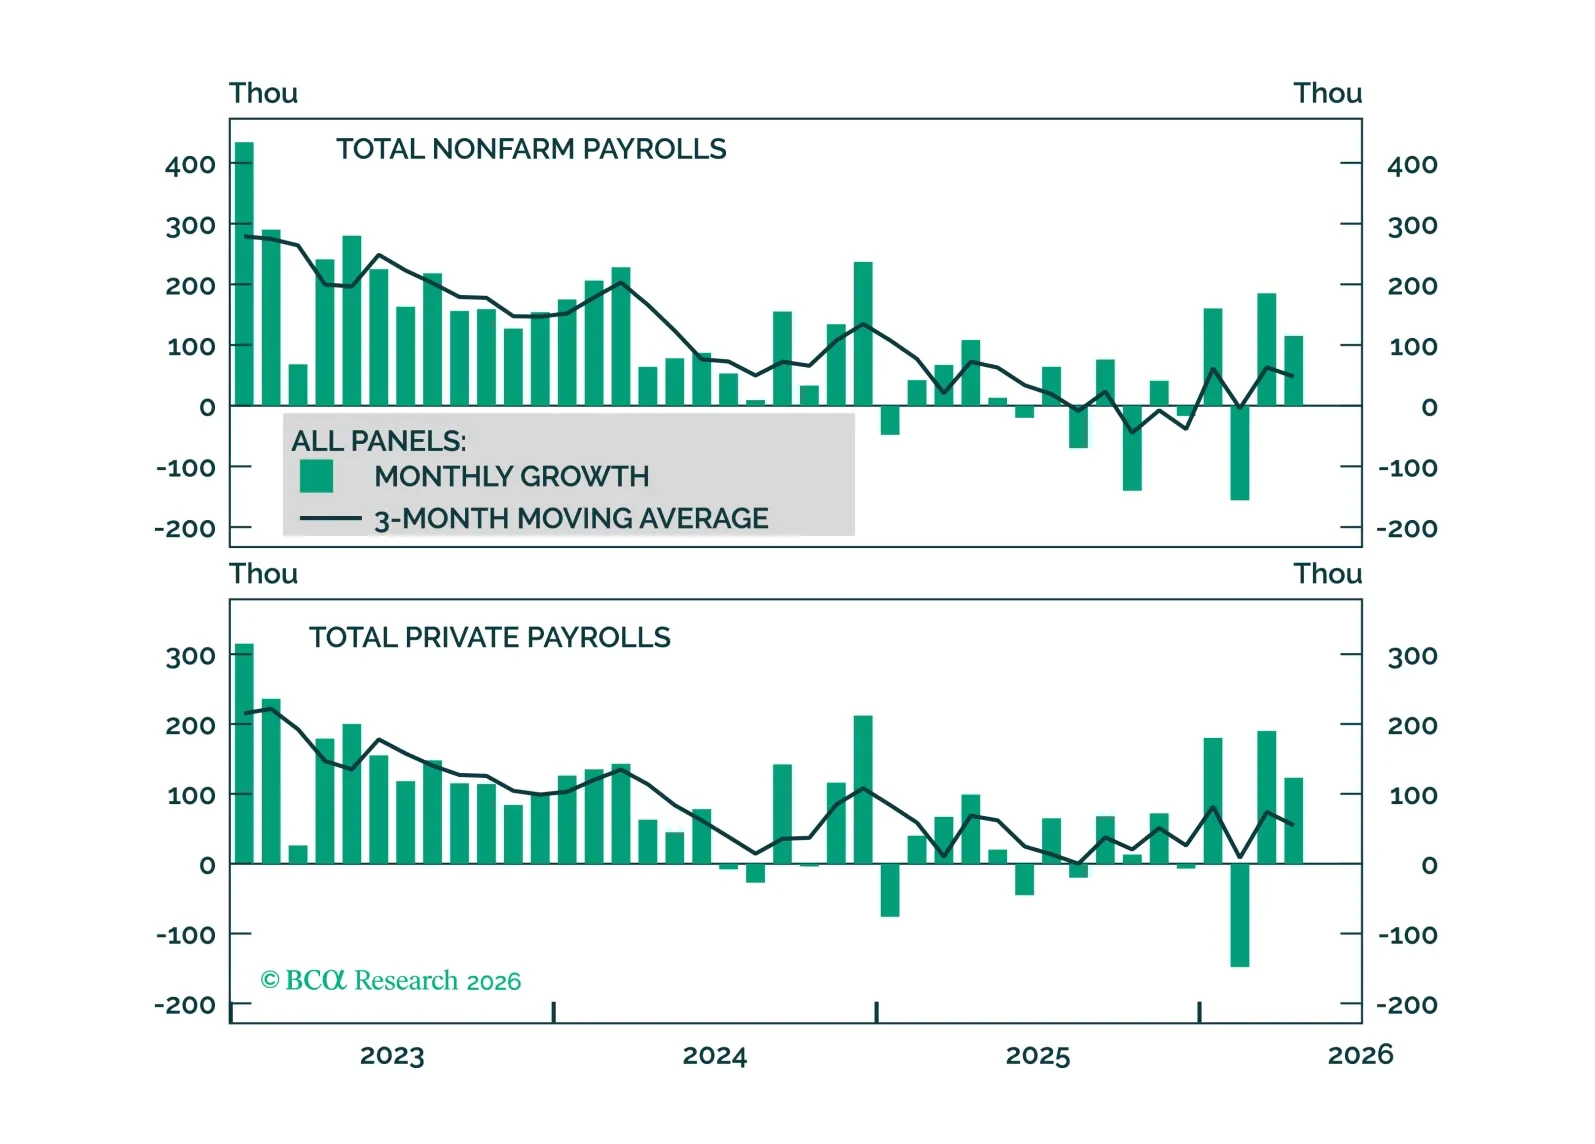
Improving job growth keeps Fed rate cuts off the table, but evidence of labor market tightening will be required before rate hikes become part of the discussion.
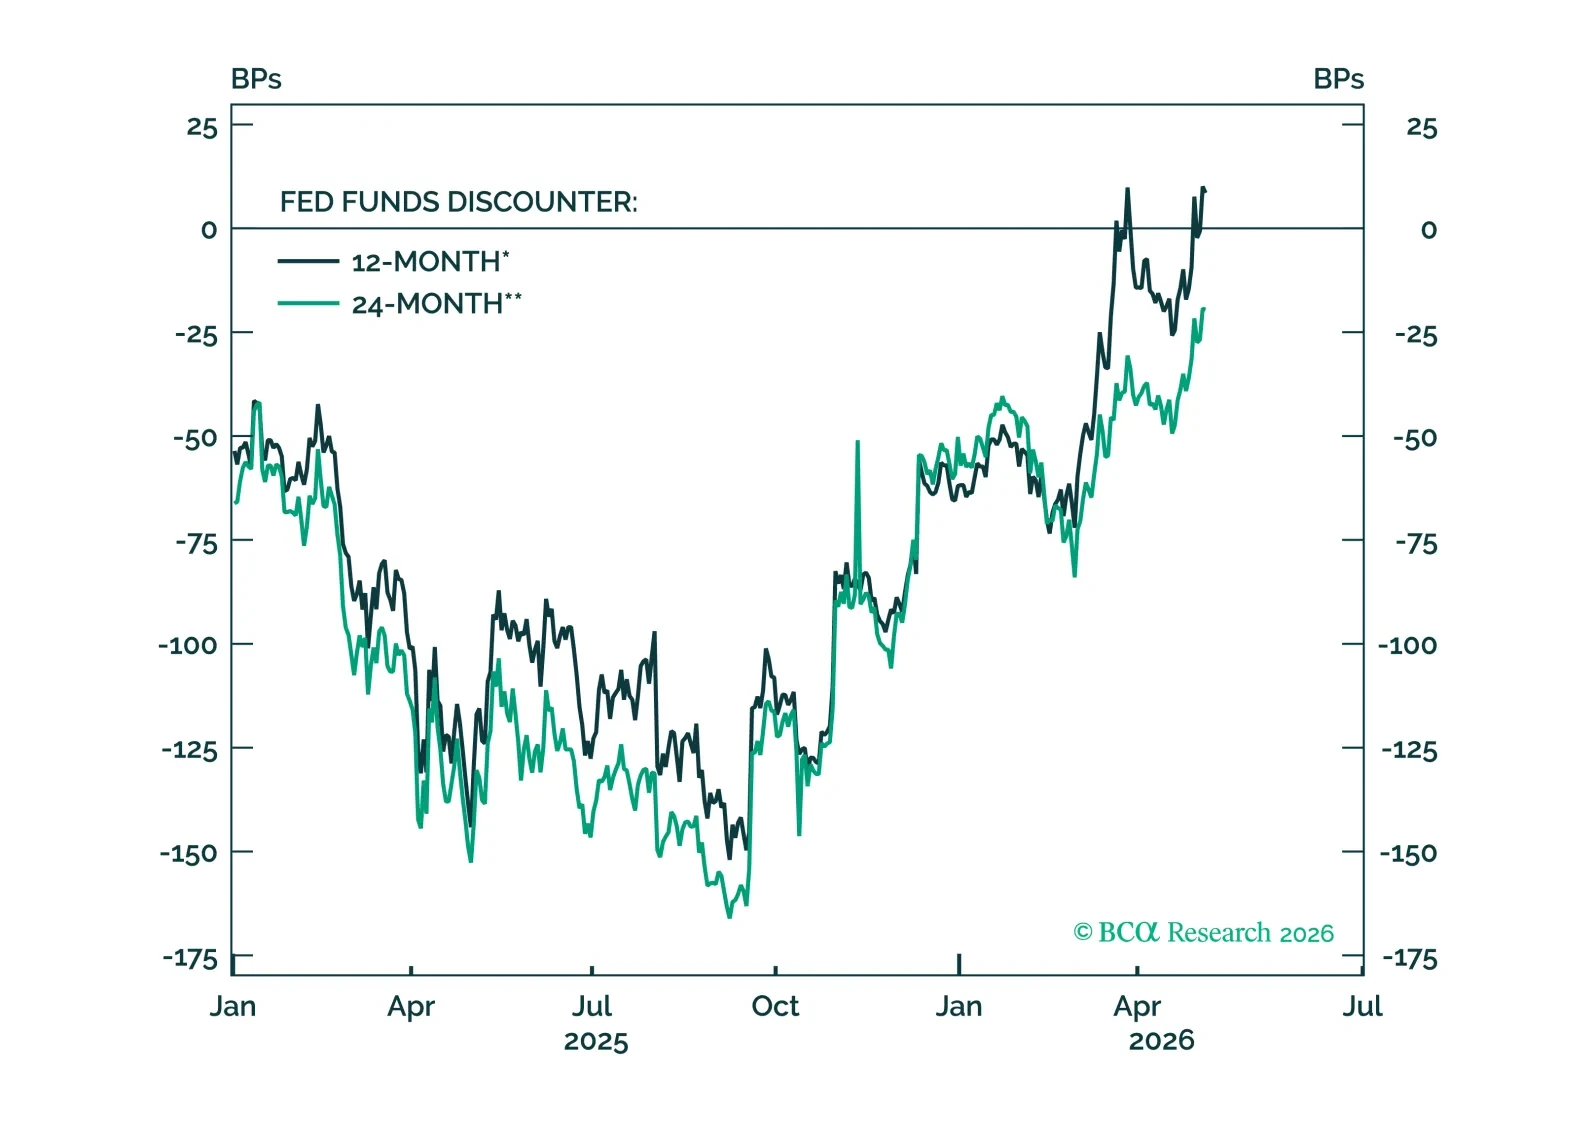
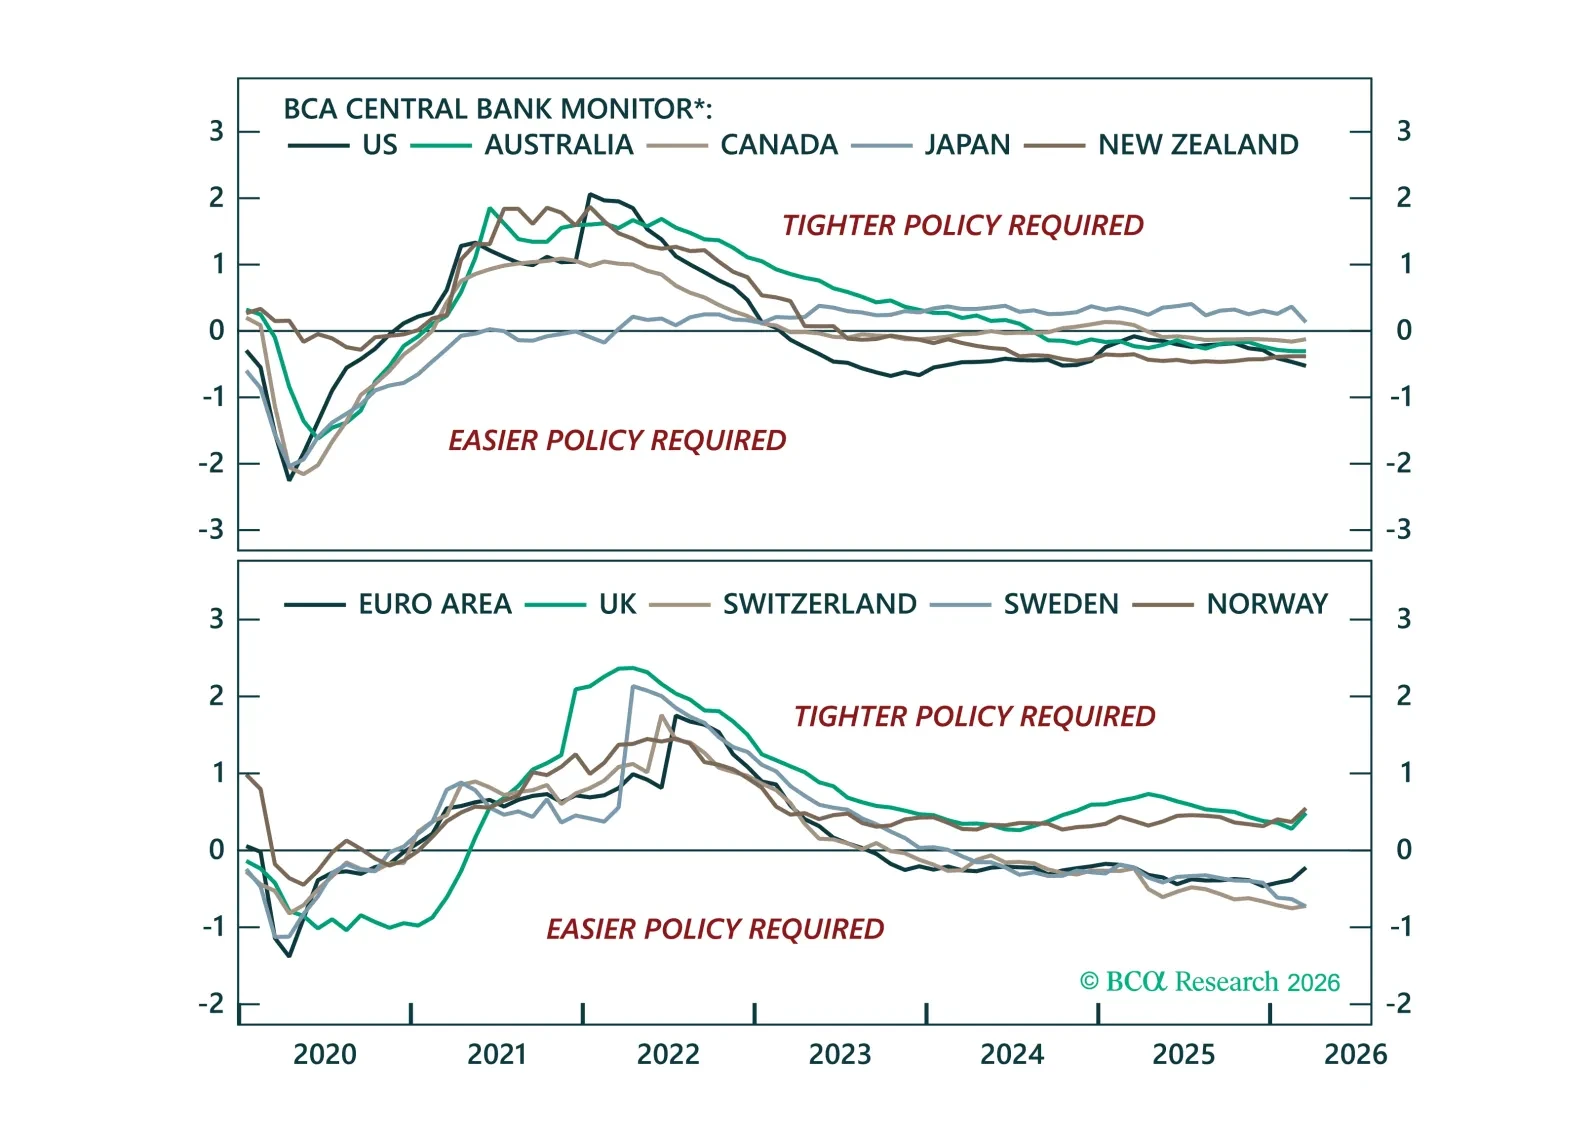
Central banks remain on hold amid heightened uncertainty. We rely on BCA’s Central Bank Monitors to assess the current policy stance of major central banks, and highlight the tactical opportunities across bond markets and currencies.