 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
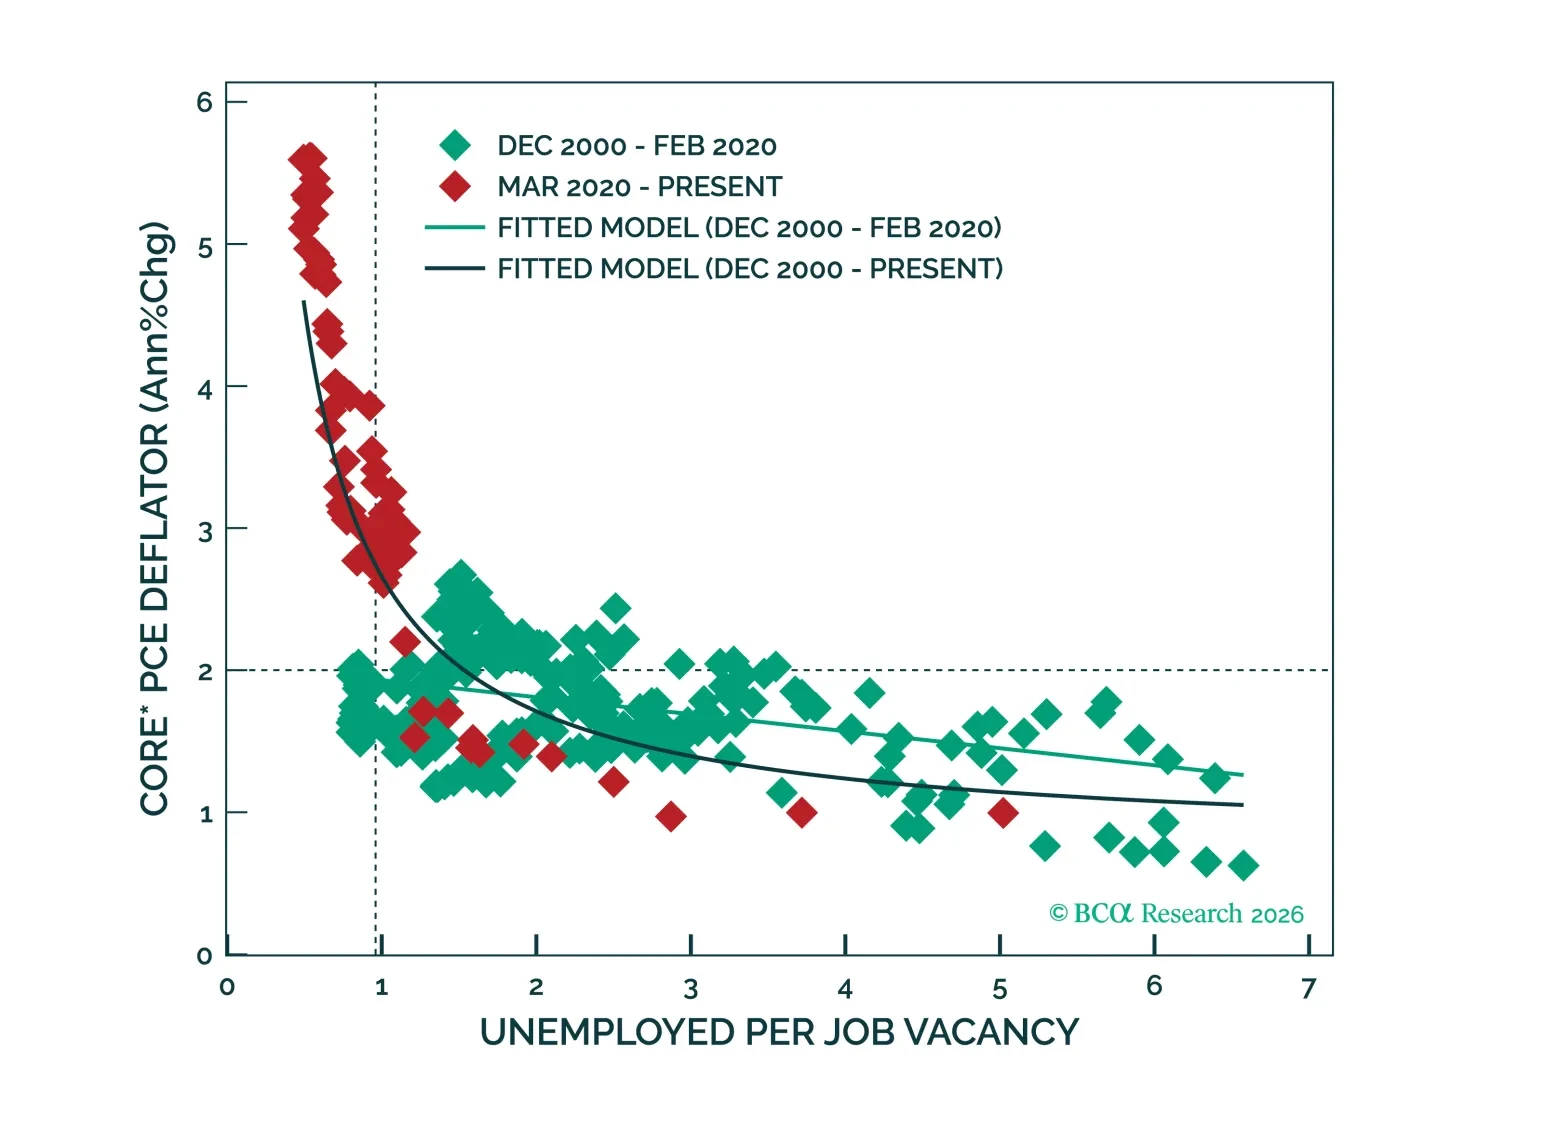
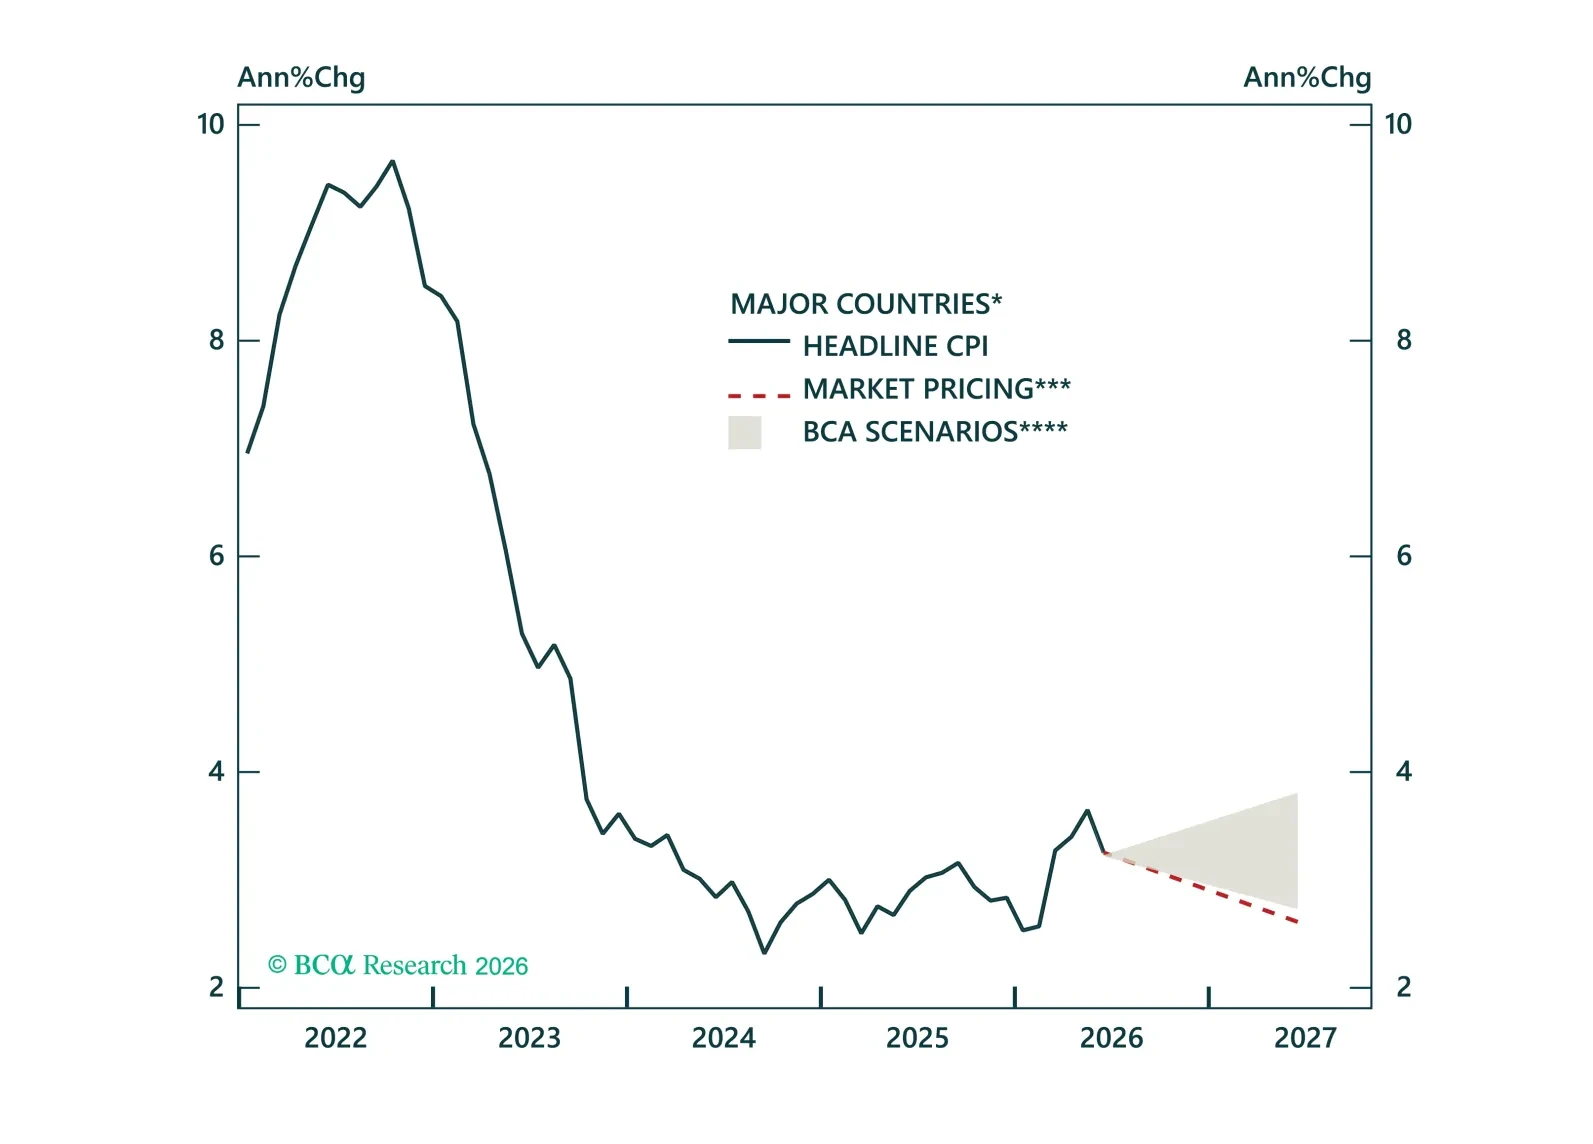
In this Strategy Insight, we assess how Middle East-related energy and shipping disruptions are shaping the global inflation outlook and review the implications for inflation-linked bond markets. We also examine the outlook for core inflation and the resulting implications for central bank policy and duration positioning.
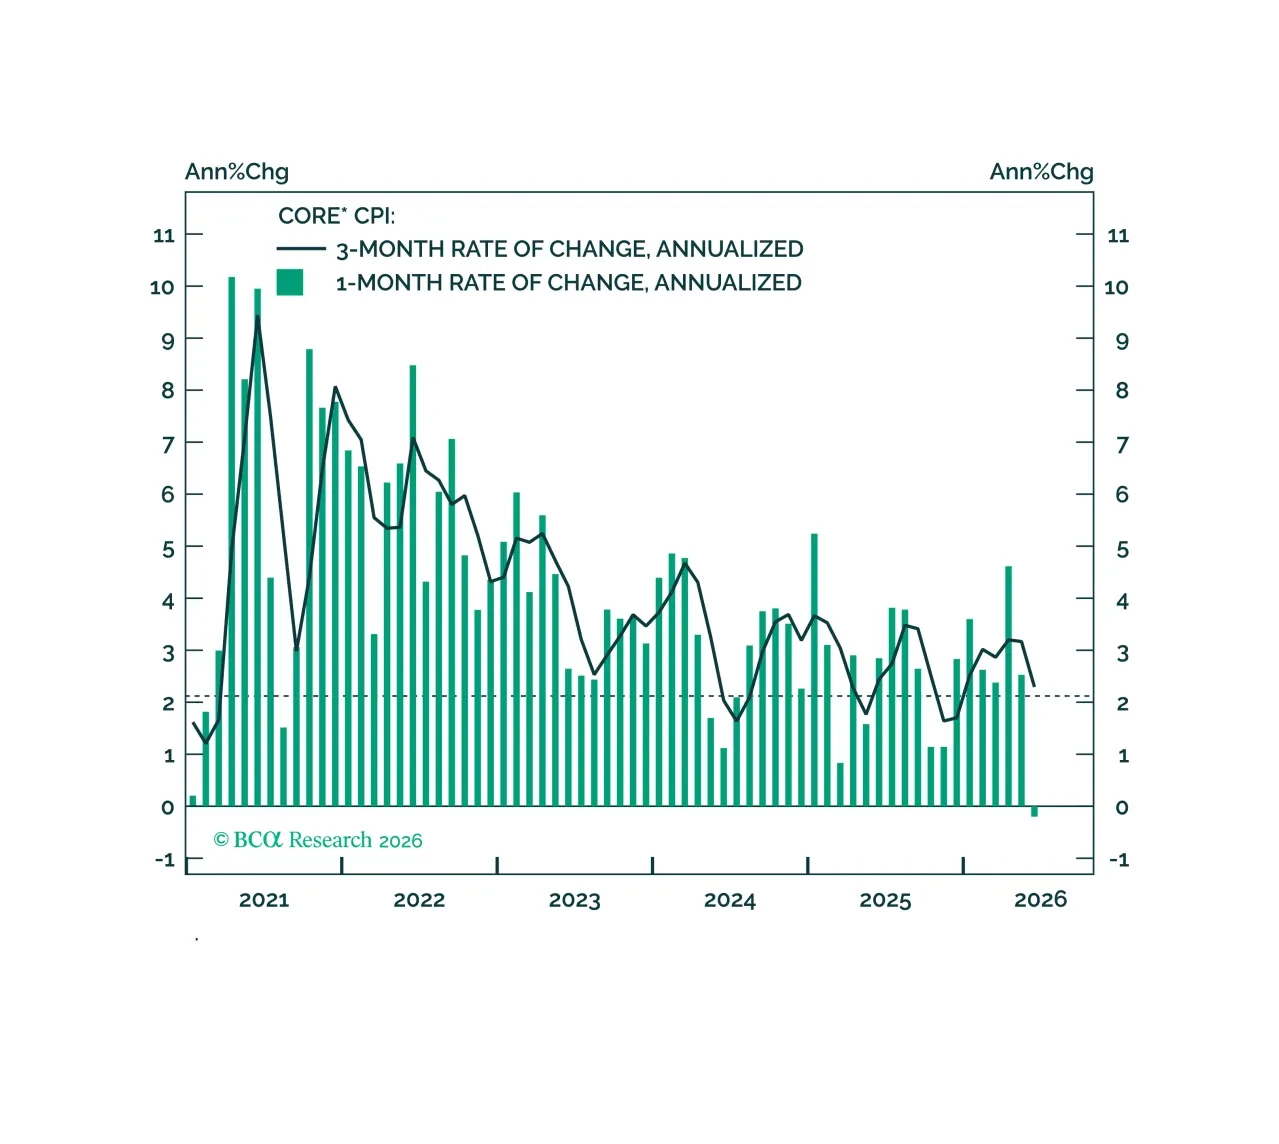
June’s low CPI reading rules out a July rate hike, but September is still on the table.
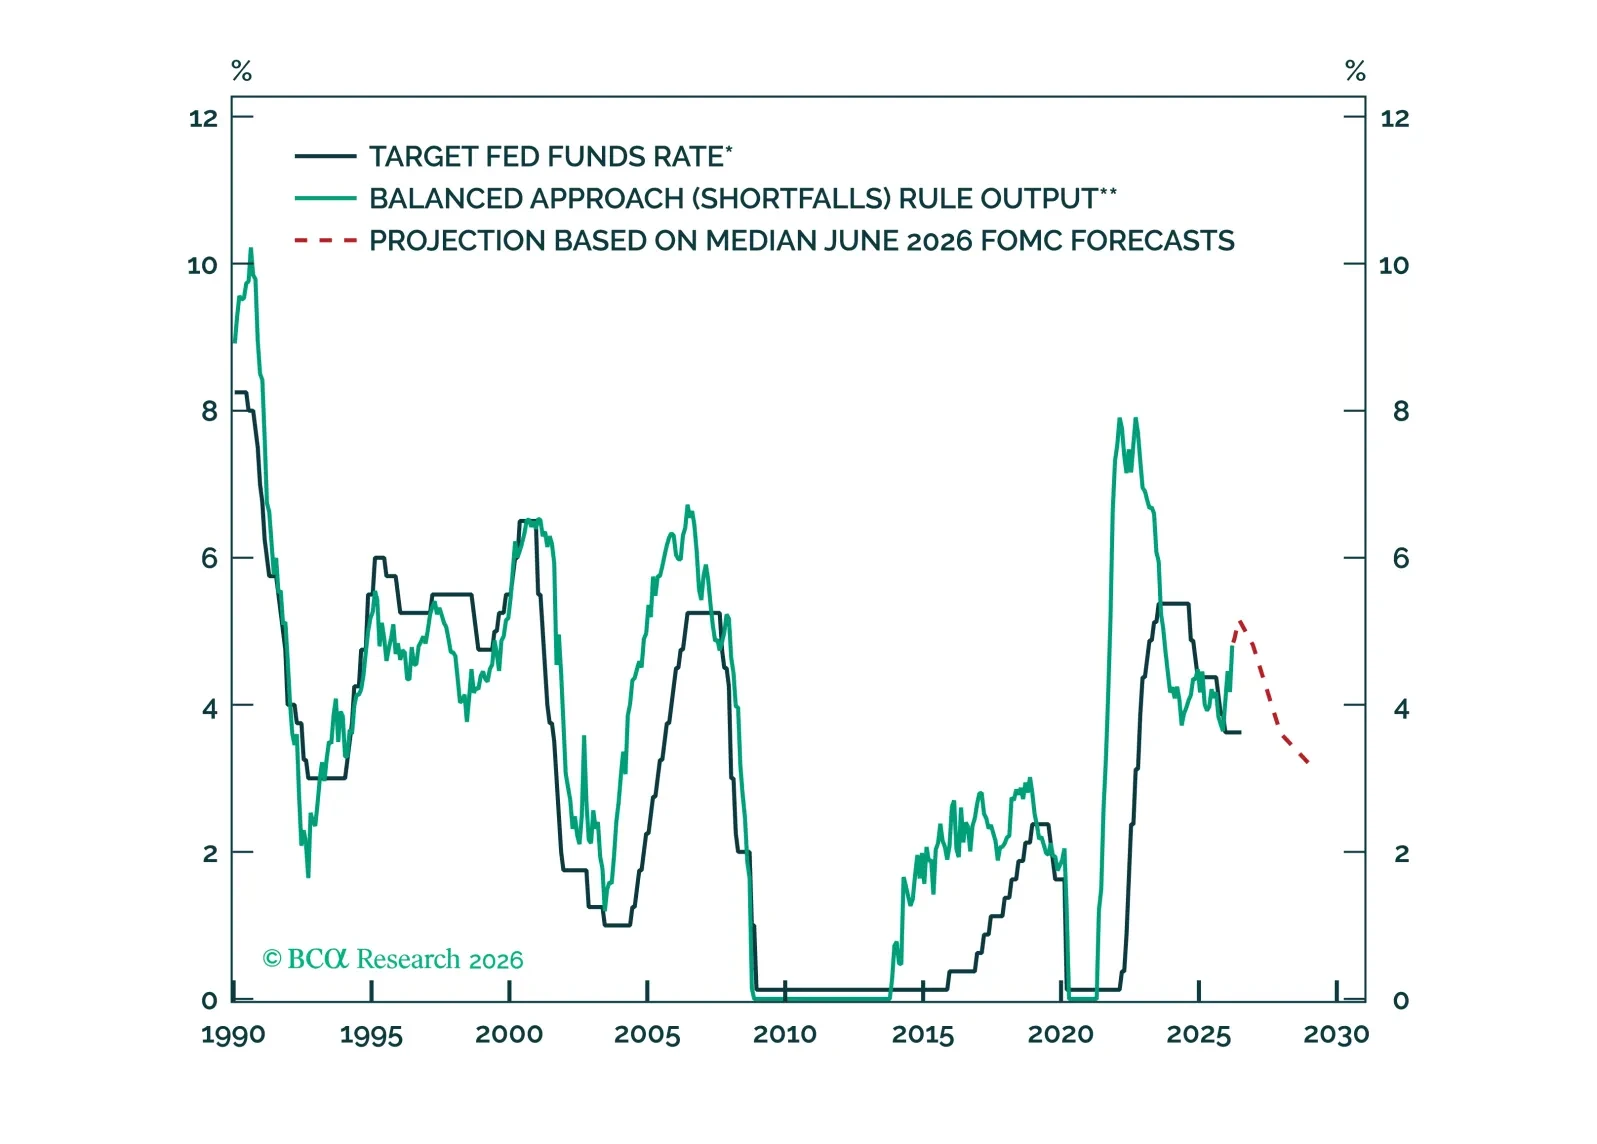
Goldilocks, with fault lines underneath. Our first joint FICC outlook lays out where growth, inflation, and policy are headed this quarter and where the calm could crack.
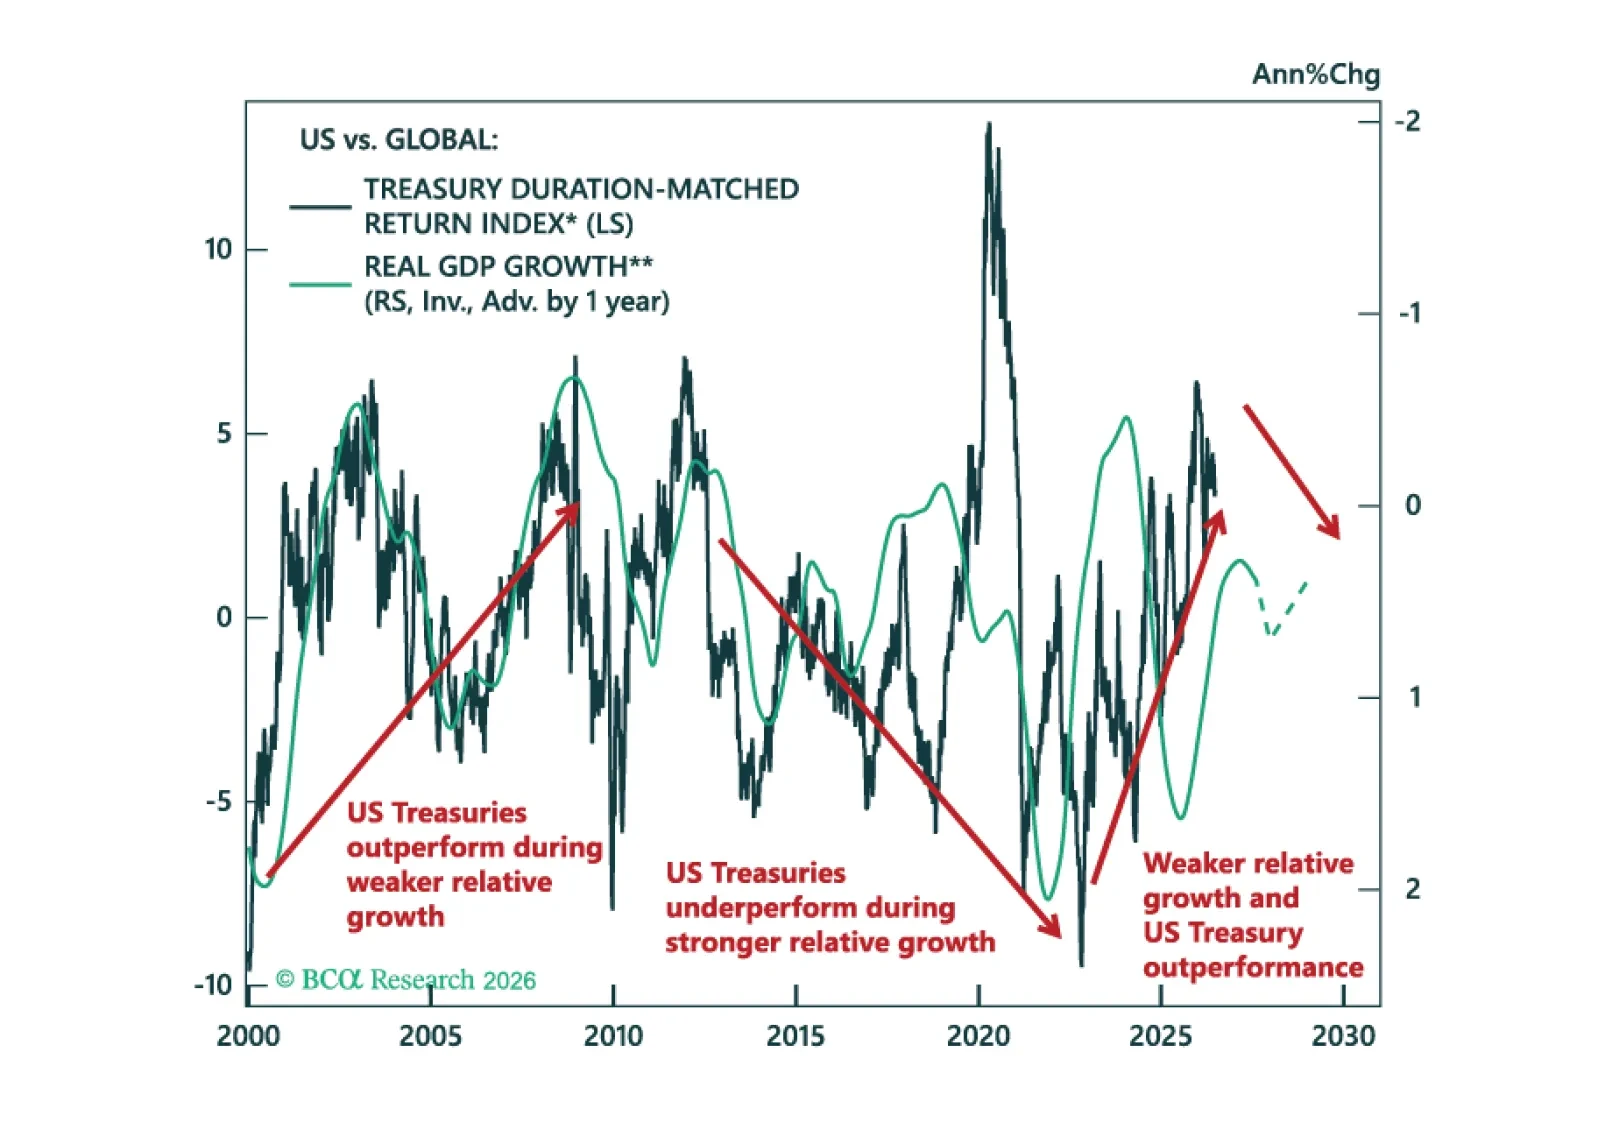
We review our Model Bond Portfolio performance for Q2 and look ahead as fixed income markets move beyond the US-Iran conflict, which is finding its kinetic equilibrium. Valuations and growth differentials are moving against continued US Treasury outperformance.
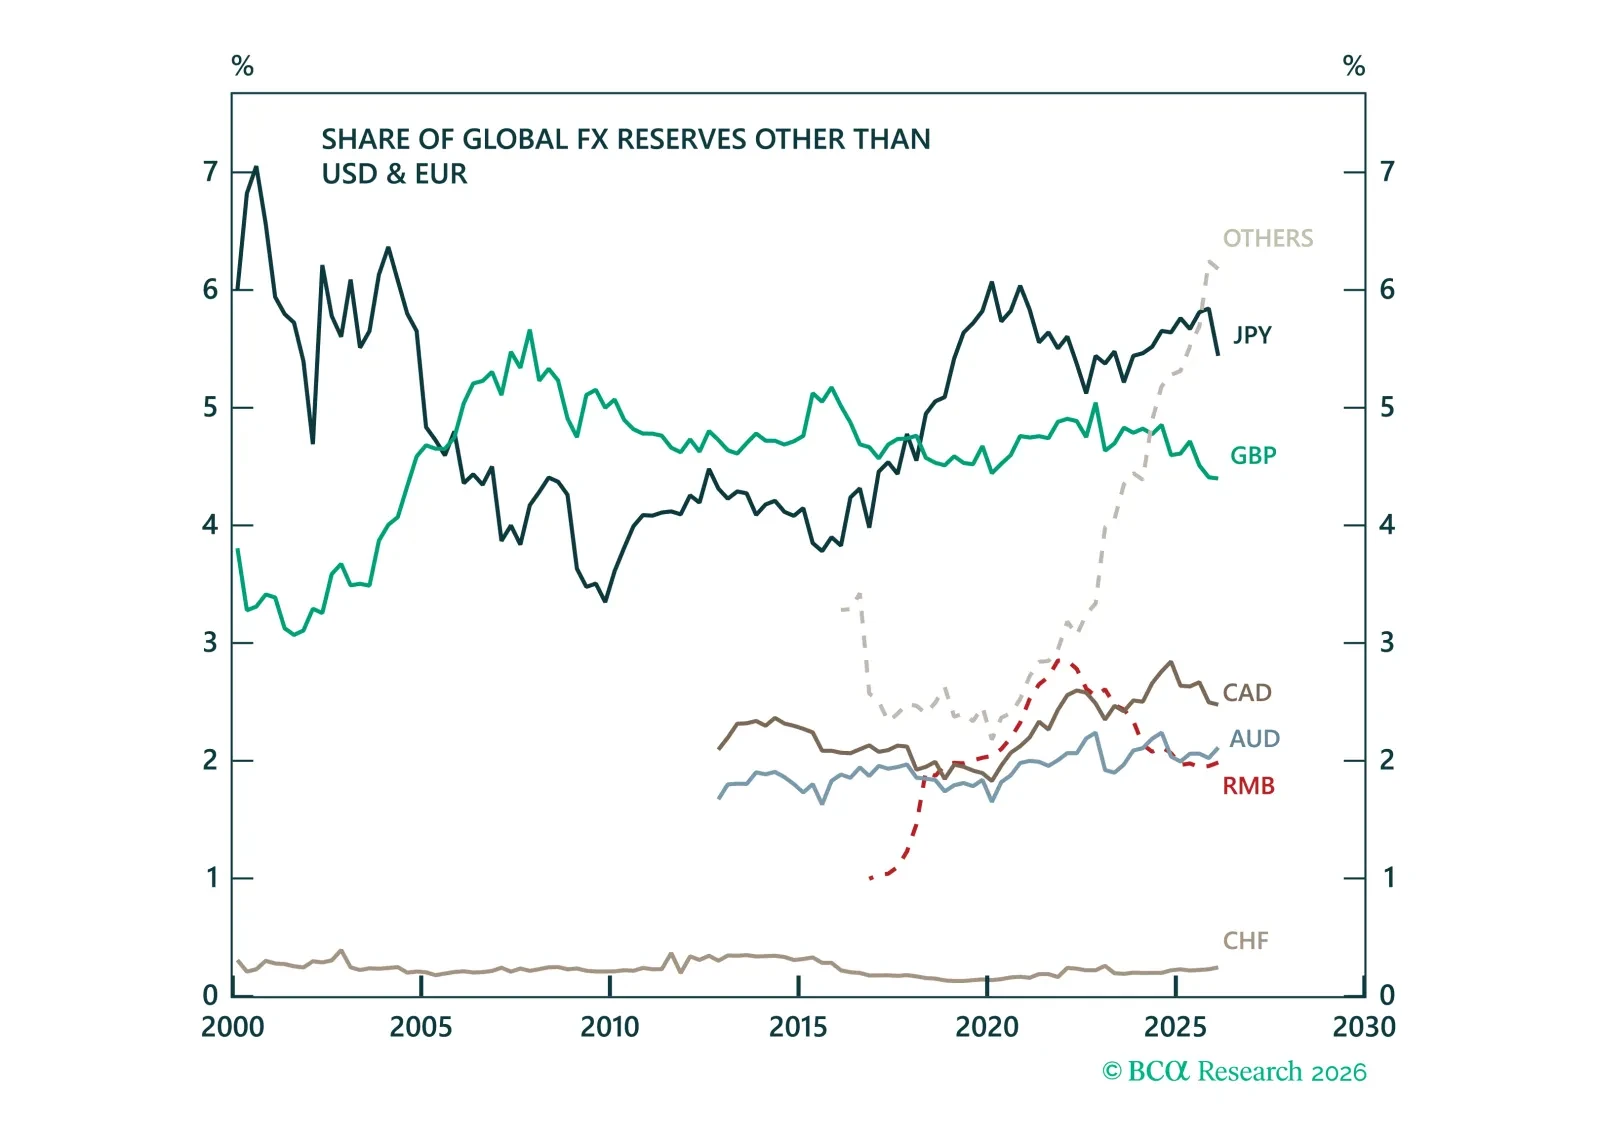
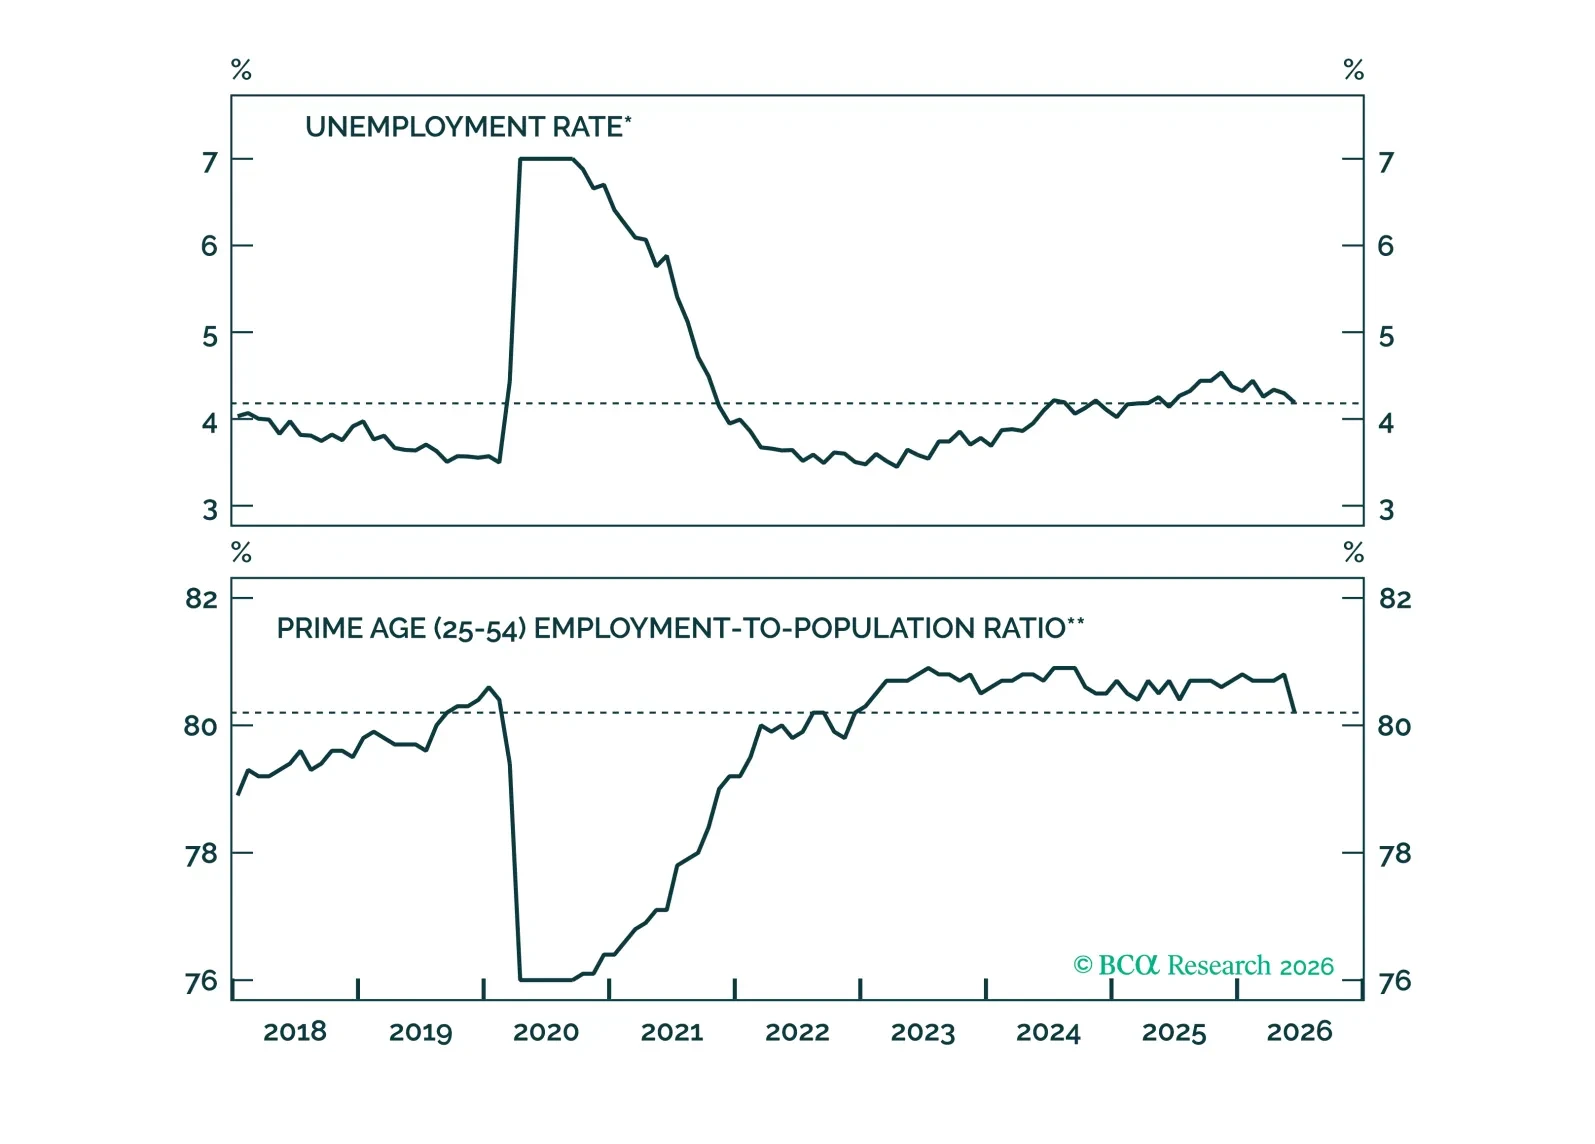
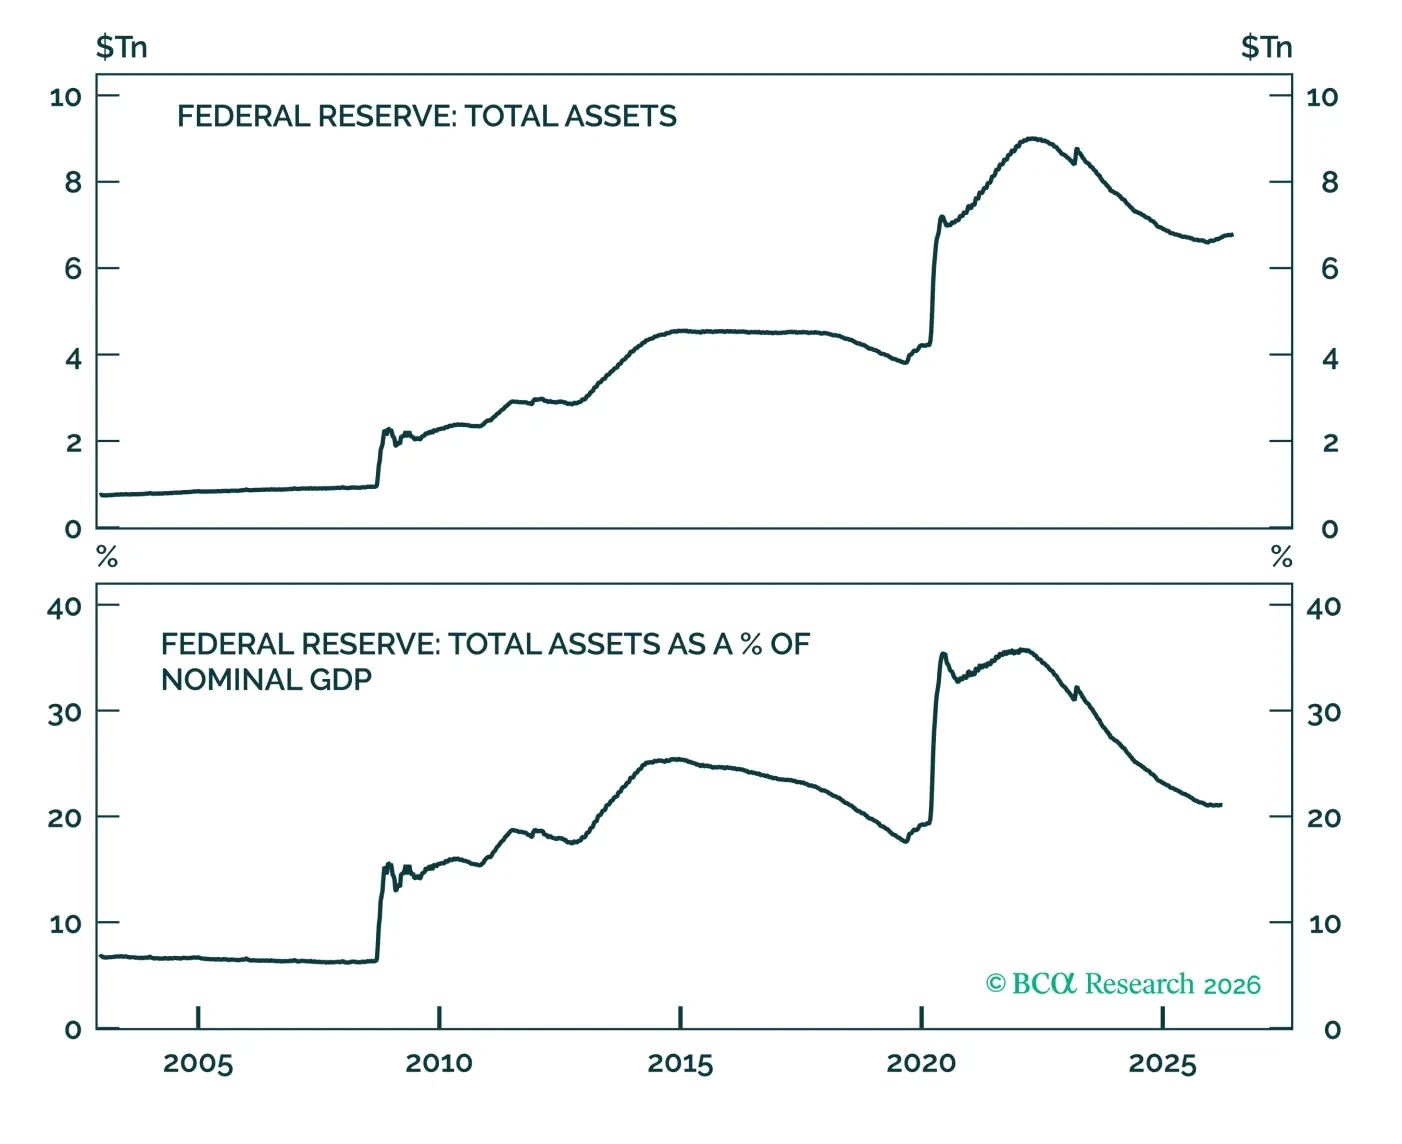
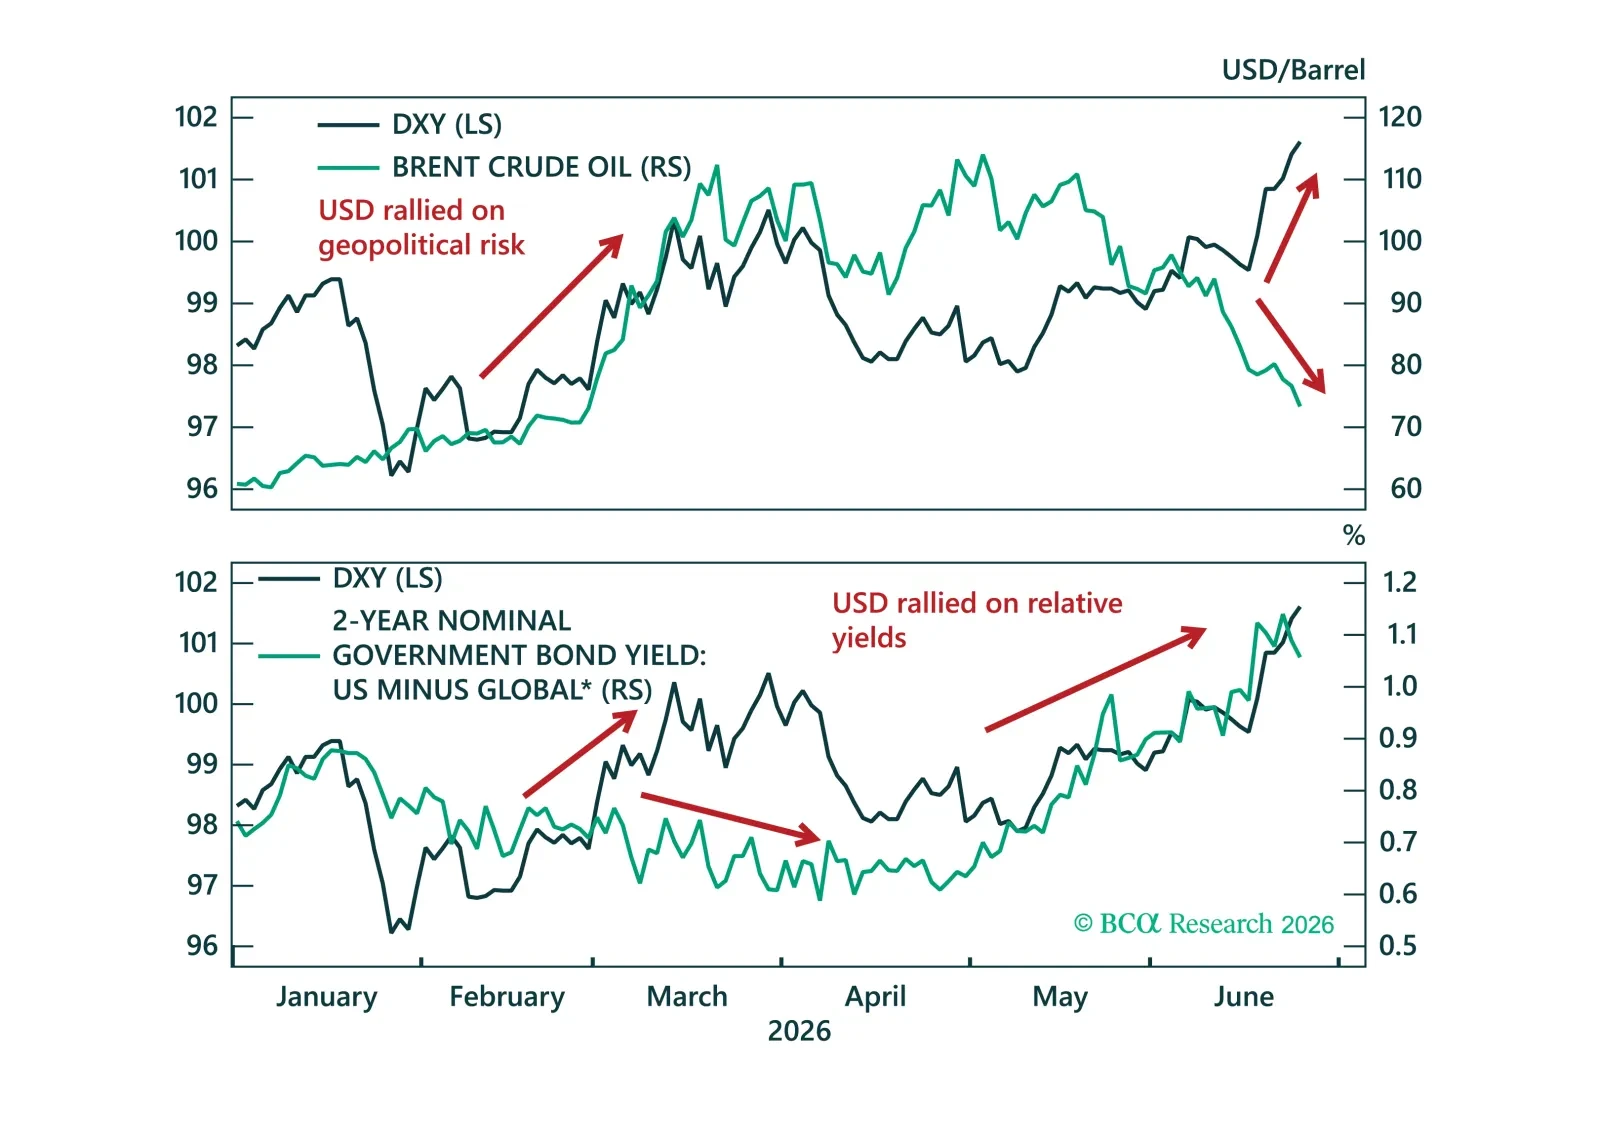
The dollar has had a strong run but its key supports from Fed repricing, positioning, and terms of trade are starting to fade. We close our tactical long USD positions and turn to short USD/JPY, where intervention risk makes yen shorts look increasingly dangerous.